Brazil

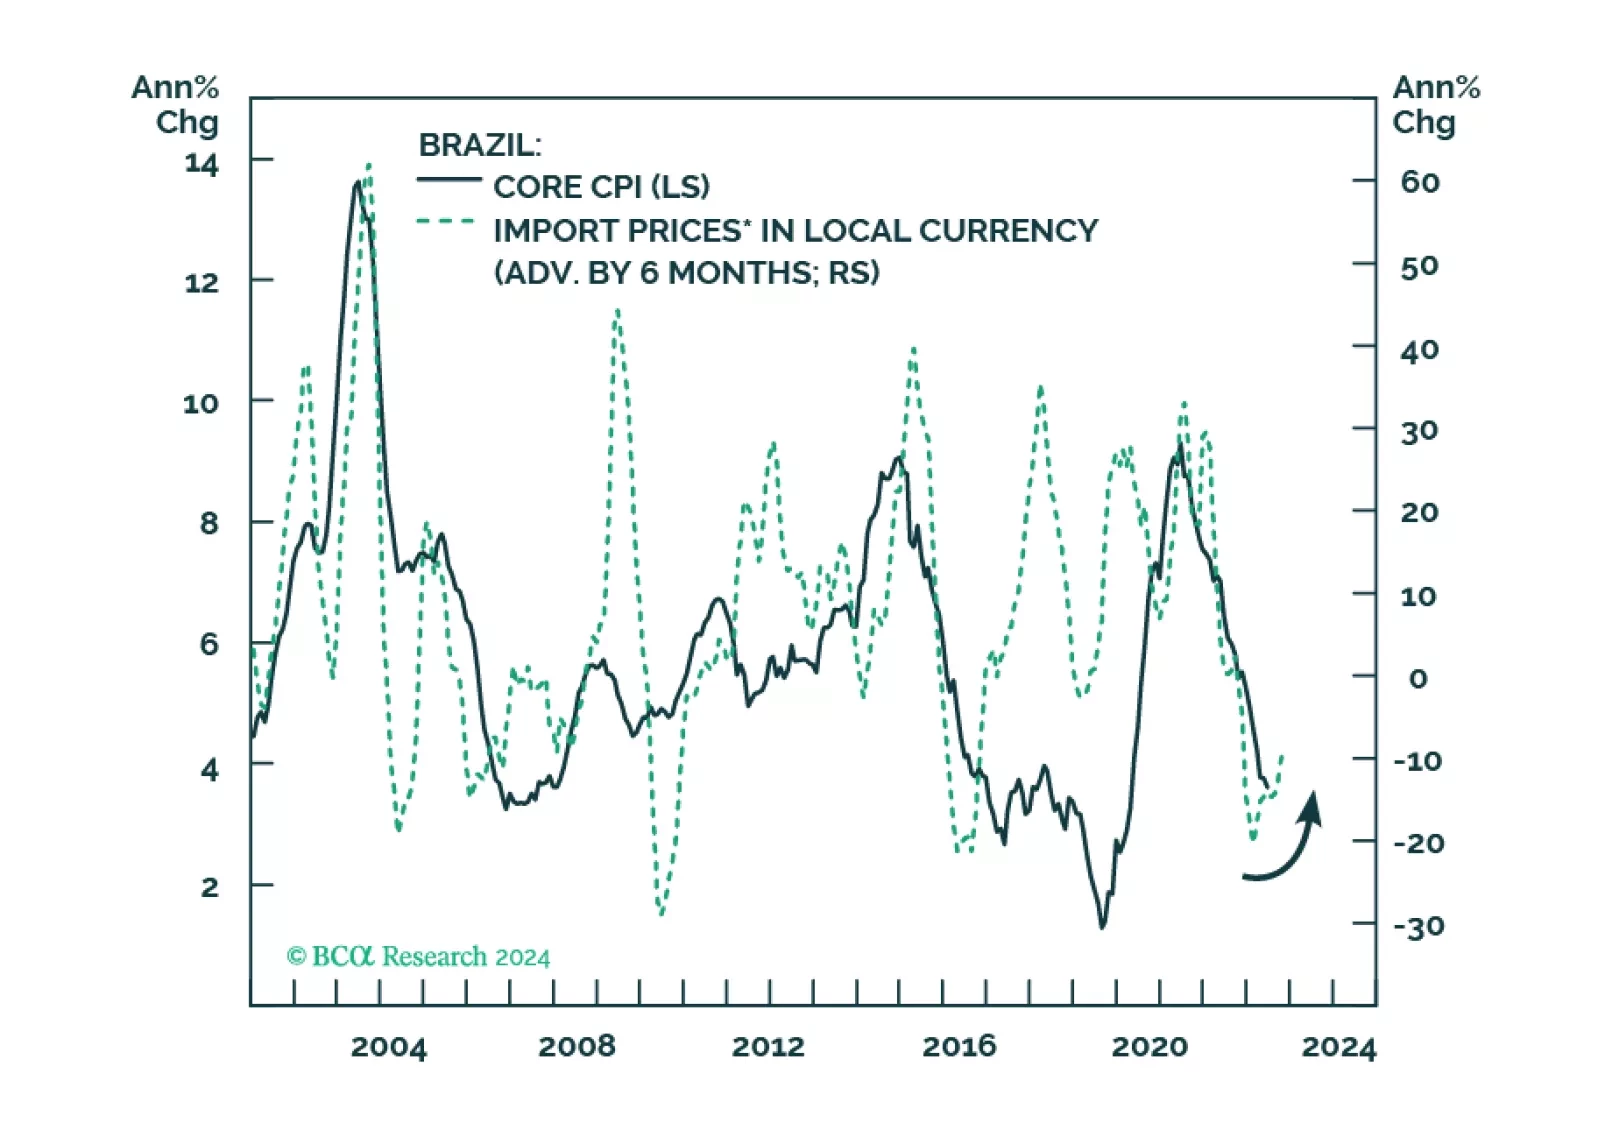
Brazil’s two macro demons – a rising public debt-to-GDP ratio and inflation – have resurfaced and will worsen over the coming months. Yet, President Lula will pay lip service to fiscal concerns without enacting meaningful cutbacks. In addition, a politicized COPOM will cut rates aggressively next year and fall behind the inflation curve. All in all, the selloff in Brazilian markets still has legs.
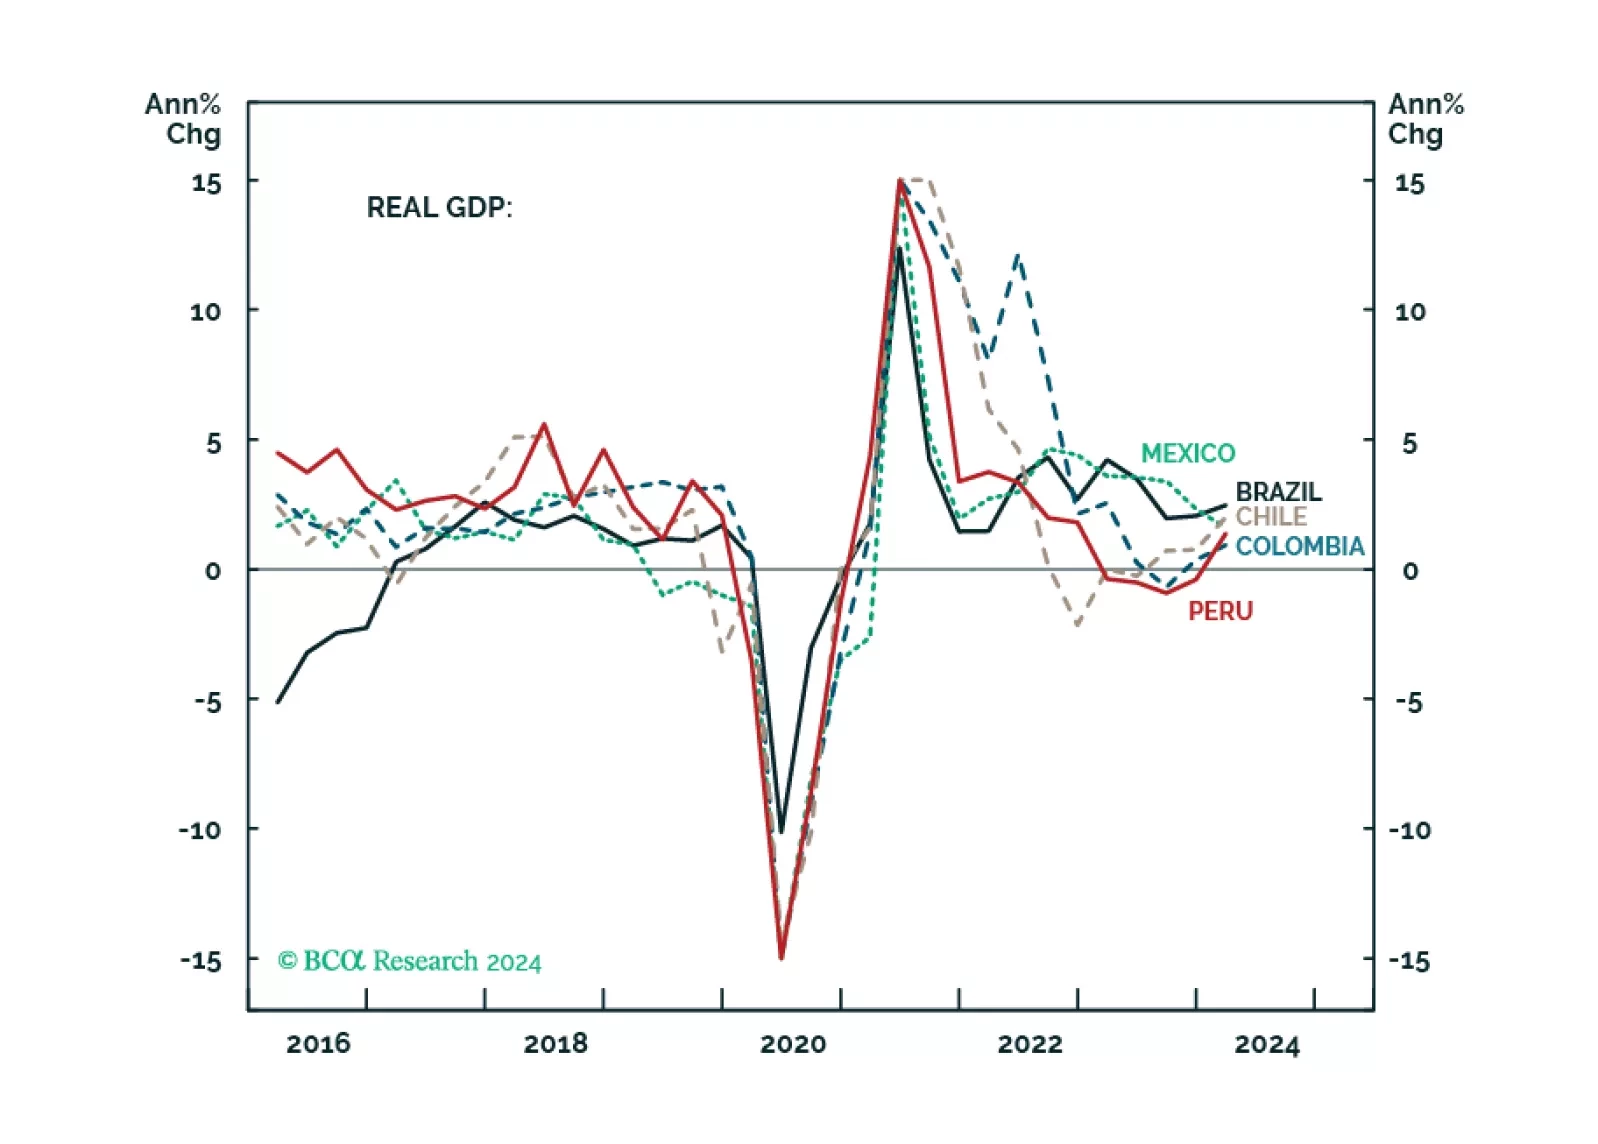
Non-trivial macro divergences have emerged between mainstream LATAM economies. This report compares and ranks Brazil, Mexico, Colombia, Chile, and Peru based on their business cycle outlook, macro policy stance, external accounts, and structural fundamentals. All in all, LATAM risk assets will fall in absolute terms given a strengthening US dollar and a global risk-off move in the coming months. Within LATAM, we favor Mexico, Chile and Peru, are neutral on Brazil, and bearish on Colombia.
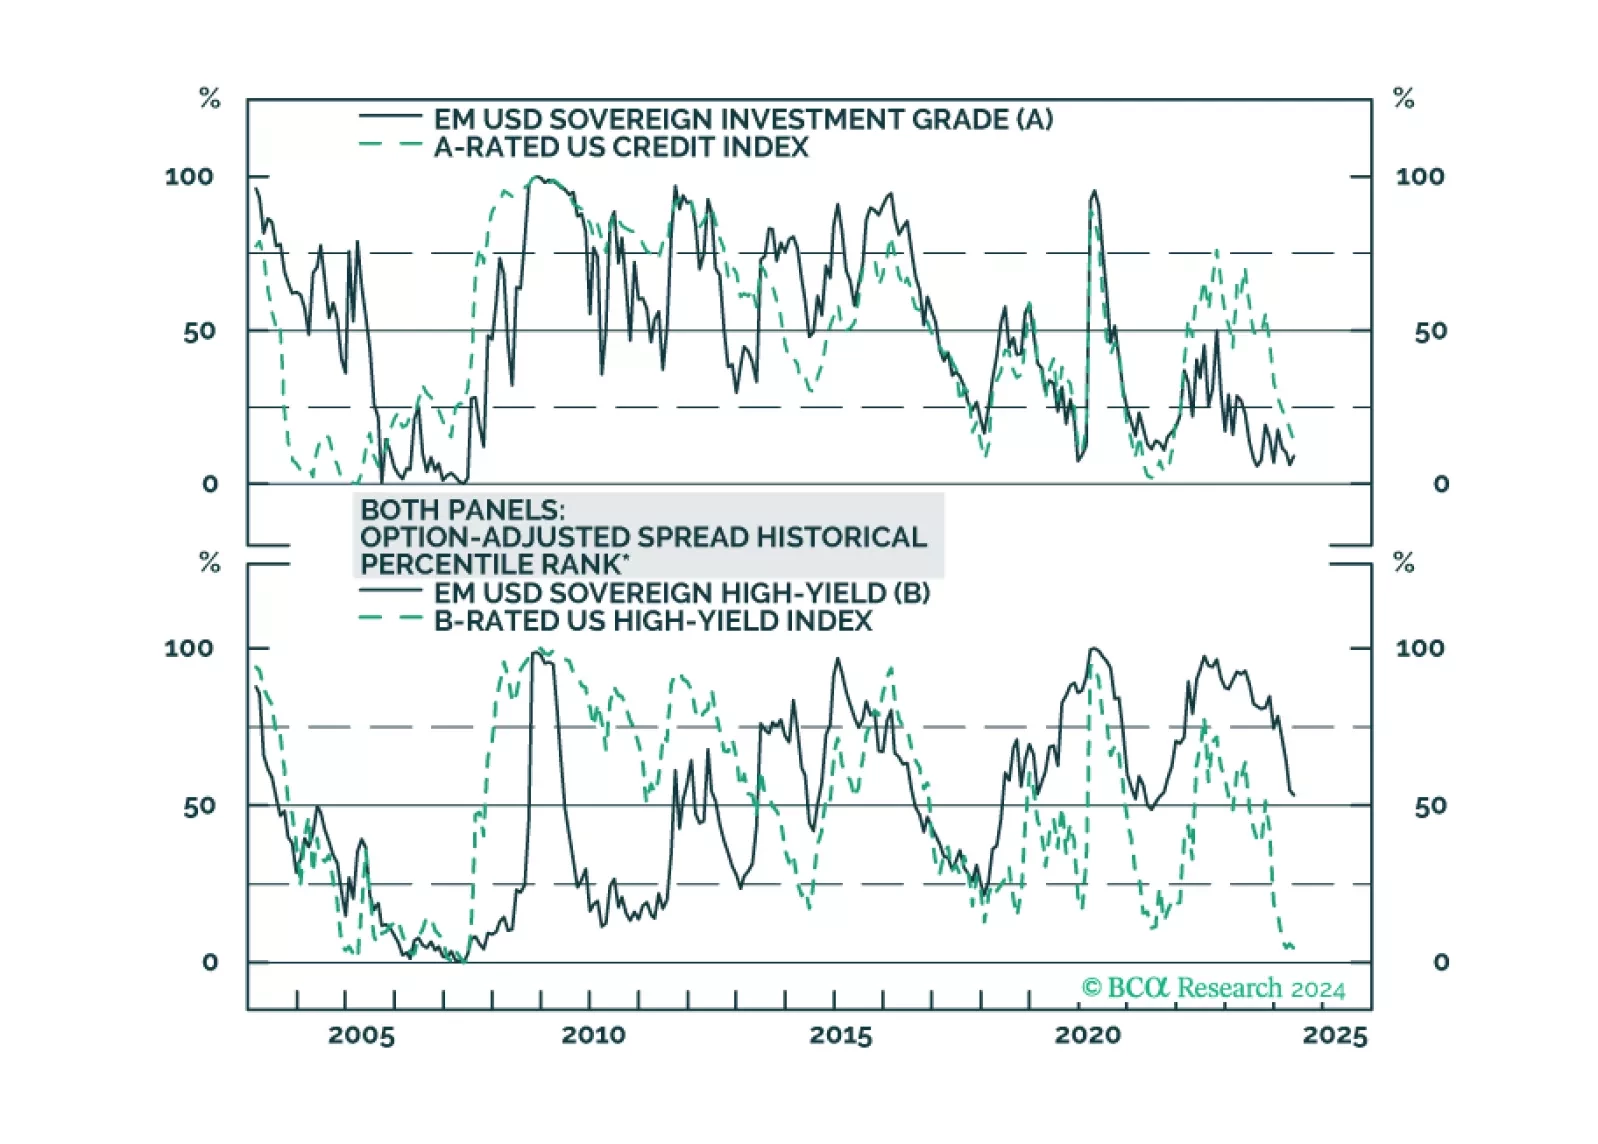
We dig into the USD-denominated Emerging Market Sovereign Index to see which credit tiers and countries offer value relative to US Credit.
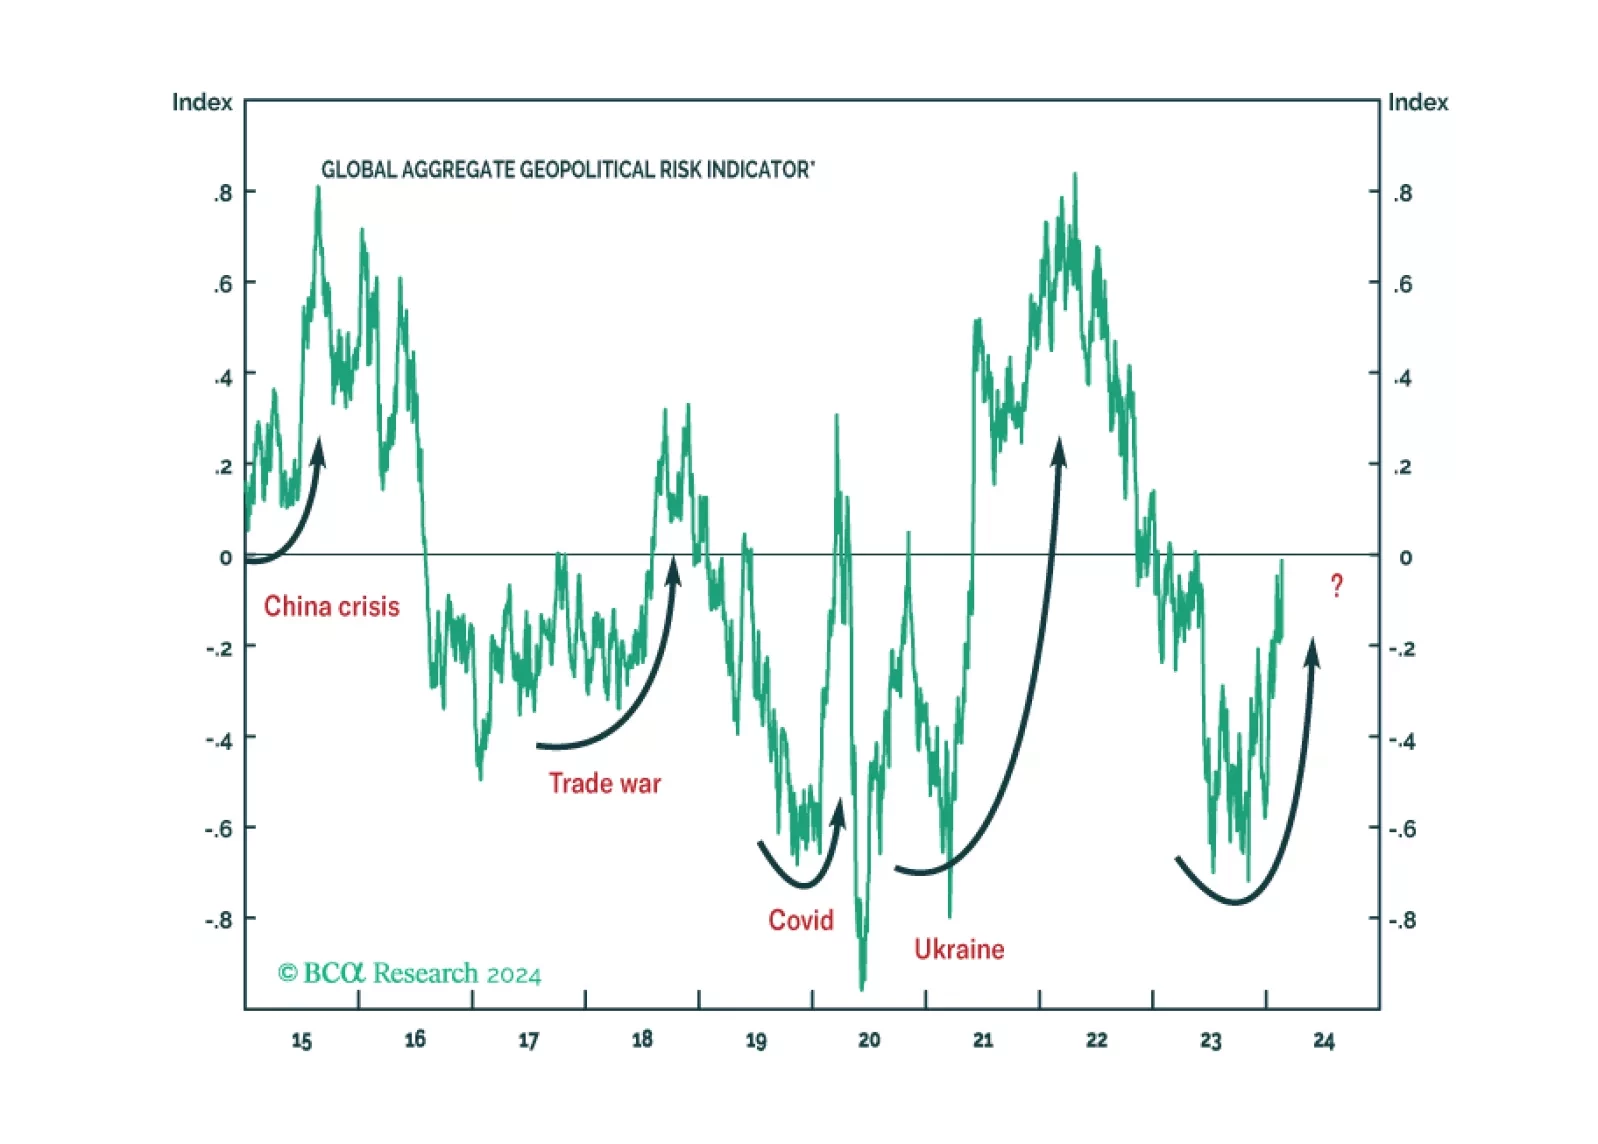
While 2024 will see various election risks, global geopolitical uncertainty is driven by the US election and its struggle with Russia, China, and Iran. The stock market can manage local domestic political risk. But it will correct upon a major outbreak of geopolitical uncertainty.
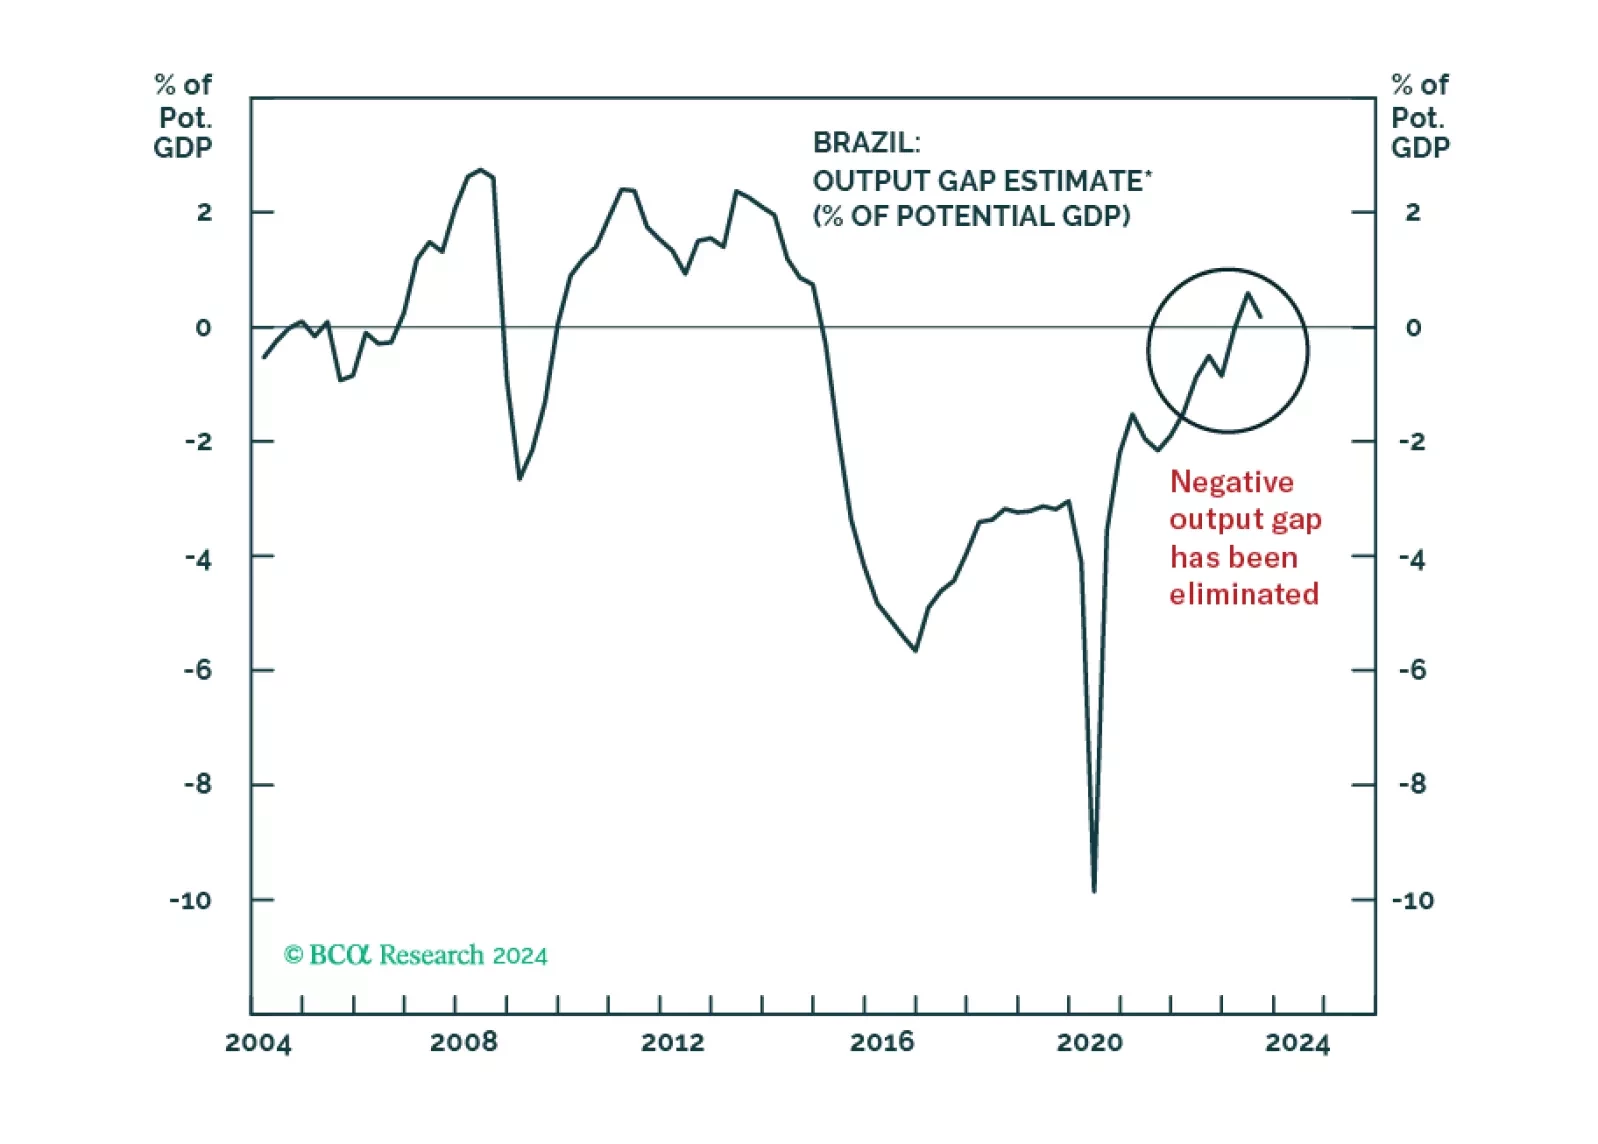
The Brazilian government and the central bank will be prioritizing growth over curbing the fiscal deficit and inflation. The outcome of an easy policy mix is that growth and inflation will be higher relative to market expectations, and real interest rates will drop considerably. We recommend that investors go long mid- and small-cap stocks on a pullback and inflation-linked bonds. However, foreign investors should hedge the currency risk.

In this report, we explore Brazil’s inflation and monetary policy outlook, the Lula administration’s back-and-forth between pragmatism and populism, and how these factors will affect Brazilian financial markets going forward. All in all, we believe Brazilian risk assets will be in a trading range relative to their EM peers in the next 12 months.