Emerging Markets
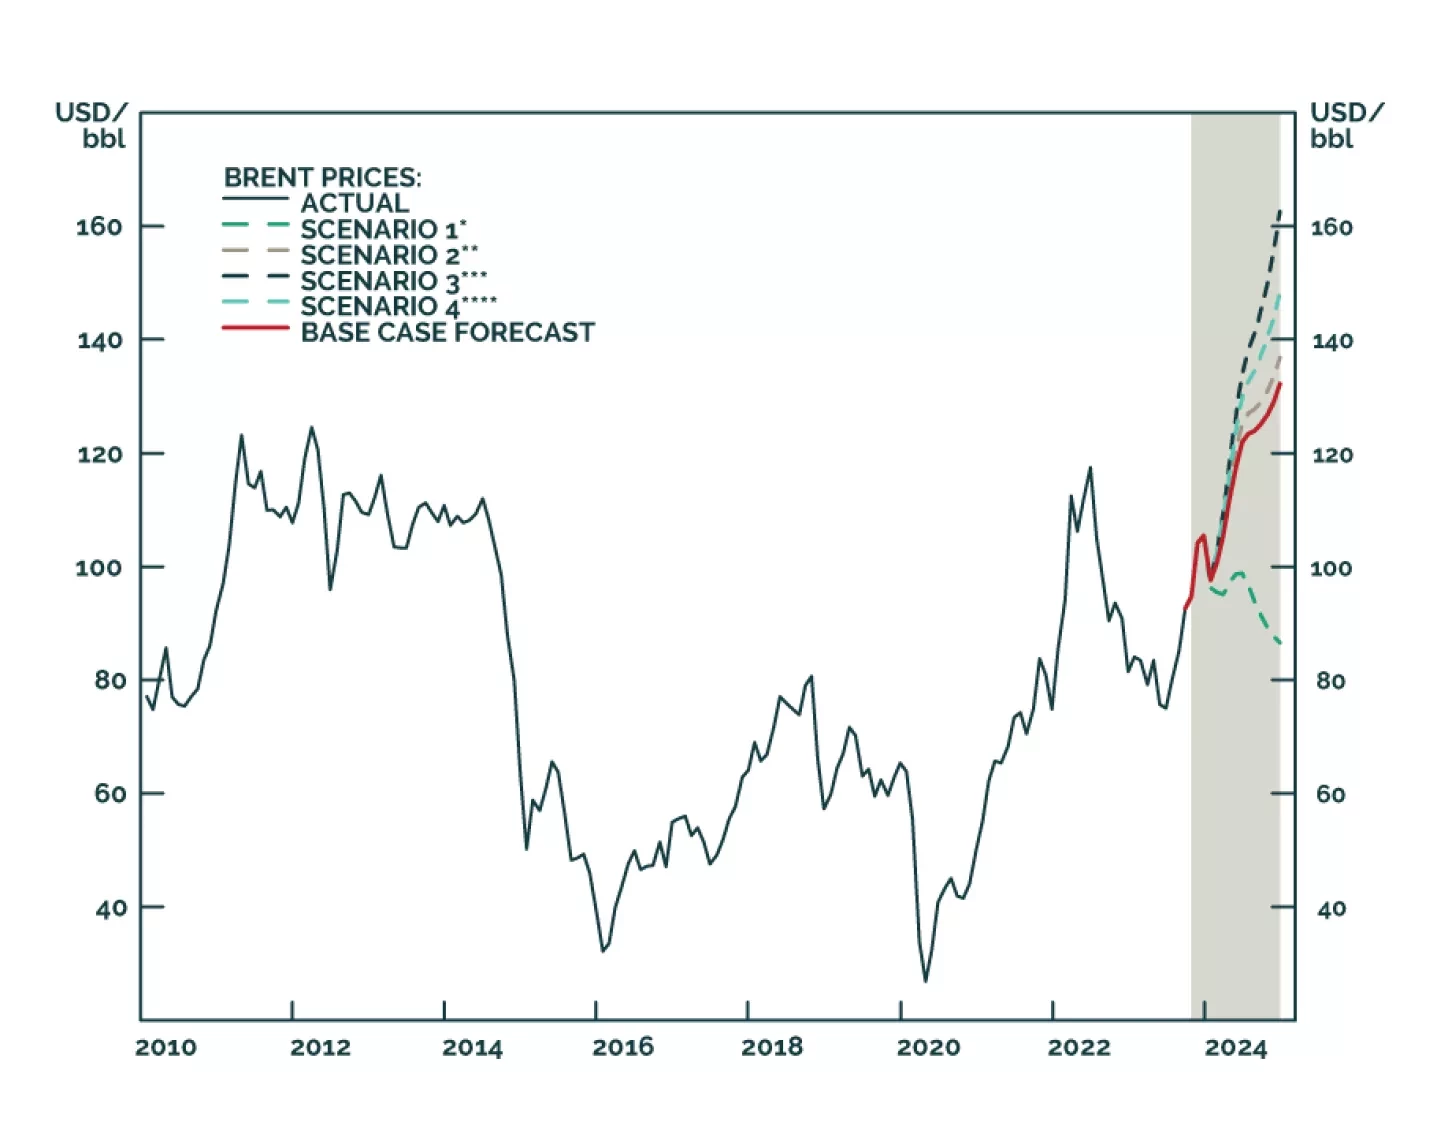
Despite higher uncertainty, our Brent price forecasts remain unchanged at just over $101/bbl for 4Q23 and $118/bbl for next year. We remain long equity exposure to oil and gas producers via the XOP ETF, and commodity exposure via the COMT ETF. We also remain long $100 Dec24 Brent calls and long 1Q24 Brent futures vs. short 1Q25 Brent futures in anticipation of stronger backwardation.

The Israeli-Arab crisis is more likely to expand and cause oil disruptions than market consensus holds. Close long dollar trades and go long energy and defense stocks relative to cyclicals.
Domestic auto sales in China will likely have anemic growth over the next three years. Yet, Chinese automakers are set to gain a larger share of the global market. Go long Chinese automakers / short global ones.
As global financial institutions like the IMF draw attention to the real-estate crisis in China, the CCP will be forced to step up regulatory and restructuring efforts to contain its spread and limit further contagion domestically and globally. The Party also will be forced to deliver stronger fiscal- and monetary-policy support to beleaguered banks and developers. We expect it to do so, which keeps us bullish energy and metals. Failure raises the odds of a collapse in the property markets, which would be socially destabilizing, and lead to greater risk aversion and volatility globally.
Hamas’s attack on Israel raises the odds of a wider conflict in the Gulf, which would lead to higher oil prices. Given the response of oil prices Monday, markets appear to be relatively restrained in their assessment of a sharp escalation in prices. However, this is early days in a strategy that is just revealing itself.