Equities

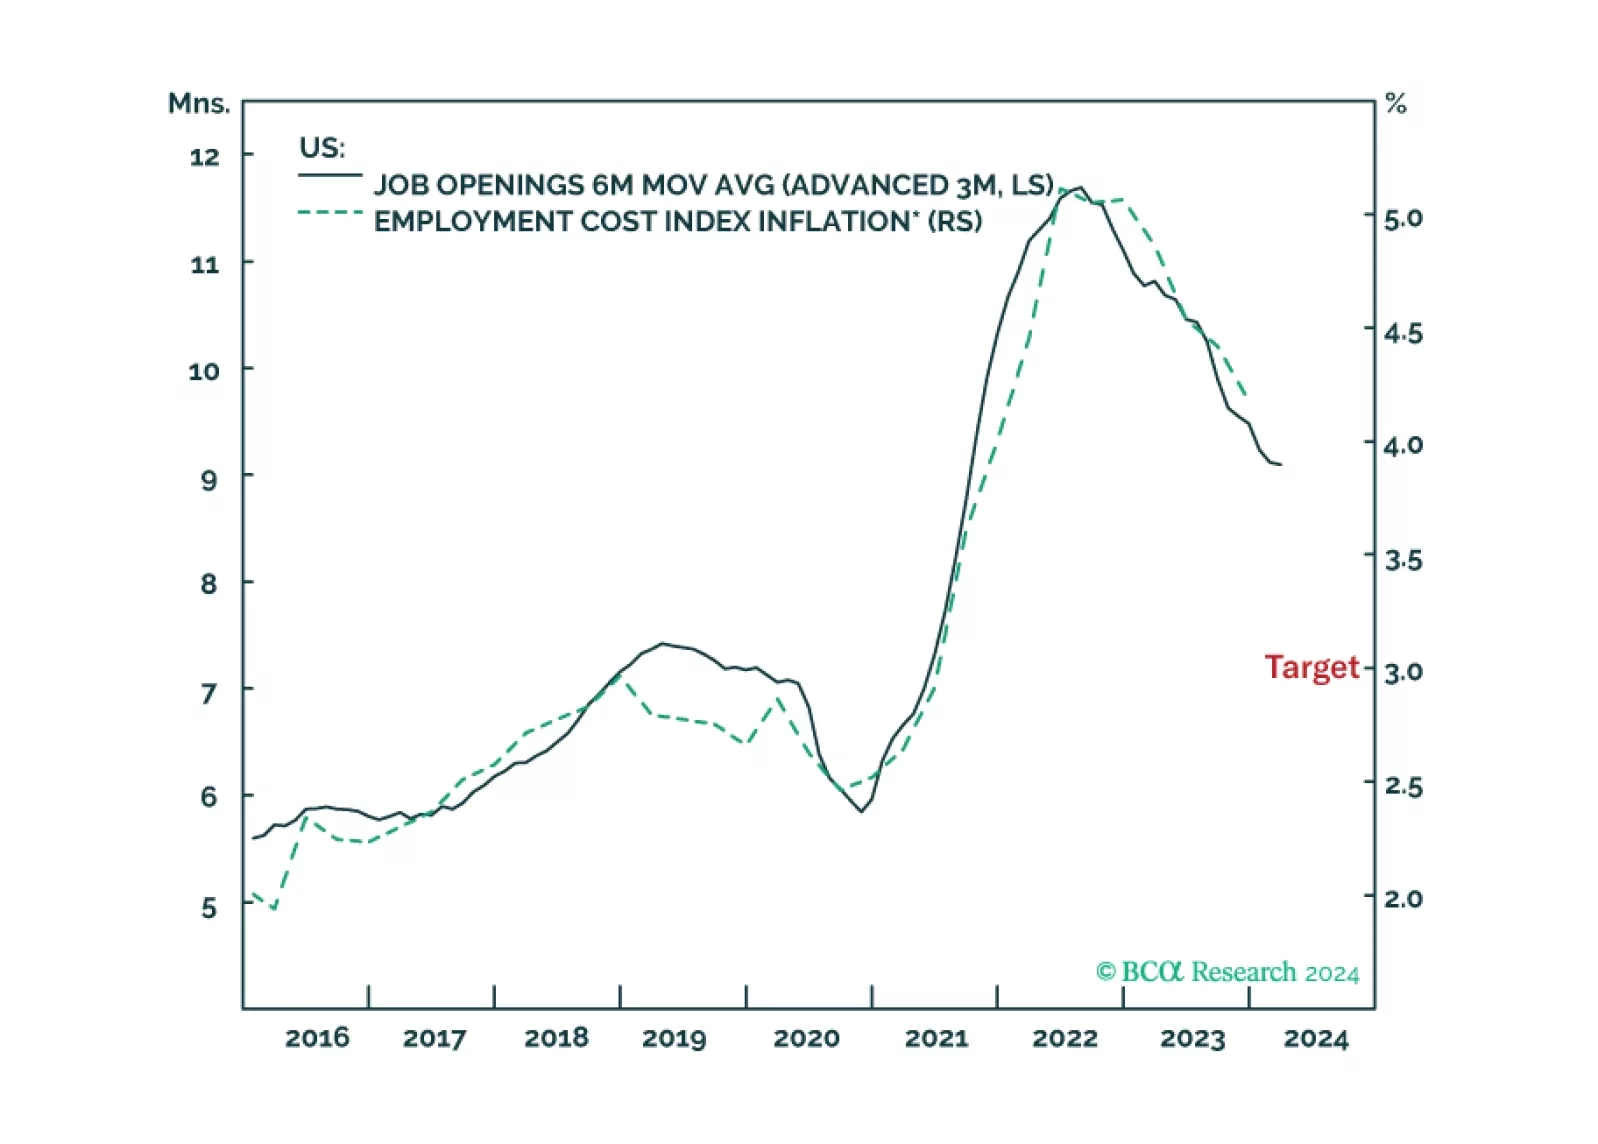
The disinflation to date has been benign because it has come almost entirely from improving supply. But the supply-side tailwind has exhausted, so the last mile of the journey to 2 percent inflation will be the hardest, especially in the US and the UK. We discuss the investment implications. Plus, we highlight an interesting sector pair-trade.
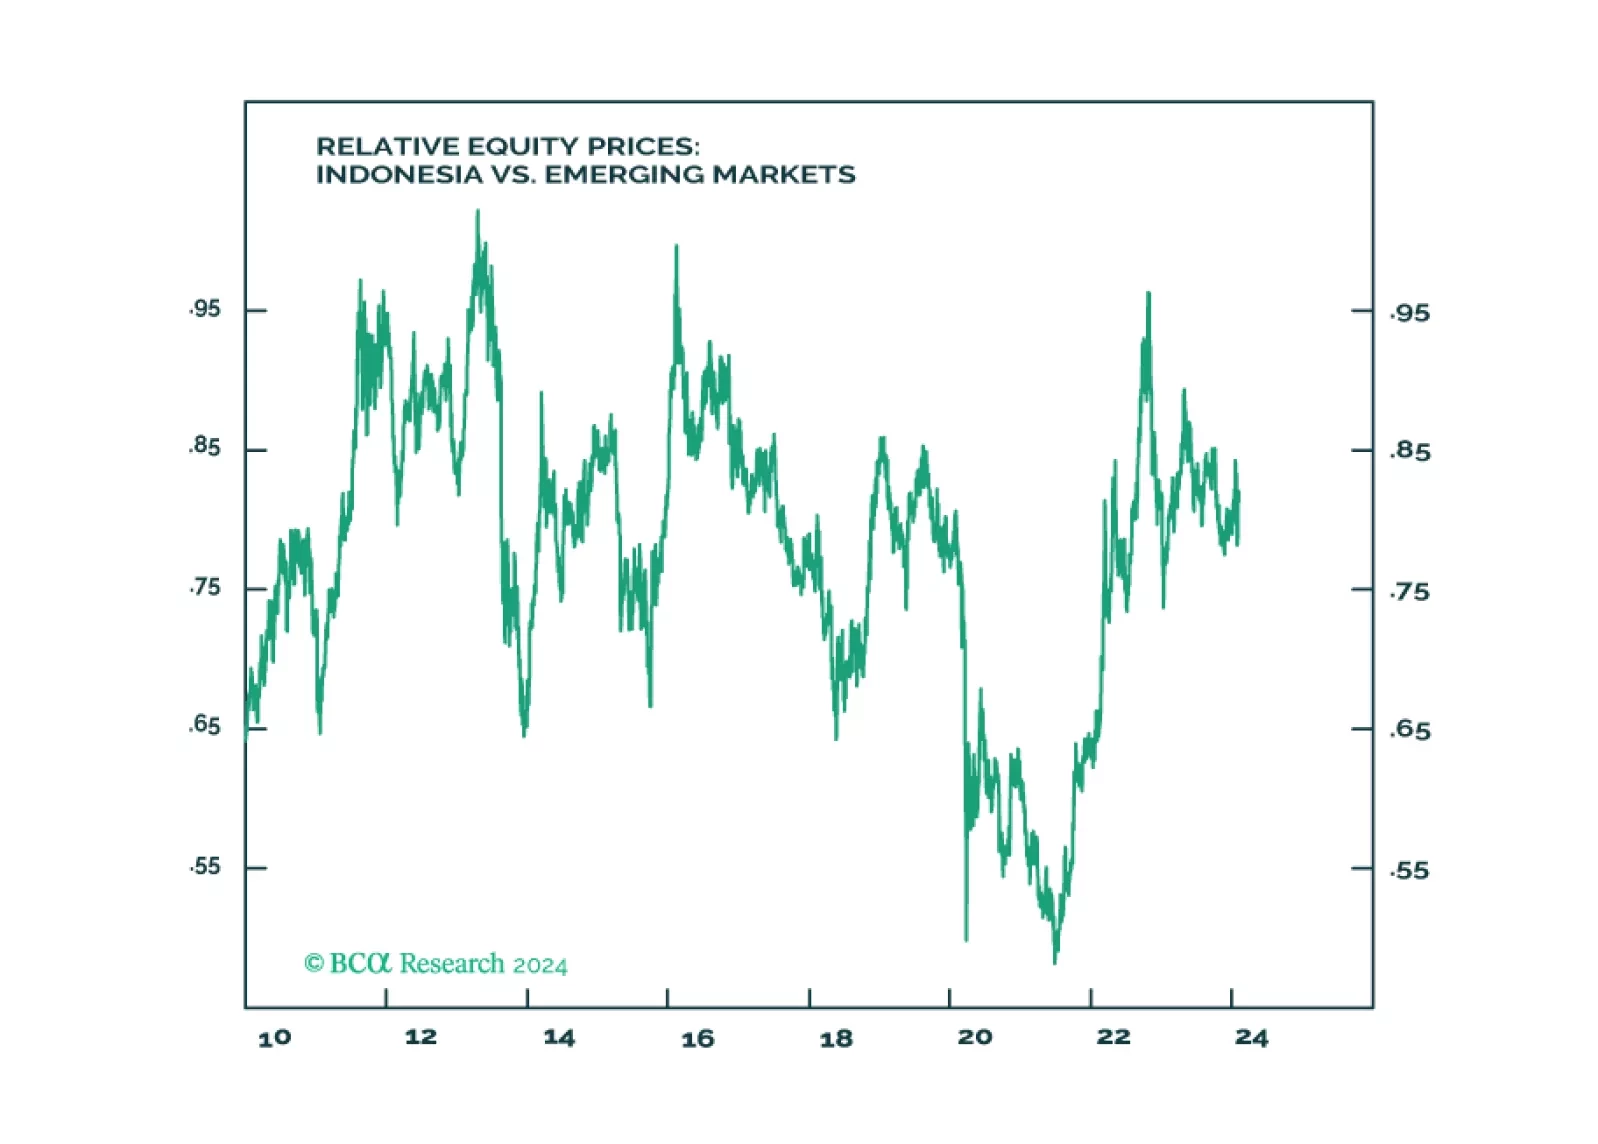
Indonesia will not revert to dictatorship. Yet the guardrails against authoritarianism are also constraining the actions of the next government in tackling near term domestic and regional challenges. For long-term positioning, use potential selloff from a “dictatorship scare” to build position as structural outlook for Indonesia is positive due to the China-West divorce and the global energy transition.
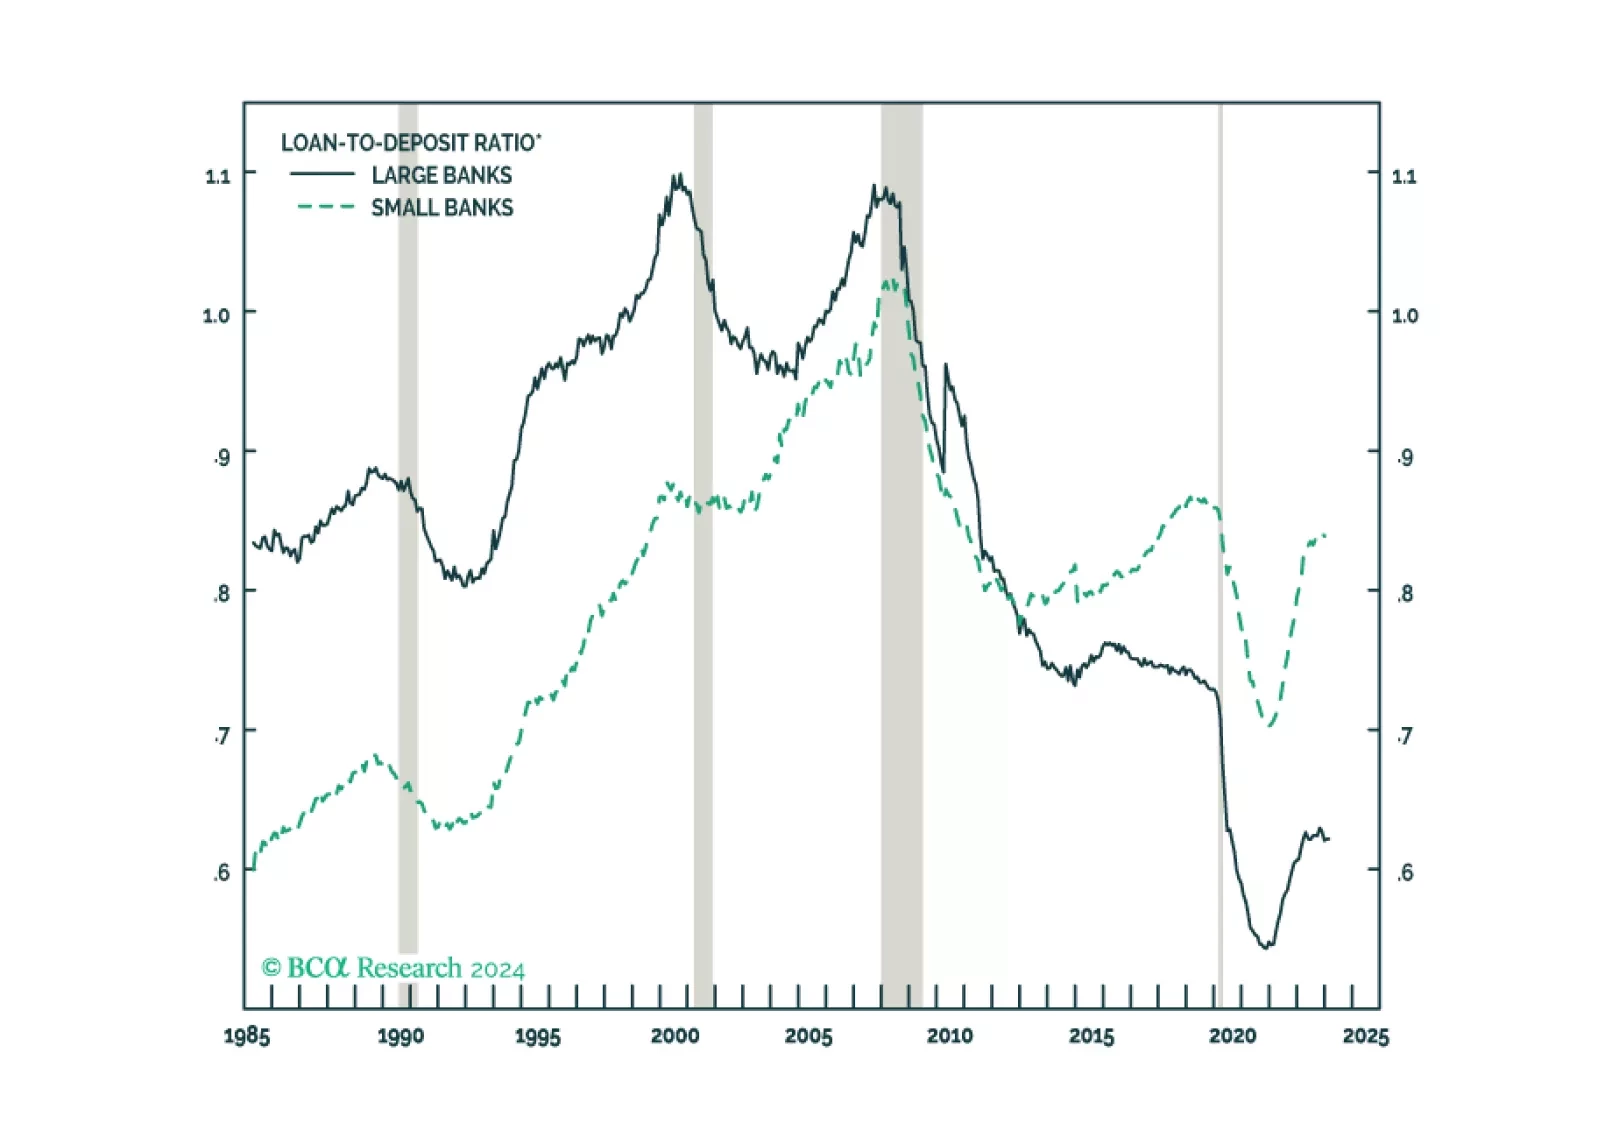
We do not believe that NYCB is a canary in the coal mine for a new round of bank distress. The MidCap 400 Regional Bank Index’s subsequent 10% decline looks to us like a juicy opportunity for stockpickers who can separate the wheat from the chaff. Our Special Report is meant to assist them with their initial winnowing.