
Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Inflation/Deflation

US CPI inflation for December came in slightly hotter than anticipated. Headline inflation accelerated from 0.1% to 0.3% on a month-over-month basis and rose from 3.1% to 3.4% on a year-over-year basis. Both the monthly and yearly changes in headline…
The best leading indicator for post-pandemic US wage inflation is the ratio of job vacancies to ‘bad’ unemployment (V/U), where bad unemployment refers to ‘job losers not on temporary layoff’. This ratio has already declined from 6.4 to 4.1 and wage…

We update our inflation forecast following this morning’s CPI report.
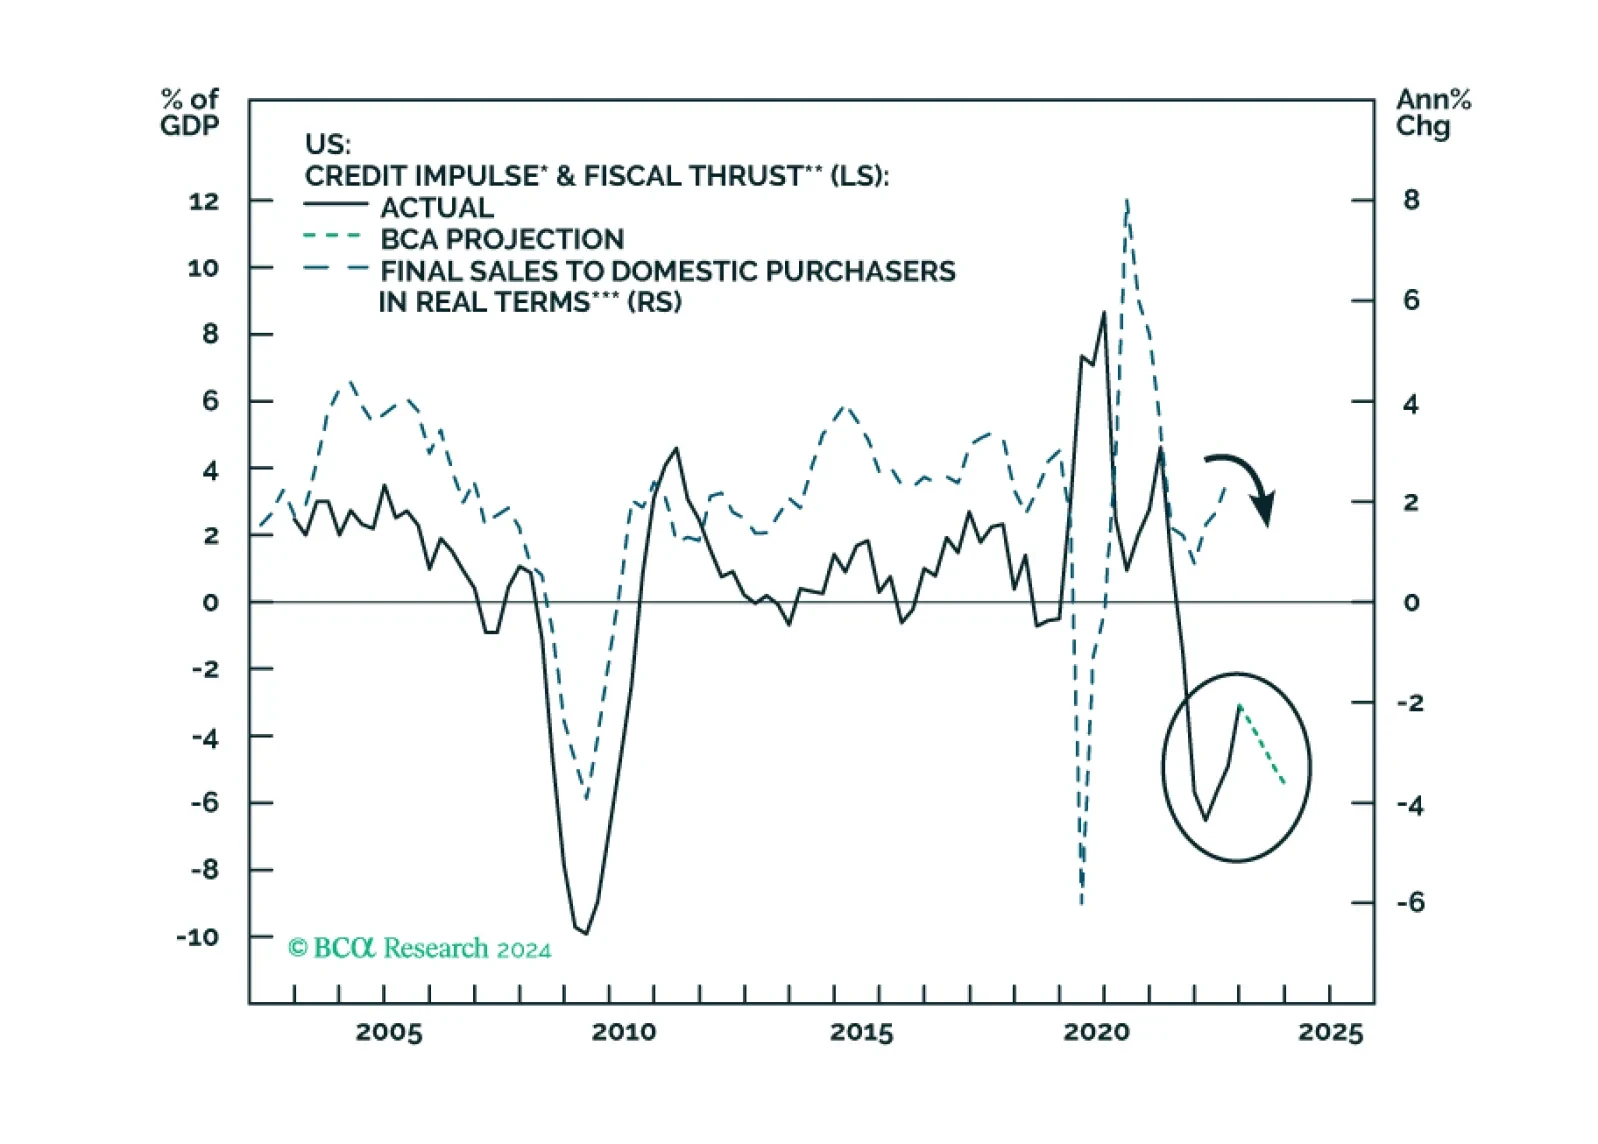
The combined US credit impulse and fiscal thrust indicator will likely relapse in 2024, heralding growth weakness. Stalling US sales volume and falling inflation, combined with sticky labor costs, will herald a non-trivial profit margin compression. The recent increase in Asian exports will likely prove to be a mid-cycle improvement rather than a cyclical recovery.
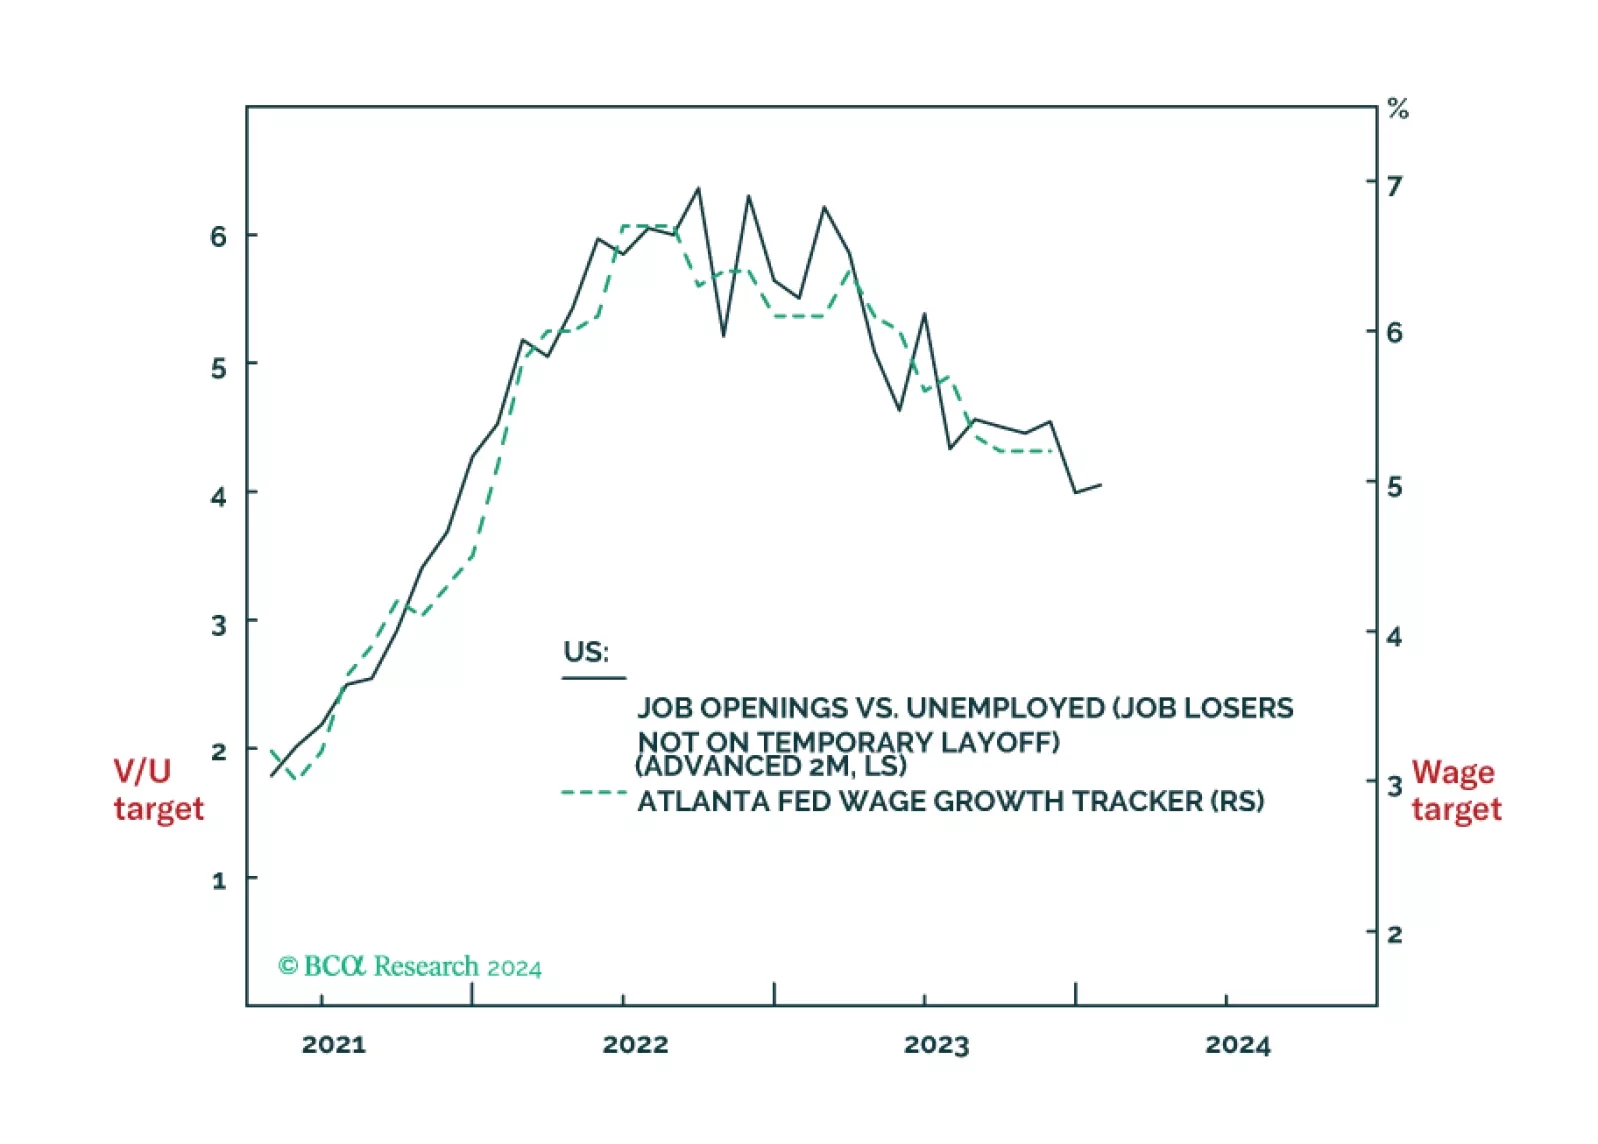
The Atlanta Fed’s US Wage Growth Tracker stalled at 5.2% in December, unchanged from November. Notably, after falling from a peak of 7.1% in June 2022, this indicator has stabilized at still-elevated levels in recent months. This dynamic raises the question…
Australian CPI inflation fell from 4.9% y/y to a 22-month low of 4.3% y/y in November – slightly below expectations of 4.4%. Underlying measures of core inflation also indicate that price pressures eased in November. The rate of growth in CPI excluding…

The Fed faces a dilemma. Cut rates early to avoid a recession, but at the risk of not slaying wage inflation. Or, not cut rates early to ensure that wage inflation is slayed, but at the risk of a downturn. Faced with such a dilemma, the lesser evil is to slay wage inflation even at the risk of a downturn. Meaning that the market has overpriced early rate cuts. We discuss some other investment implications, and identify two rebound candidates.
The NFIB Small Business Optimism Index delivered a slight positive surprise on Tuesday. The index rose 1.3 points to a five-month high of 91.9 in December and beat consensus expectations of 91.0. However, the contents of the report were more mixed. On the…
BCA Research’s US Bond Strategy service recommends investors keep portfolio duration close to benchmark for now. They will increase rate exposure as the labor market downturn worsens. Treasury yields are up slightly to start the year, but last Friday’s…

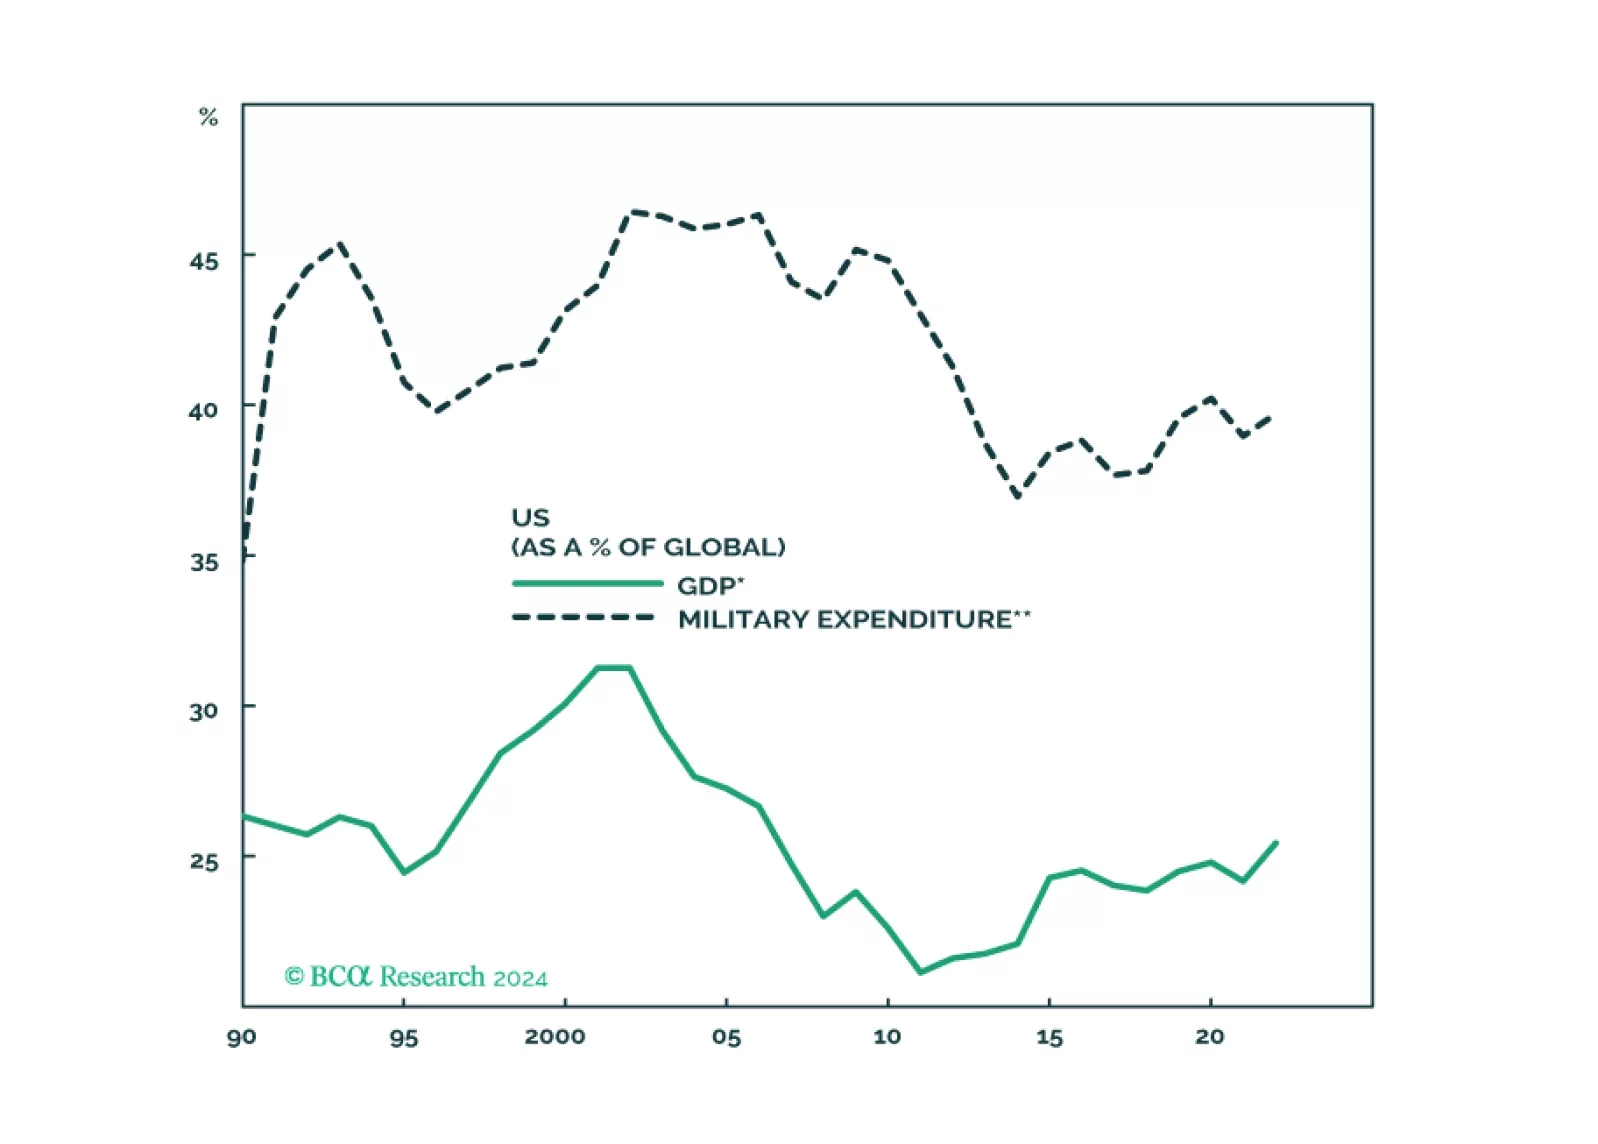
The market’s pricing of a soft landing means that geopolitical risks are becoming more, not less, relevant in 2024. US domestic divisions will invite challenges as foreign powers rightly fear that US policy will turn more hawkish after the election.