Natural Gas

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.
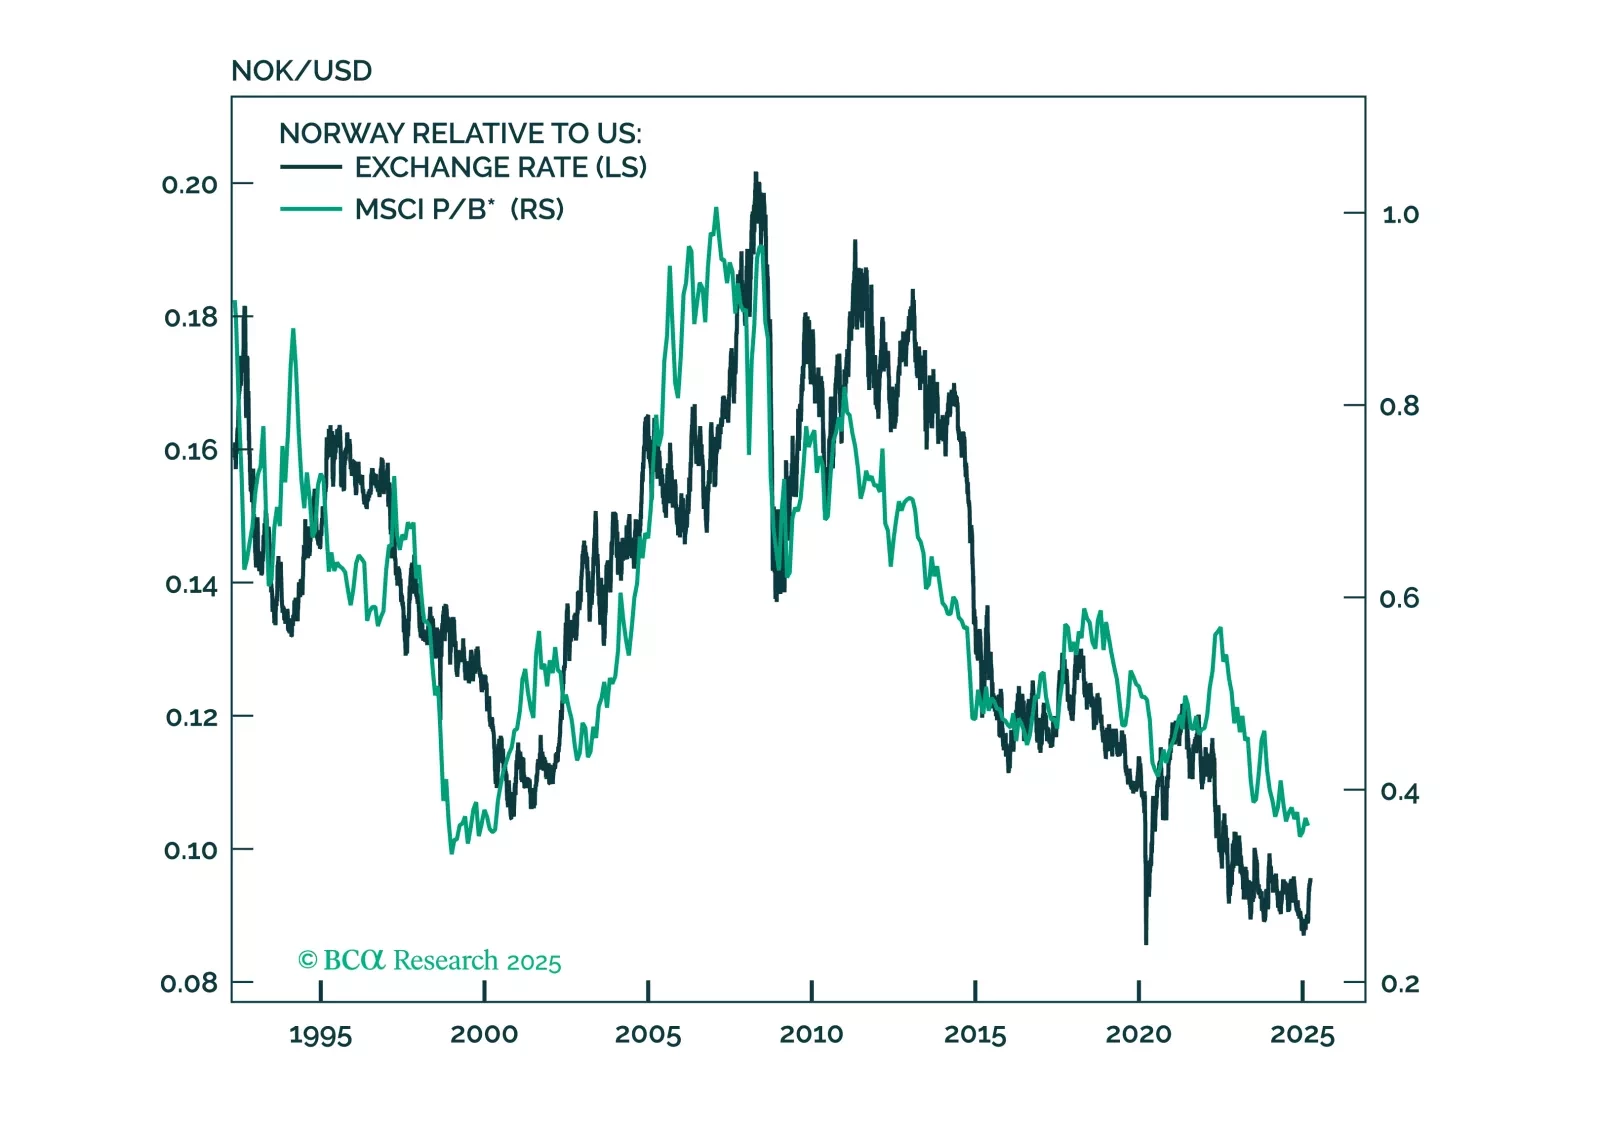
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.
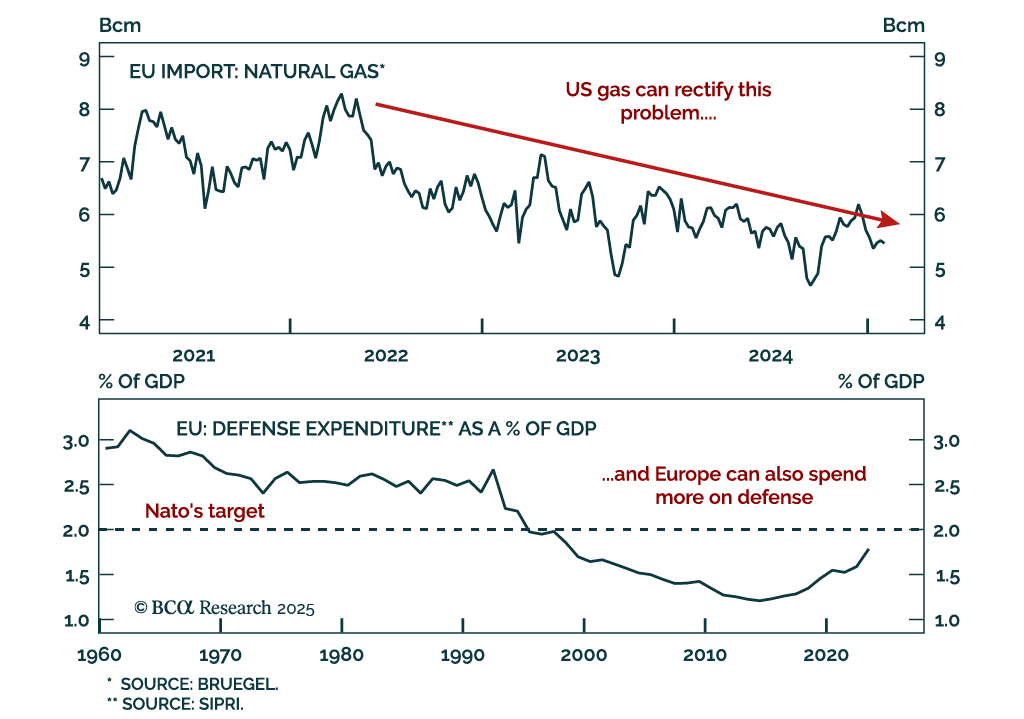
Europe is about to become President Trump’s next target. The good news: a US/EU trade war will be short as common ground to achieve a deal exists. The bad news: European assets remain at the mercy of heightened uncertainty. How should investors position themselves in this tricky context?

A confluence of both supply and demand factors contributed to the natural gas rally over the past few months. This trend could continue for a while longer. However, cyclical and structural factors ultimately argue against a sustained increase in prices.
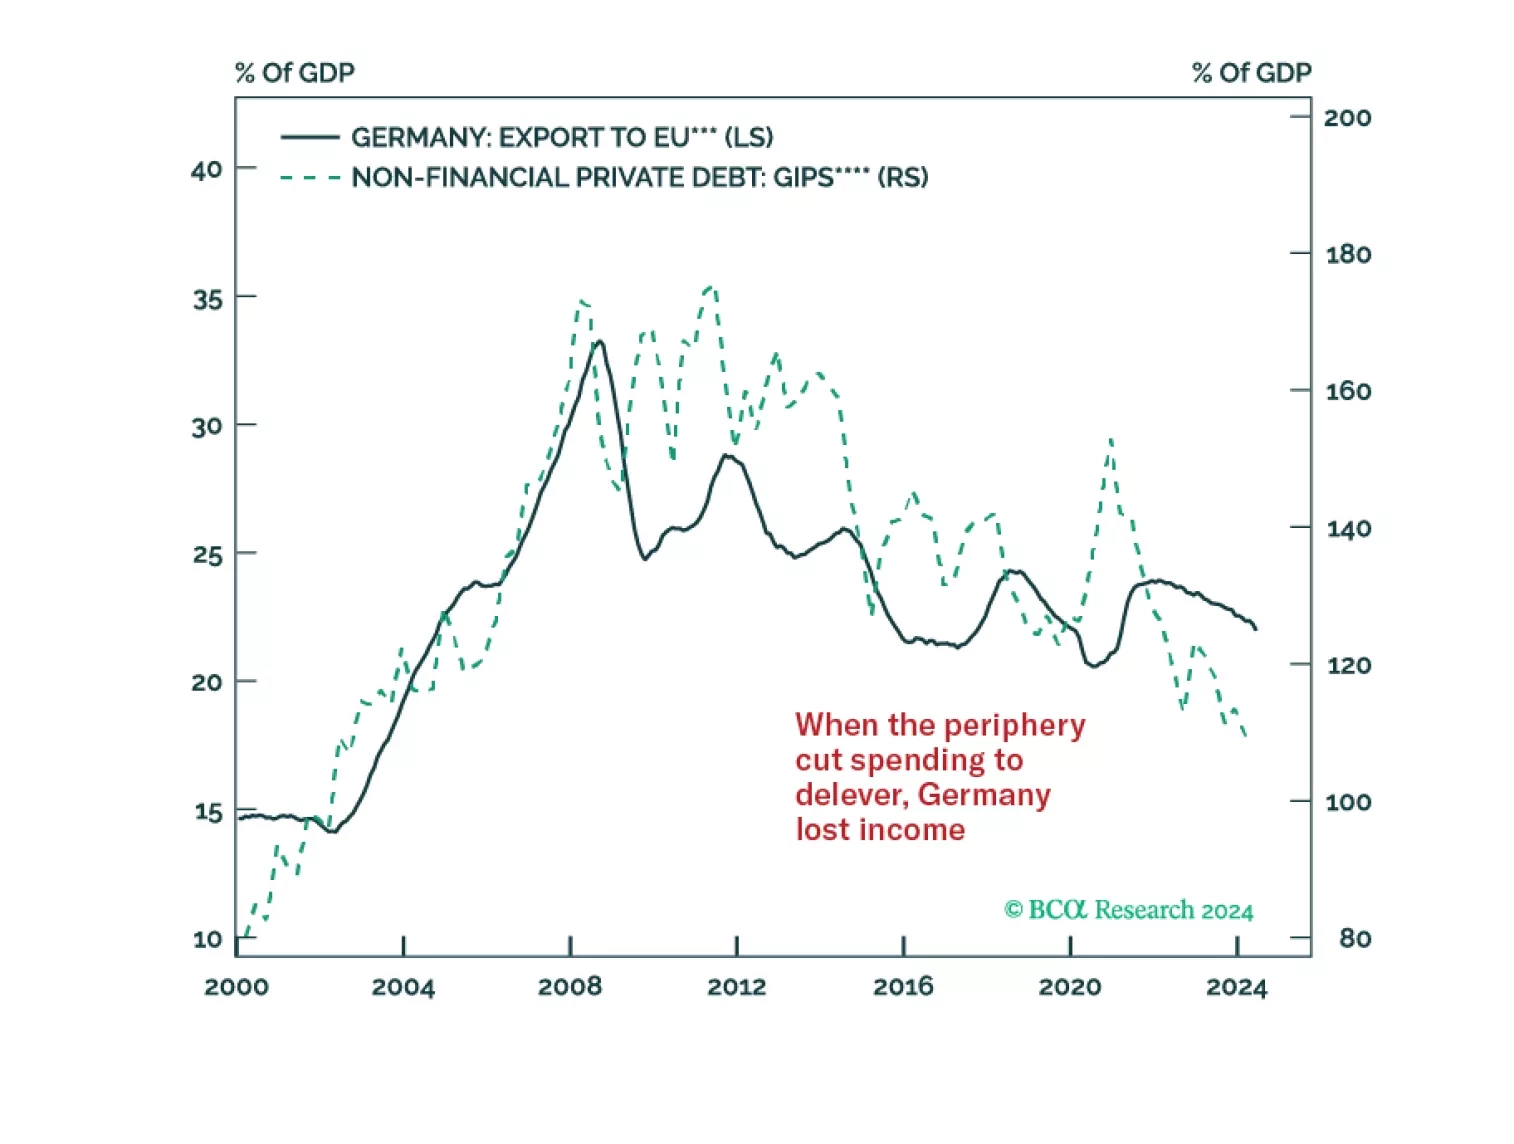
Germany’s economy has lagged that of the rest of Europe for nearly 10 years. So have German stocks. Investors are extrapolating these trends to bet on the country’s deindustrialization. Could Germany manage to beat dismal expectations?
The global political system is destabilizing and the US will turn more hawkish in foreign policy, trade policy, or both, regardless of the election outcome. Tactically go long the dollar.

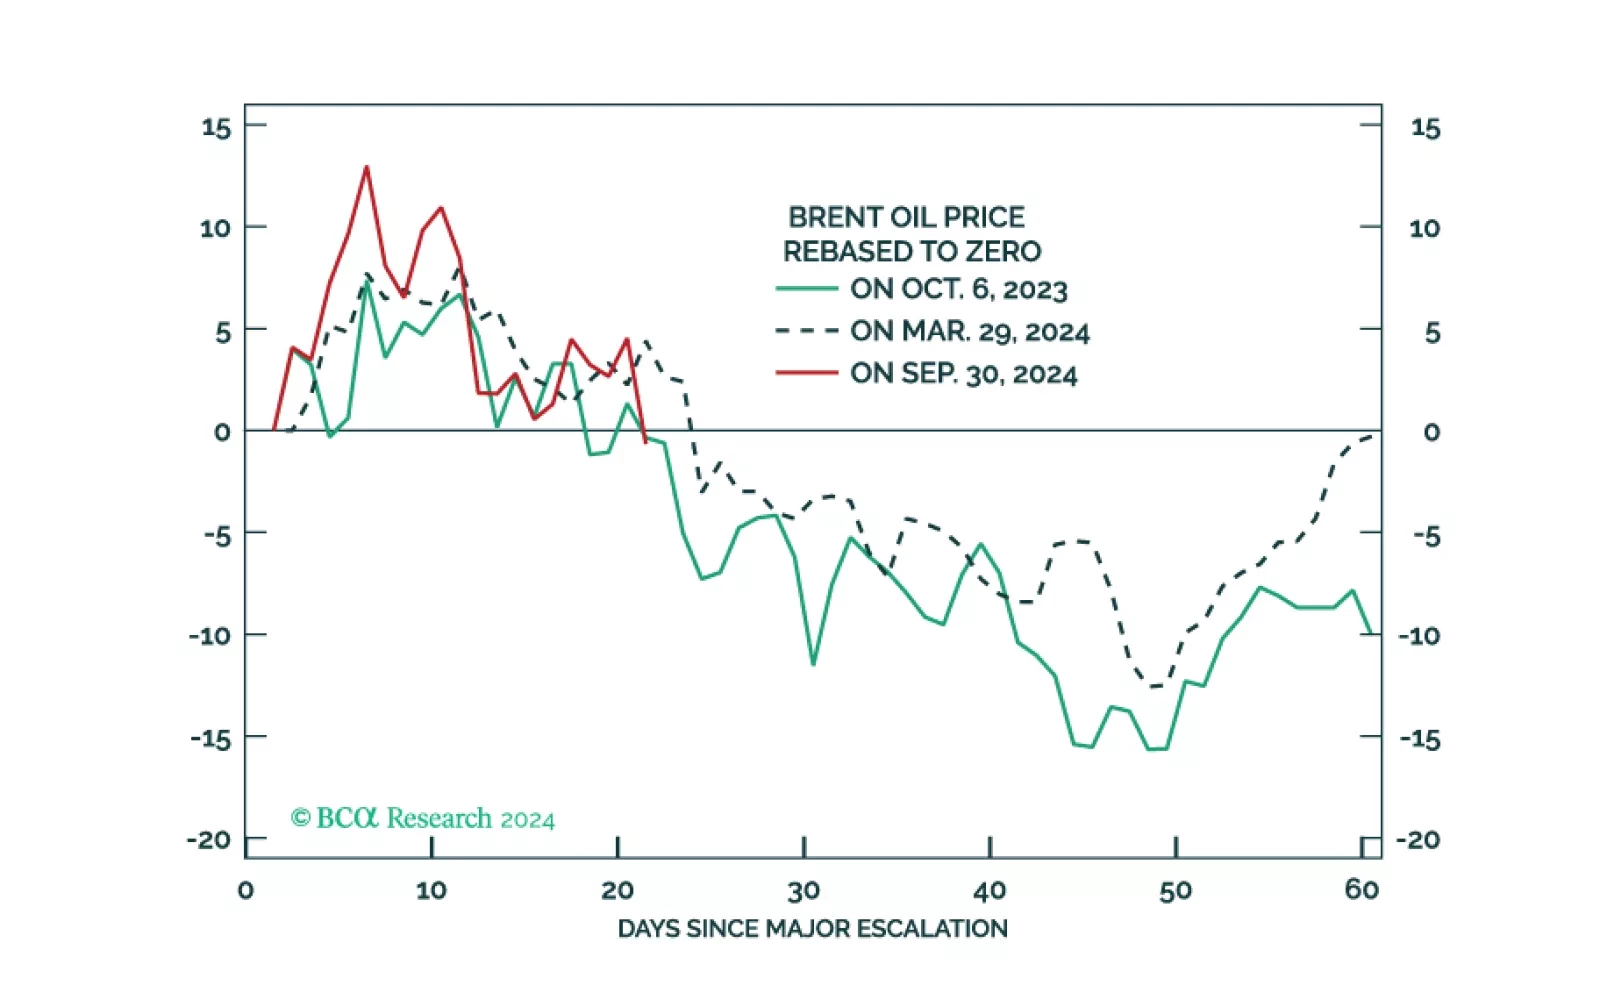
Markets are rallying on Fed rate cuts and China stimulus but there will also be October surprises ahead of the US election, which Trump could still win. Russia’s conflict with the West is escalating and the Middle East is destabilizing further. Investors should favor US bonds but they should add some risk in emerging markets in response to China’s policy turn.
