Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Commodities & Energy Sector

In a trendless yet volatile year for oil, Israel’s retaliatory attack on Iran this weekend is a reminder the outlook is fraught with geopolitical risks. Risks are usually expressed as a geopolitical price premium, but this weekend’s events point to a…

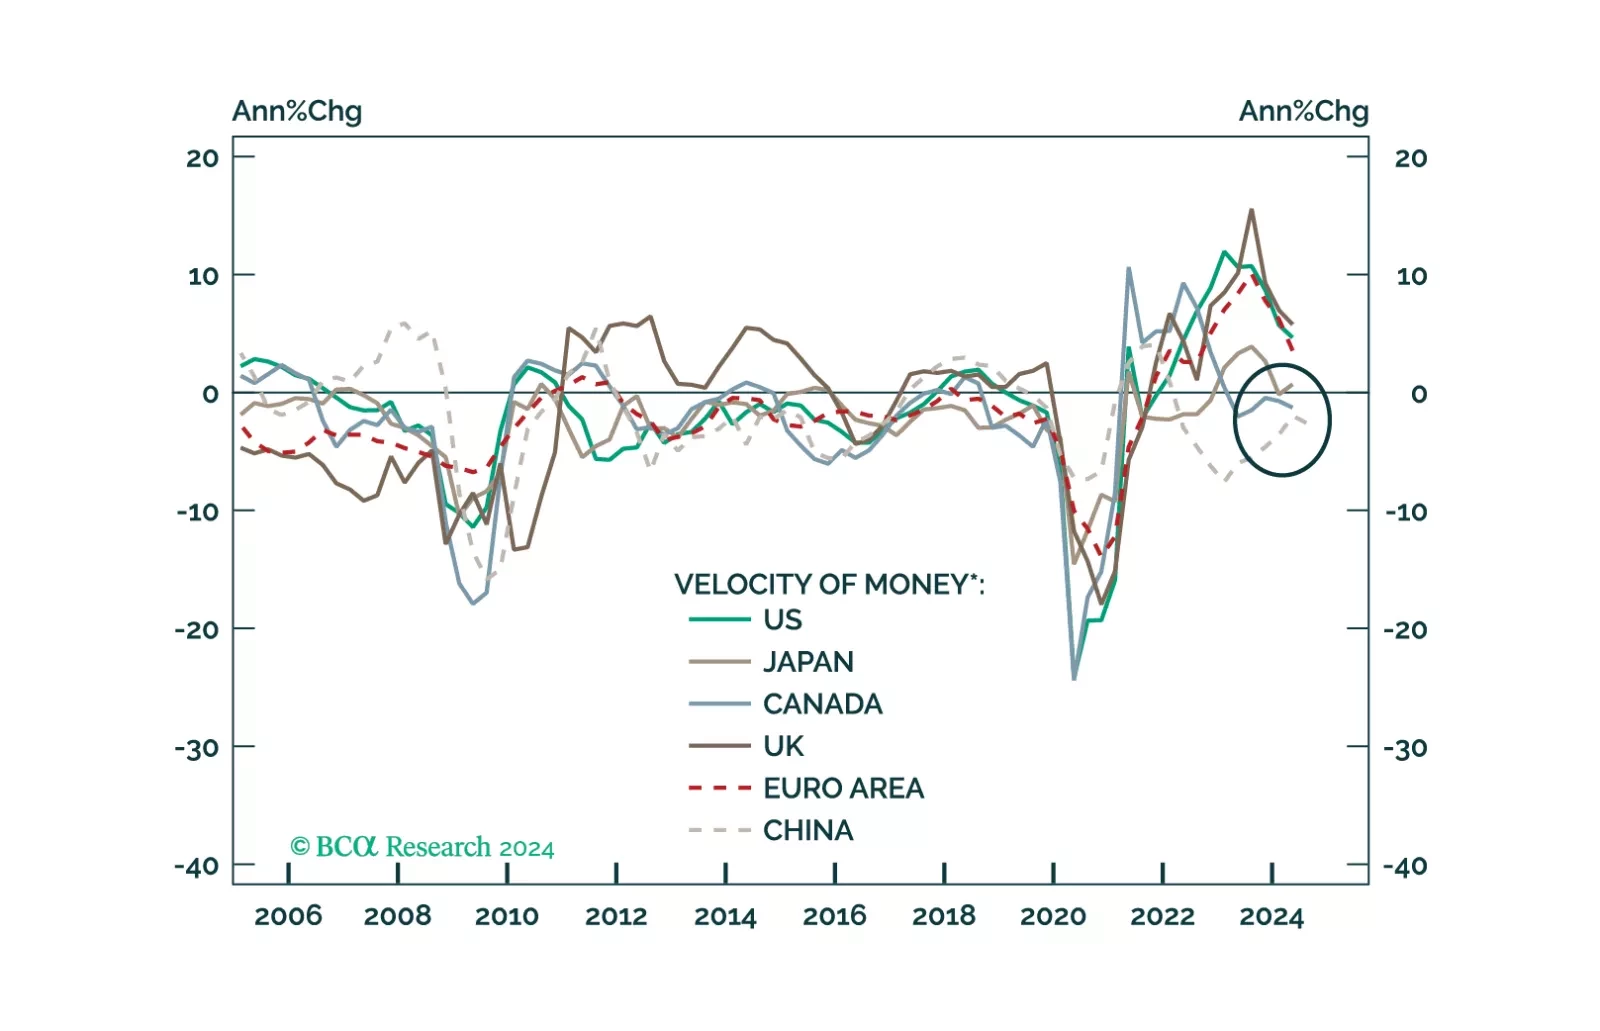
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
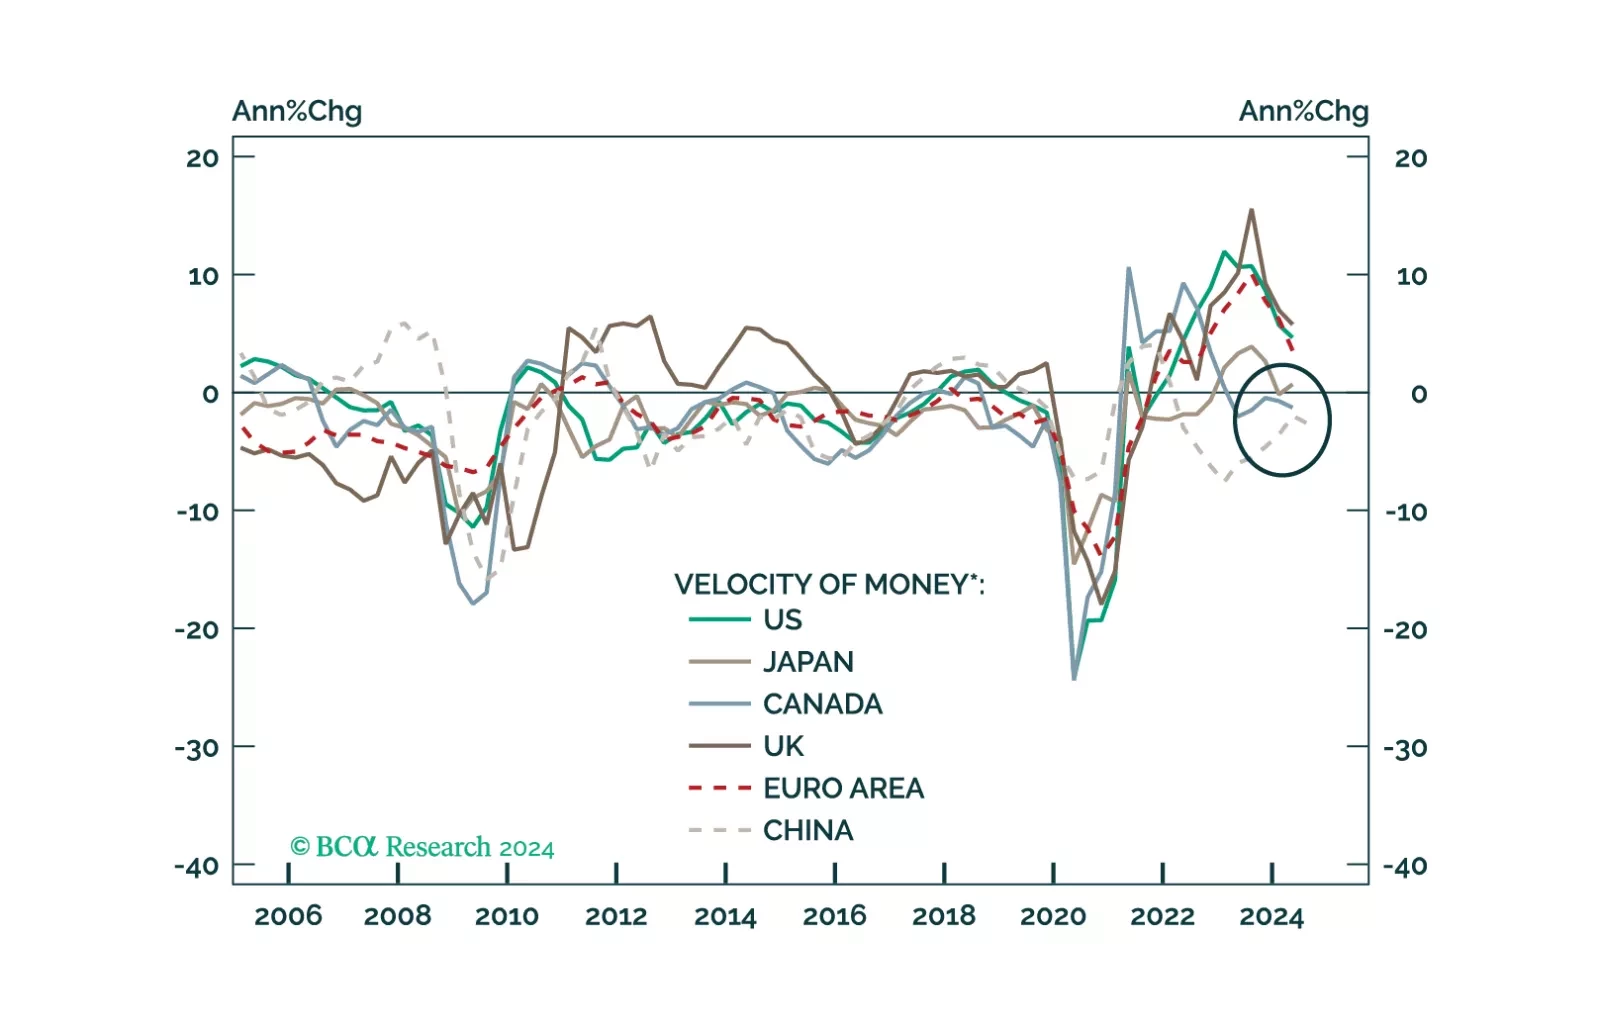
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.

Crude prices have been trendless but volatile in 2024. Oil’s choppy price action illustrates the demand and supply tug-o-war in the market. Our bias is for crude prices to weaken on a six-to-nine months horizon. Good economic news such as the resilience of…
Special Report

In this Special Report, Marko Papic, Chief Strategist of BCA Research’s GeoMacro Strategy, and Mathieu Savary, Chief Strategist of BCA Research’s European Investment Strategy, together argue that the conflict in Ukraine is already frozen, already losing support in the West, and is likely to taper off over the course of 2025. However, there is no easy alpha left to harvest from that conclusion, the market has already moved on. Some long-term investment opportunities remain in broad European assets.

While recent cross-asset developments have sent a risk-on signal, with equities and bond yields both higher, the commodity complex has recently been sending a more somber message. “Dr. Copper” is a bellwether for the global economy given its industrial…

We maintain 37% odds of a major recessionary oil shock, 51% odds of minor shocks, and 12% odds of no shocks.

Regular readers are familiar with our expectations for a global recession over the cyclical investment timeframe. A global downturn is overwhelmingly bearish for oil demand. The supply side, on the other hand, is simultaneously facing the threat of supply…
In the fifth installment of a BCA Special Report series on nuclear energy, our colleagues argue that US nuclear energy dominance is decaying. Though still the world’s leader in generation and capacity, the US will not hold the mantle indefinitely given high…

Western policymakers are pursuing three capital “T” Truths: China is evil, climate change is a major risk, and Russia is… also evil. Pursuing all three priorities at the same time presents a version of the classic “impossible trinity.”