
Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Emerging Markets

Since the pursuit of a nuclear deterrent makes it inevitable that the US and Israel will oppose Iran in the coming years, Iran must seize the initiative today. It cannot afford to assume that the Democratic Party will stay in power and continue to pursue…
Special Report

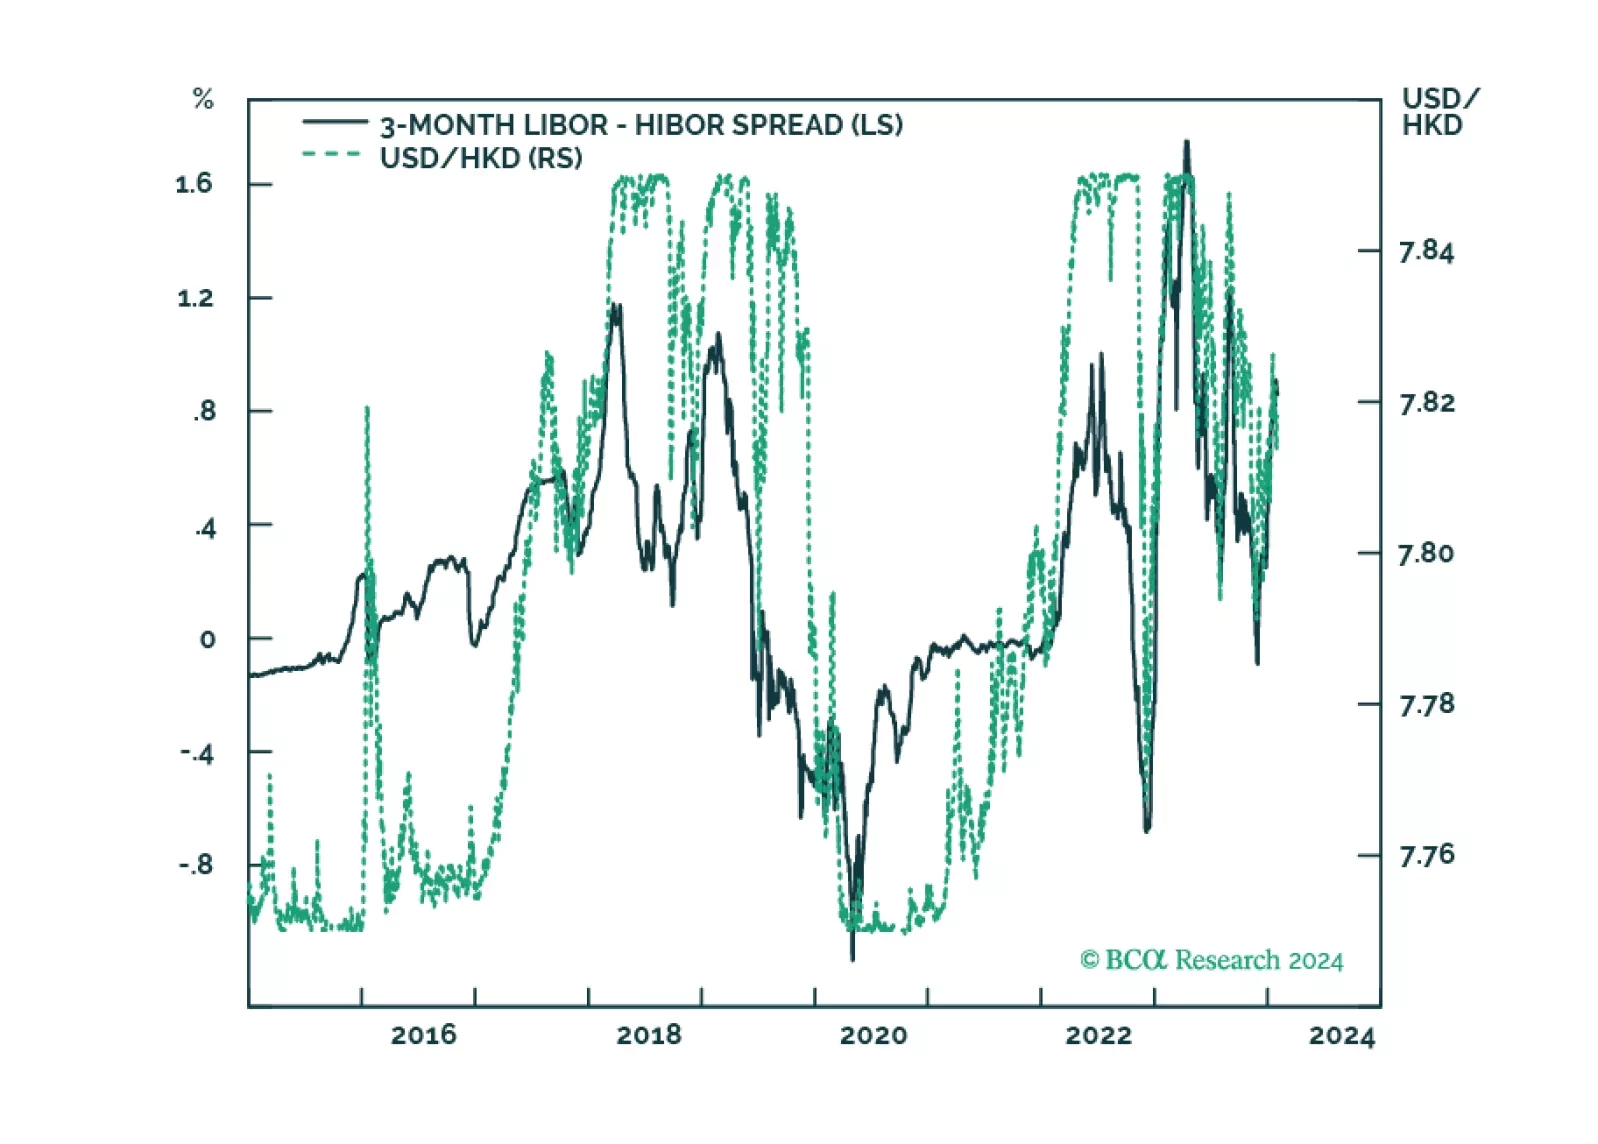
In this Special Report, we update our thinking on the Hong Kong SAR dollar peg, with implications for domestic asset markets.
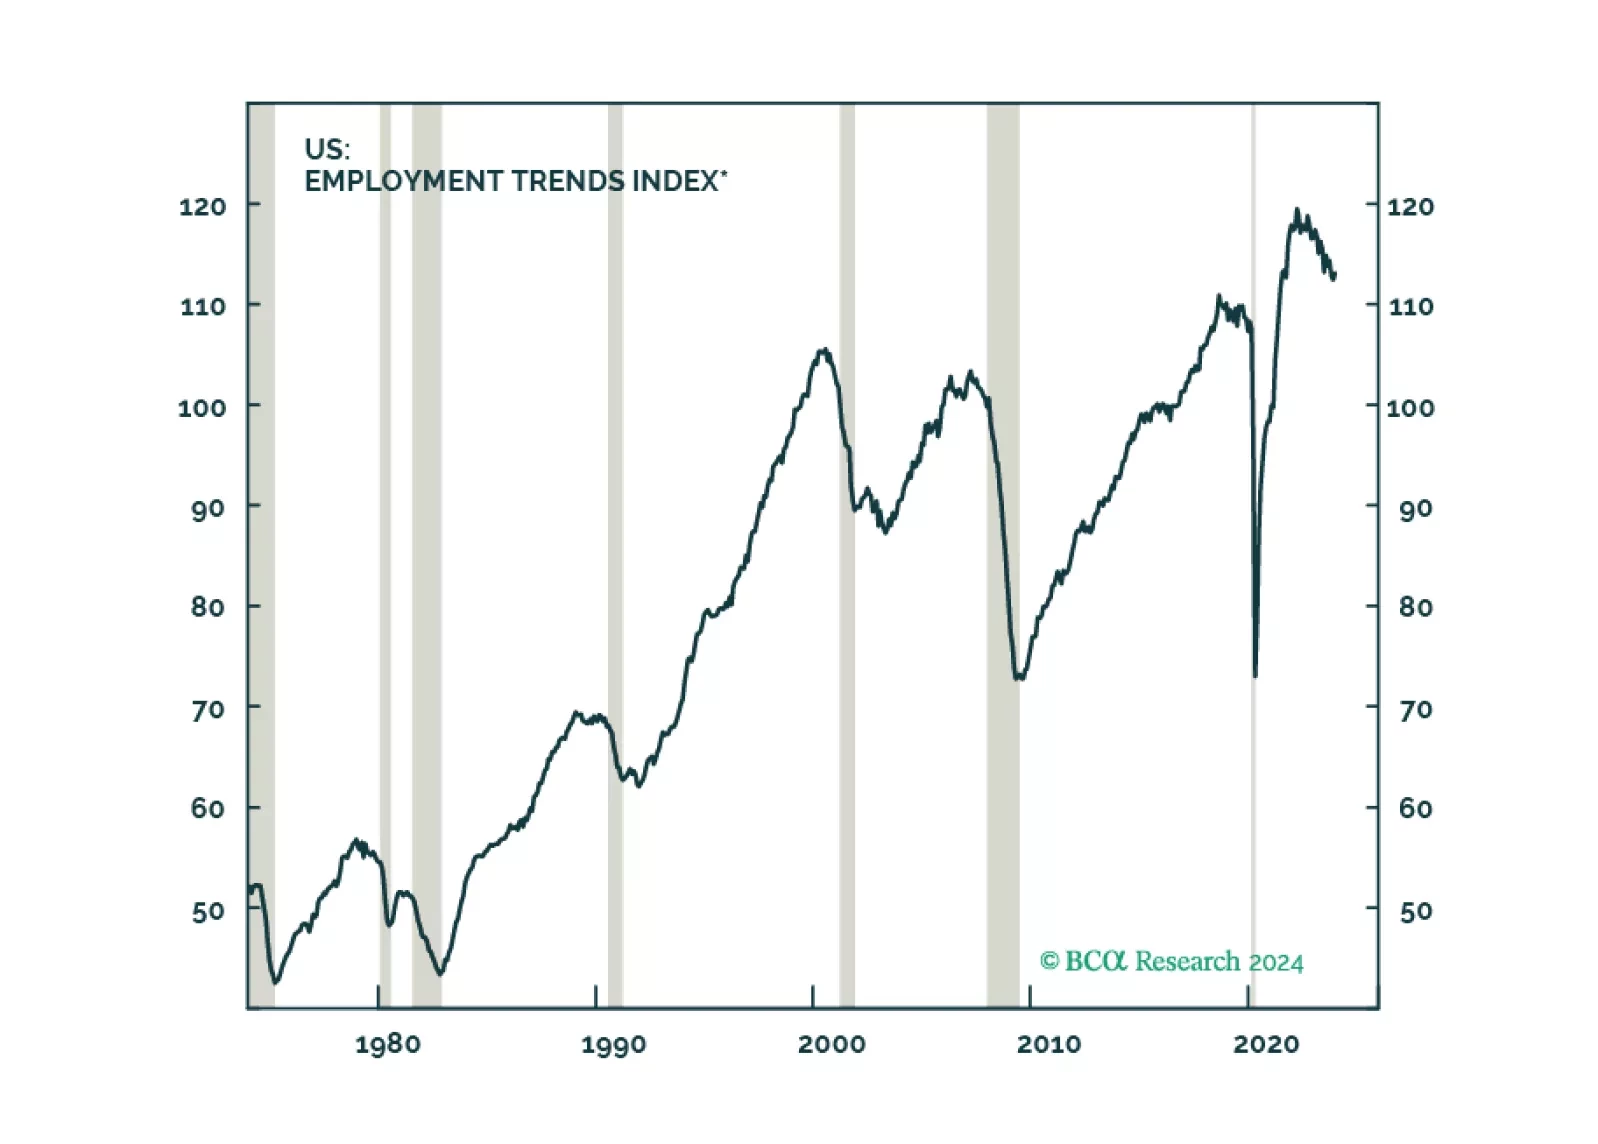
When will the US also buckle under high rates? We expect a US recession to begin around mid-year. Stay defensive.
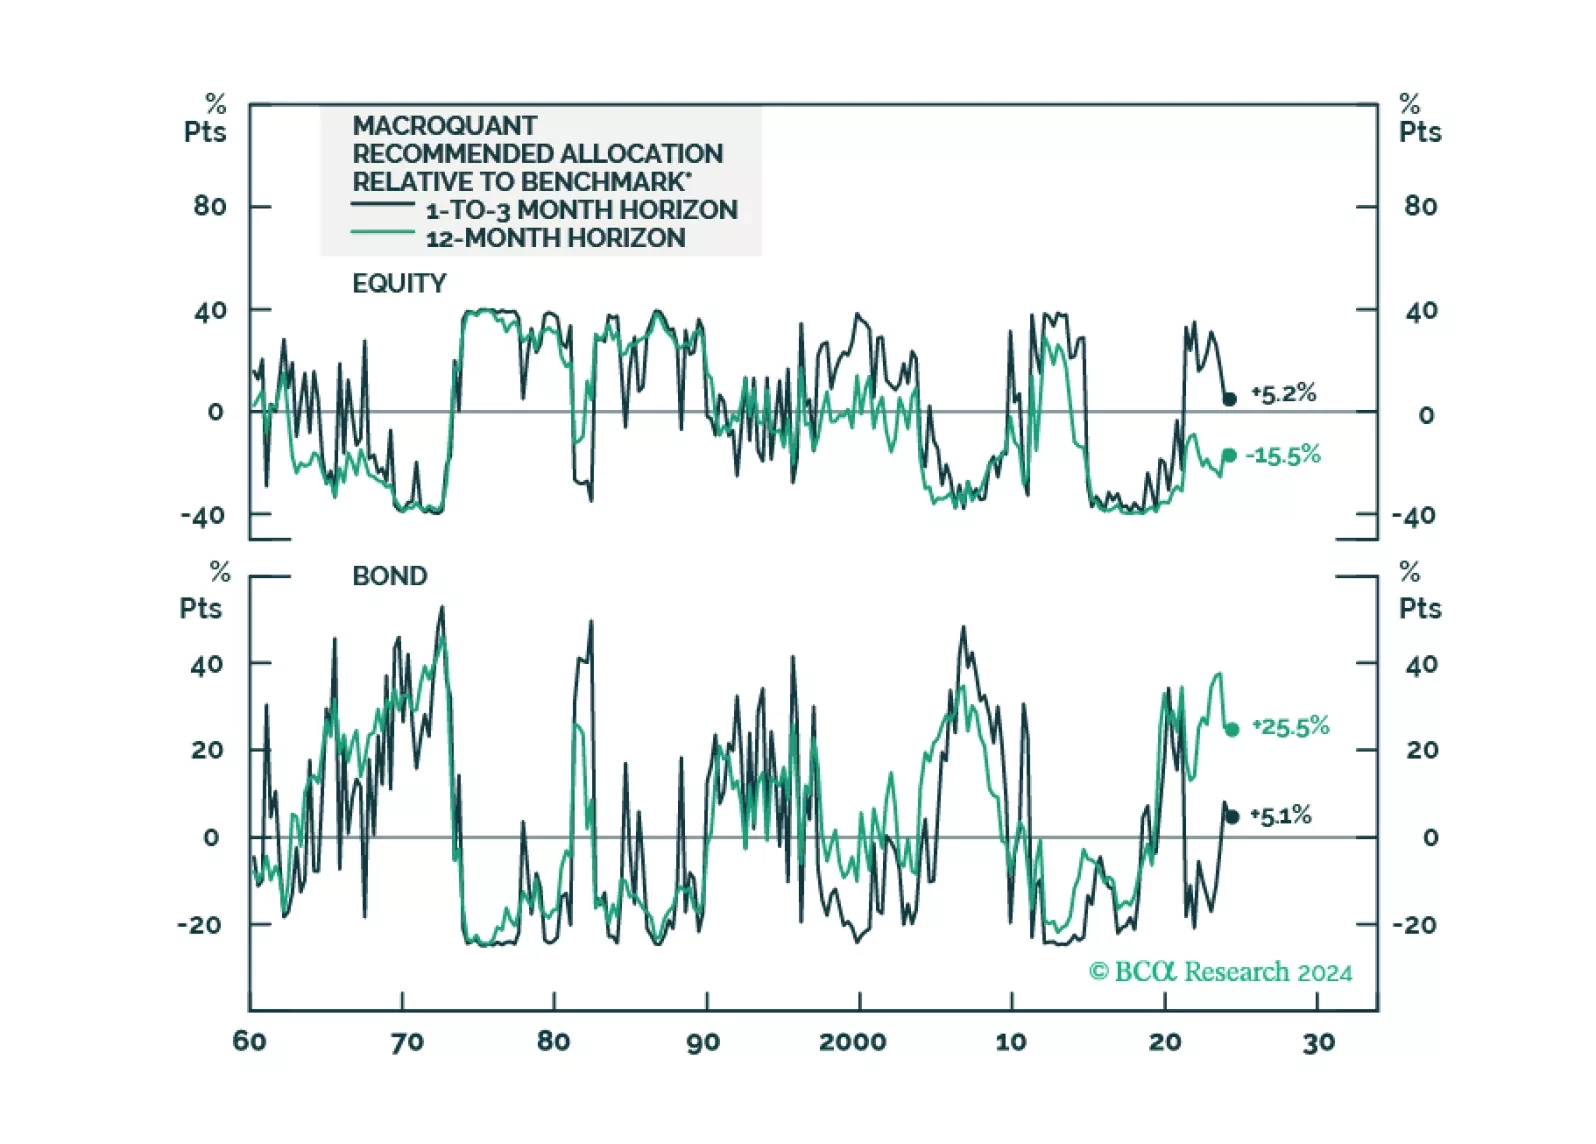
Following the release of the white paper yesterday, today we are sending you the inaugural issue of the MacroQuant Monthly, a report summarizing the output of our next-generation MacroQuant 2.0 model.
China’s official NBS PMI indicates that growth conditions remain sluggish. Although the composite index ticked up from 50.3 to 50.9, it is still barely in expansionary territory. Notably, the manufacturing PMI – which inched up by 0.2 points in January –…
China’s industrial profits registered their second consecutive annual contraction last year, falling by 2.3% in 2023. The full year contraction comes despite a surge in industrial profits near year-end. Profit growth came in at 16.8% y/y in December…
Special Report

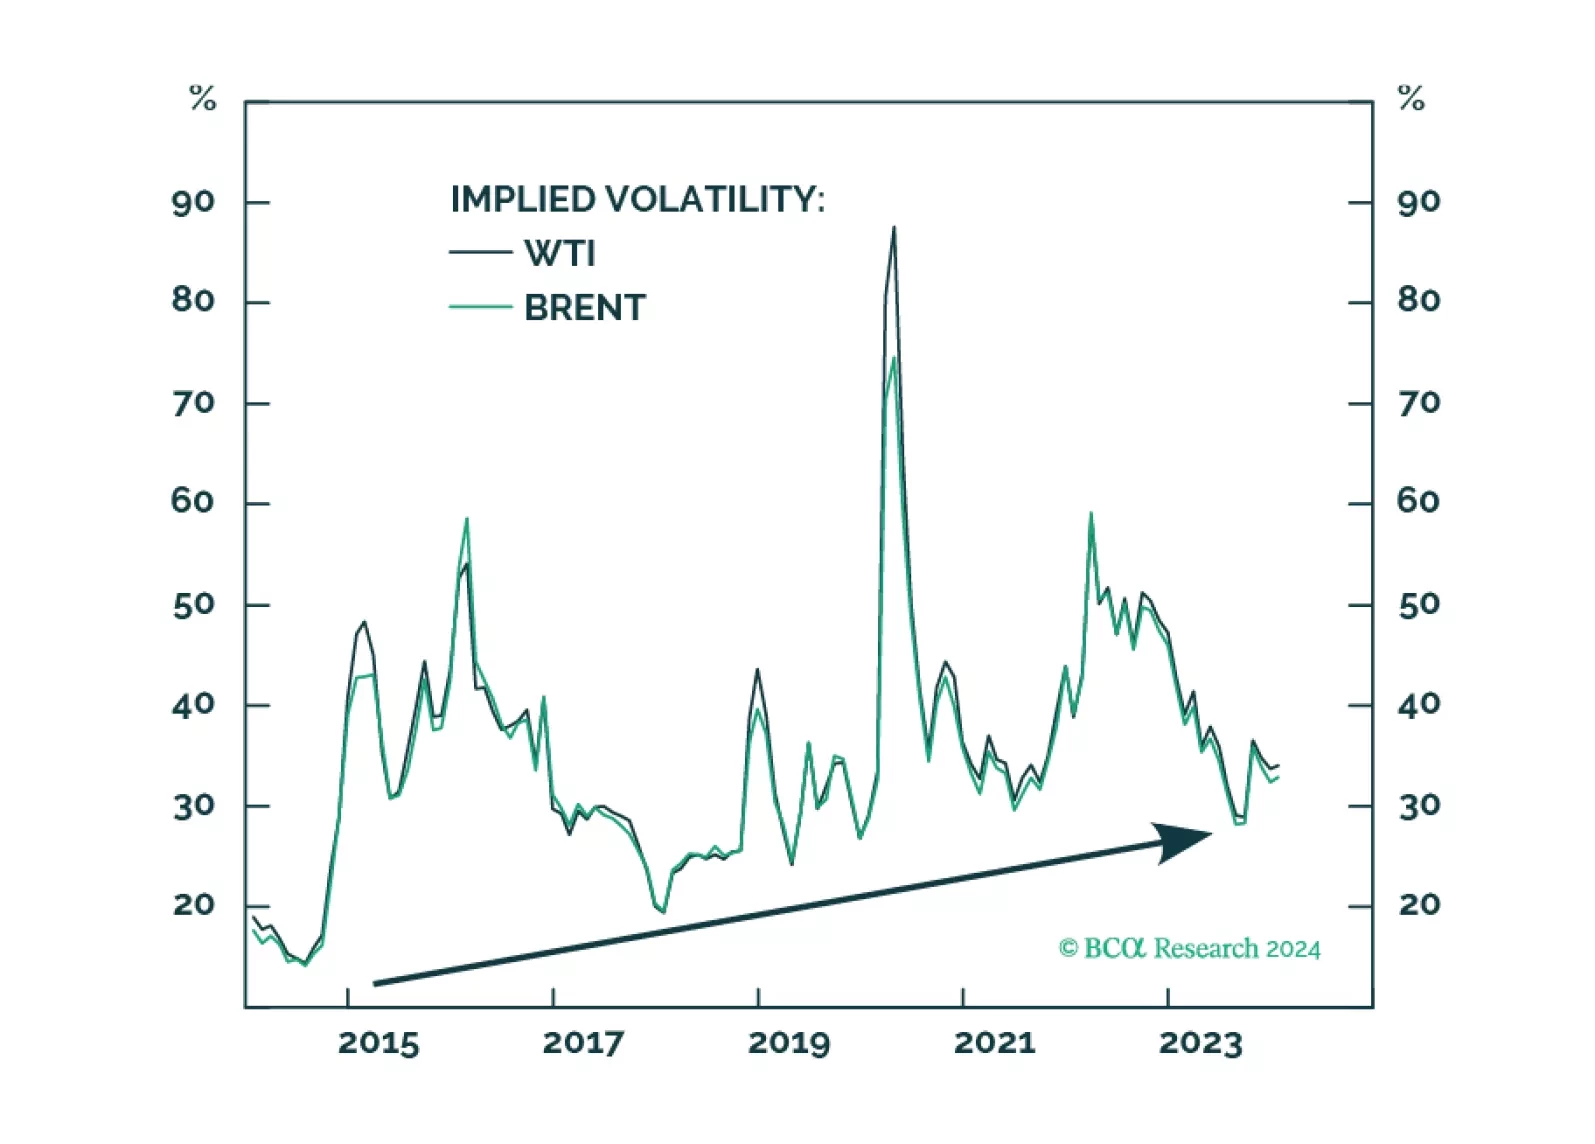
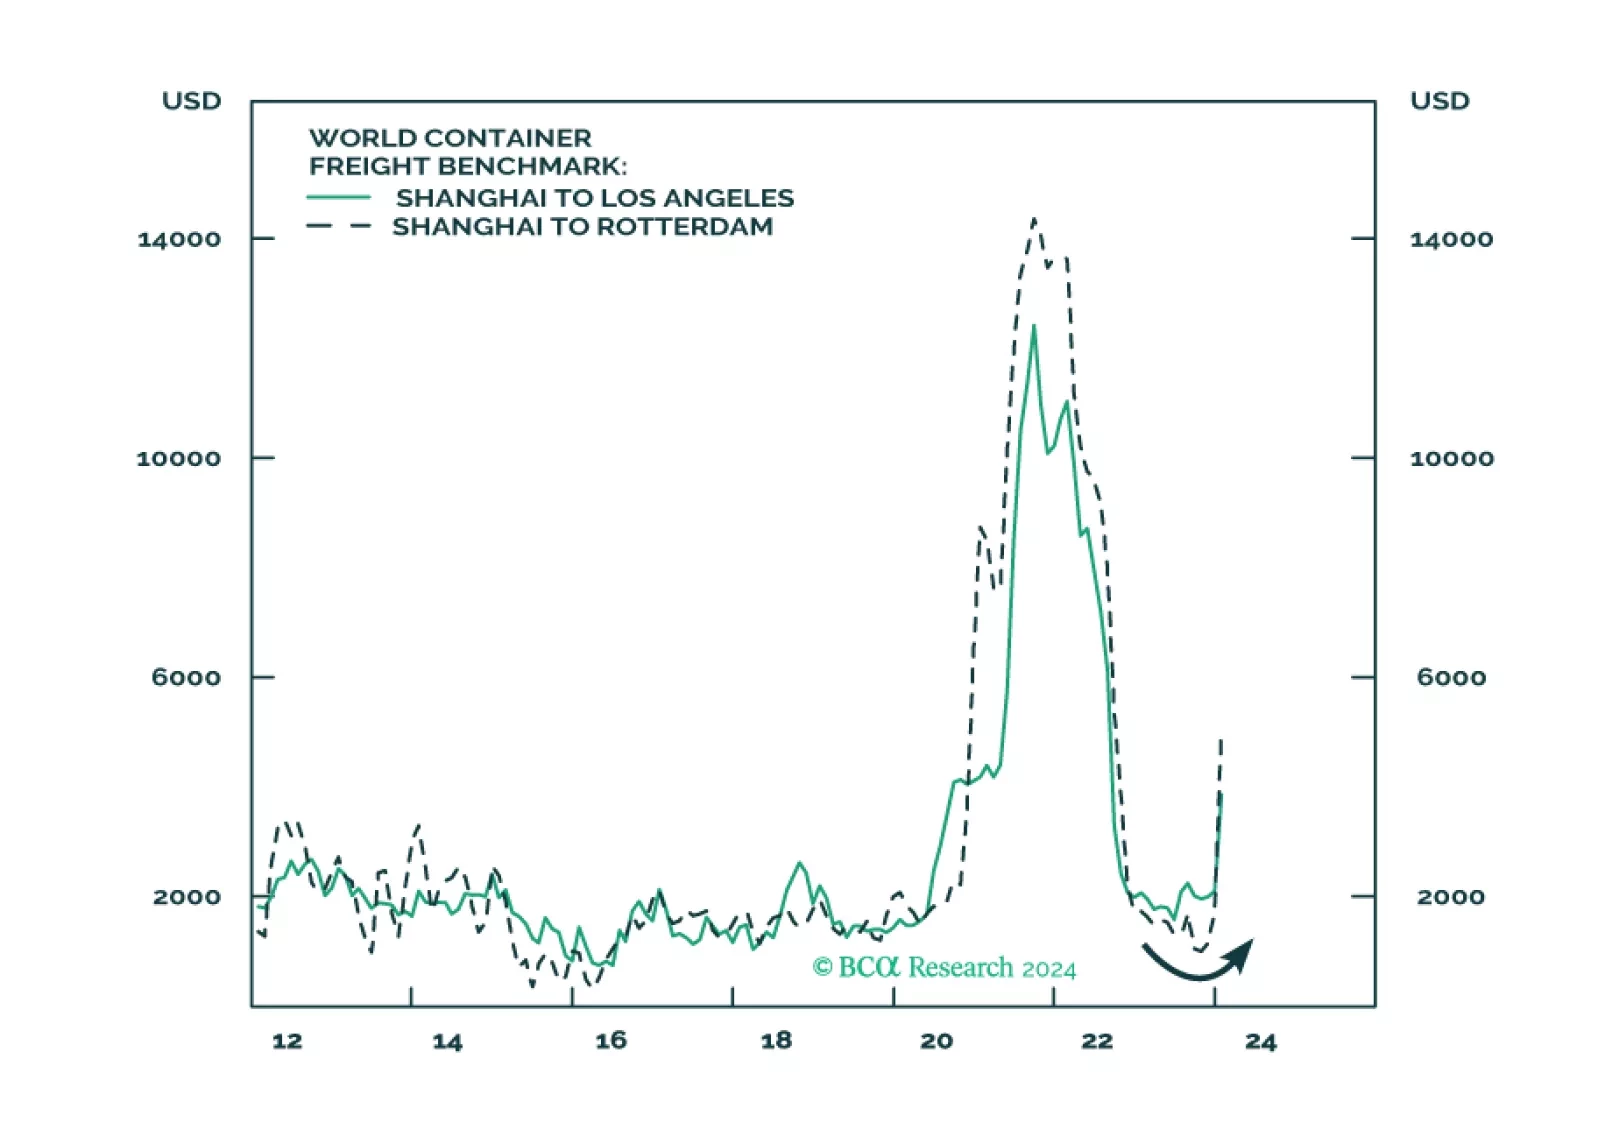
Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.
Middle East conflict, extreme US policy uncertainty, Chinese economic slowdown, US-Russian proxy war, and Asian military conflicts do not create a stable investment backdrop for 2024. Our top five “black swan” risks may be highly improbable, but they stem from these underlying trends.

Chinese policymakers have ramped up their efforts to support the economy and financial markets over the past few days. On Wednesday, the People’s Bank of China (PBoC) announced that on February 5 it will cut the reserve requirement ratio by 0.5 percentage…
According to BCA Research’s China Investment Strategy service, the current Pledged Supplementary Lending (PSL) program will provide much less support to the housing market and construction activity than the 2015-2018 program. China’s central bank…