Equities
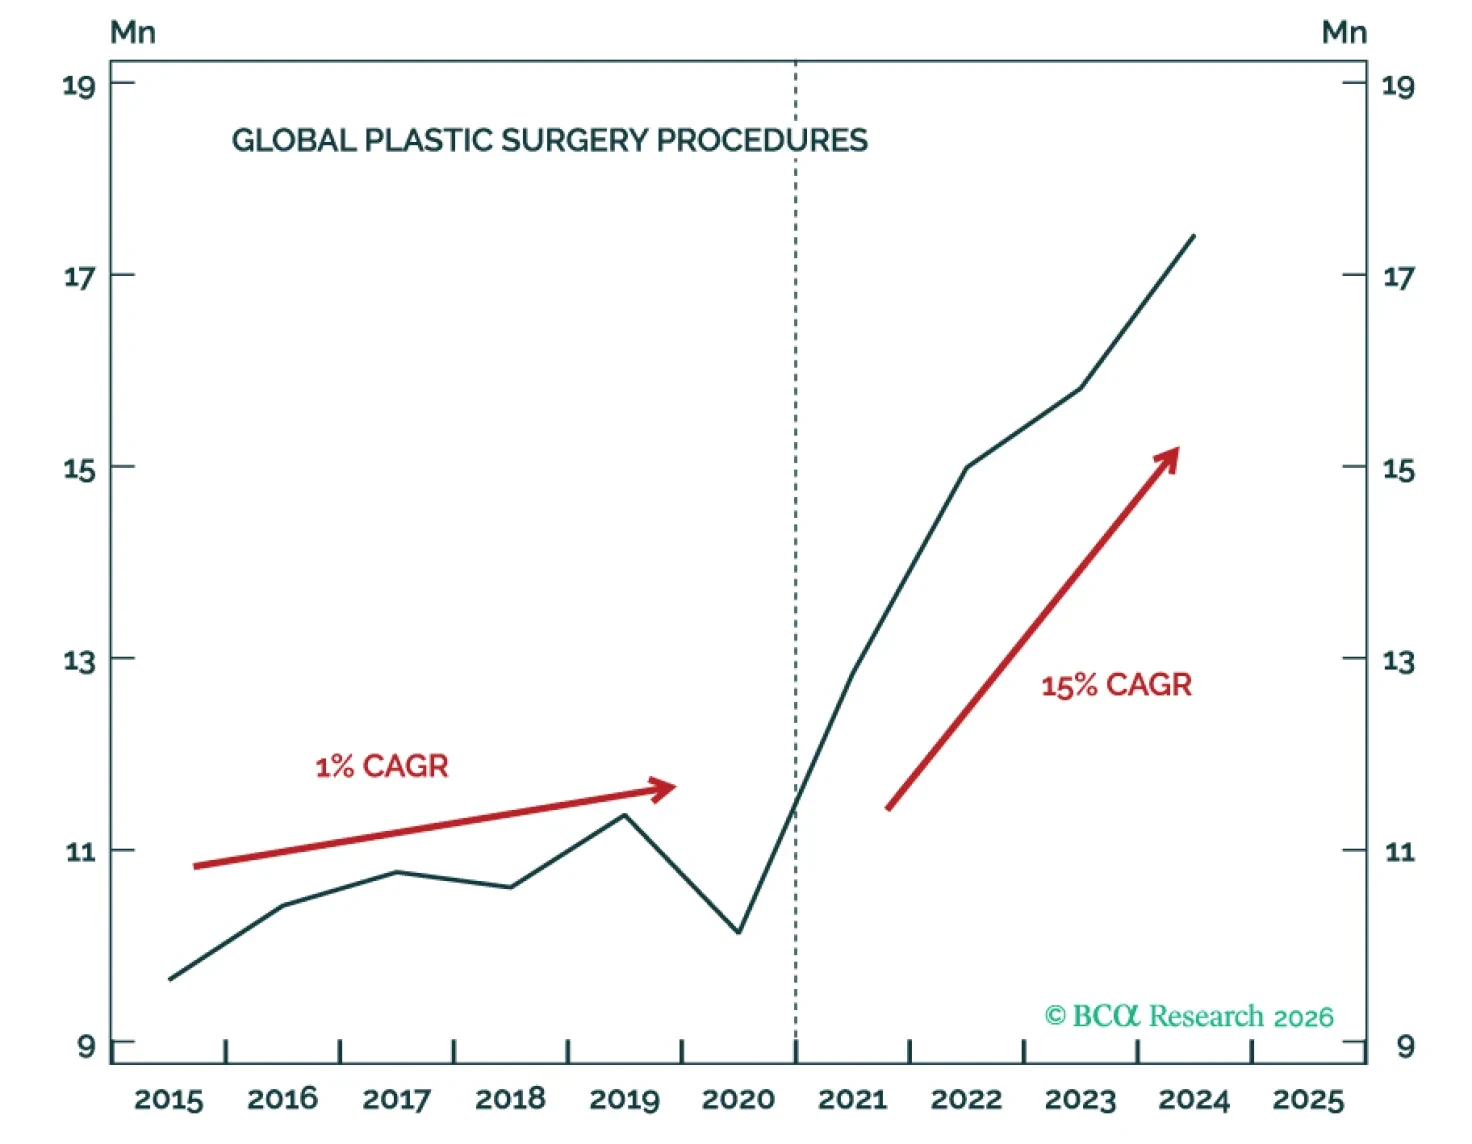
The rise of remote work, online dating, and other demographic changes are increasing the demand for aesthetics. GLP-1s provide an effective and inexpensive cure for obesity, and their secondary effect “Ozempic face” has structurally altered the demand for aesthetic procedures and skincare. Long GLP-1 producers, biostimulator injectable producers, and K-Beauty contract manufacturers.
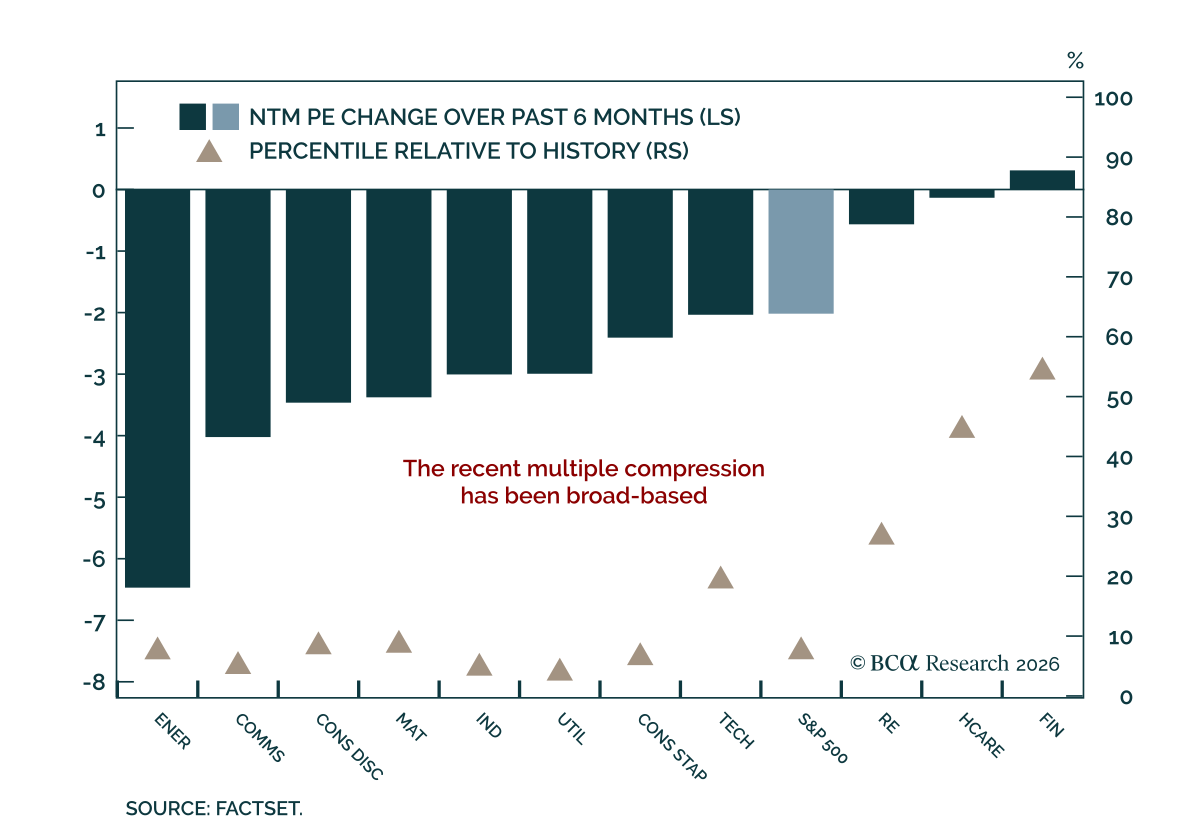
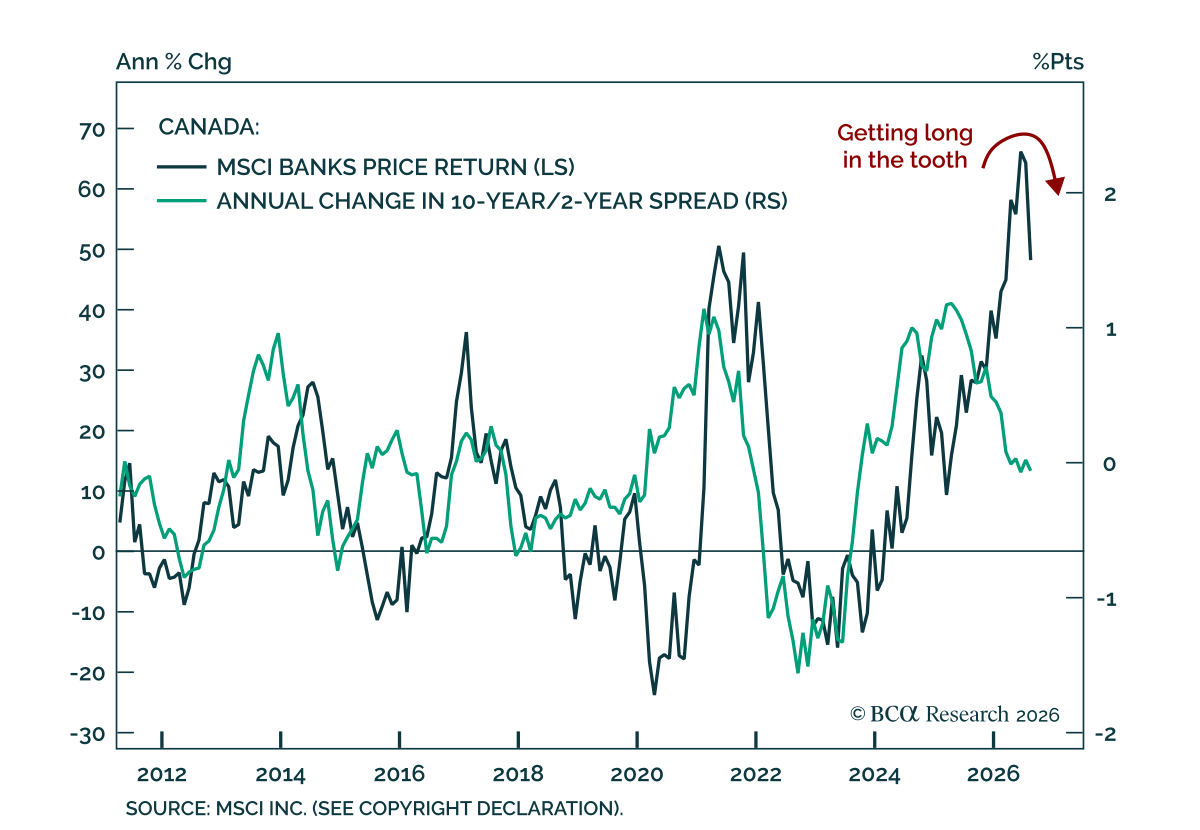
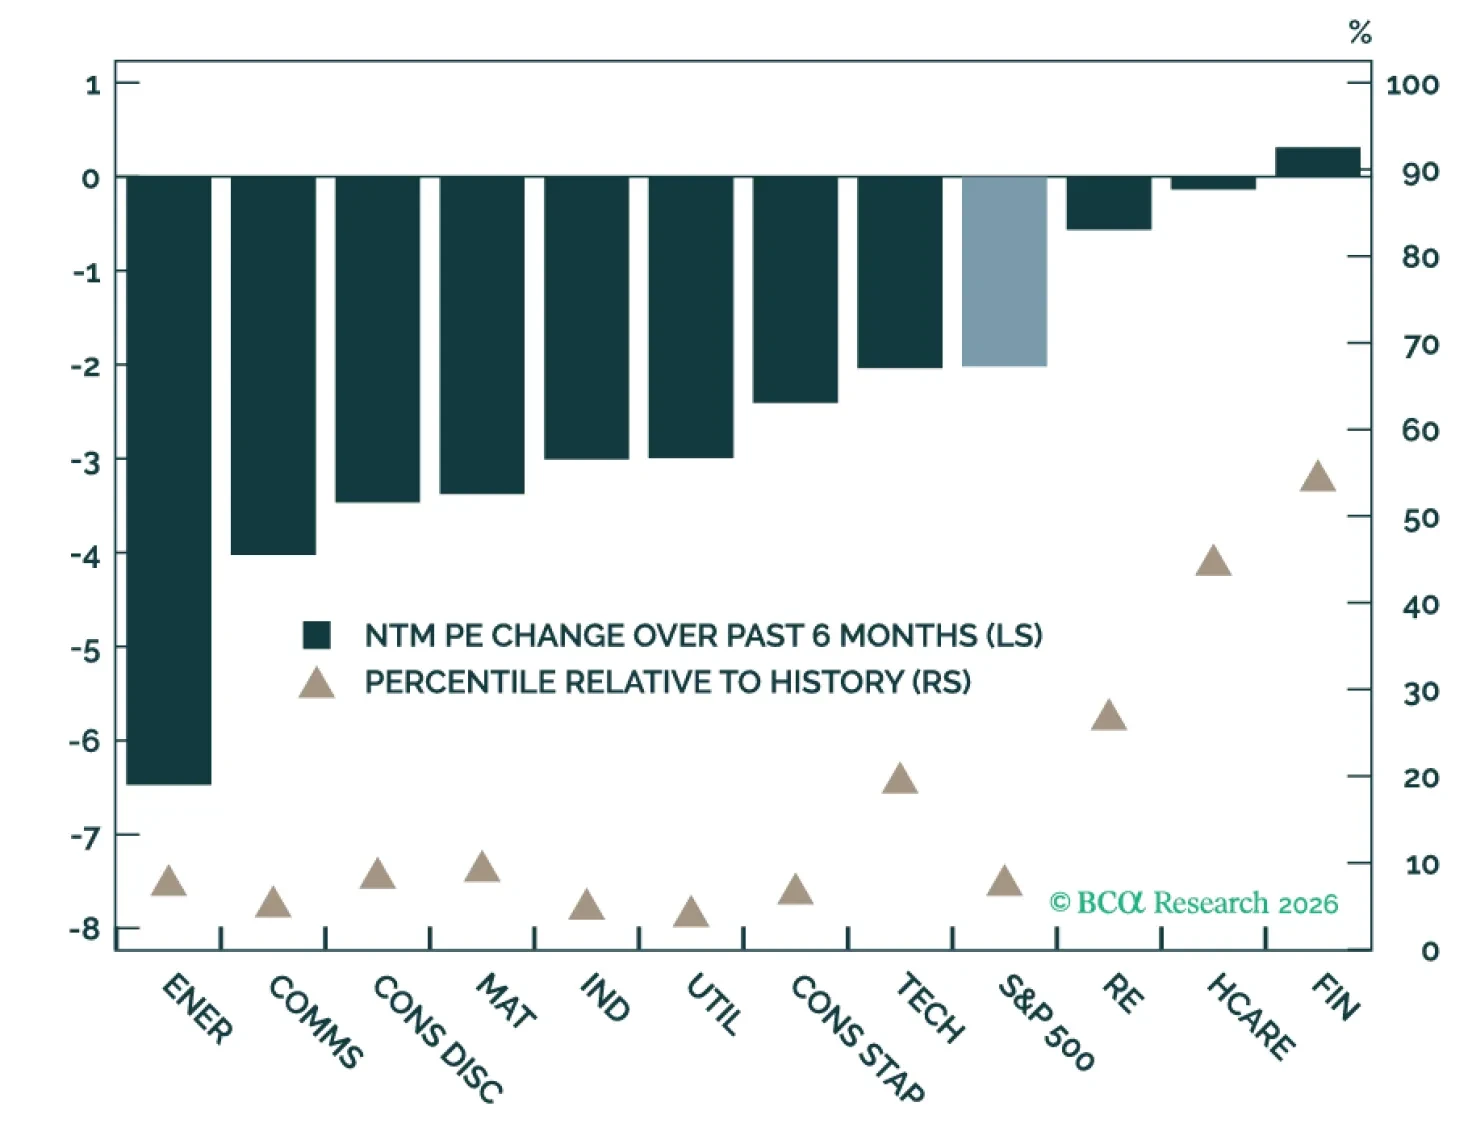
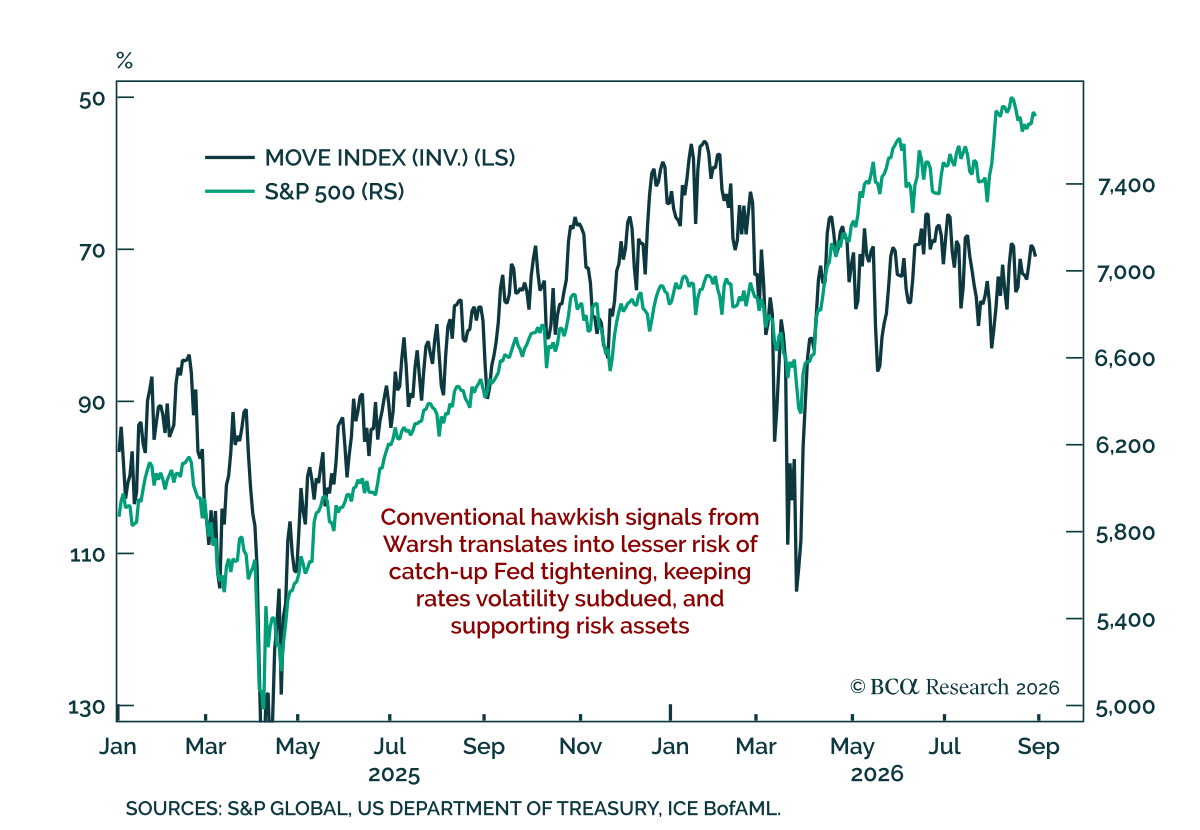
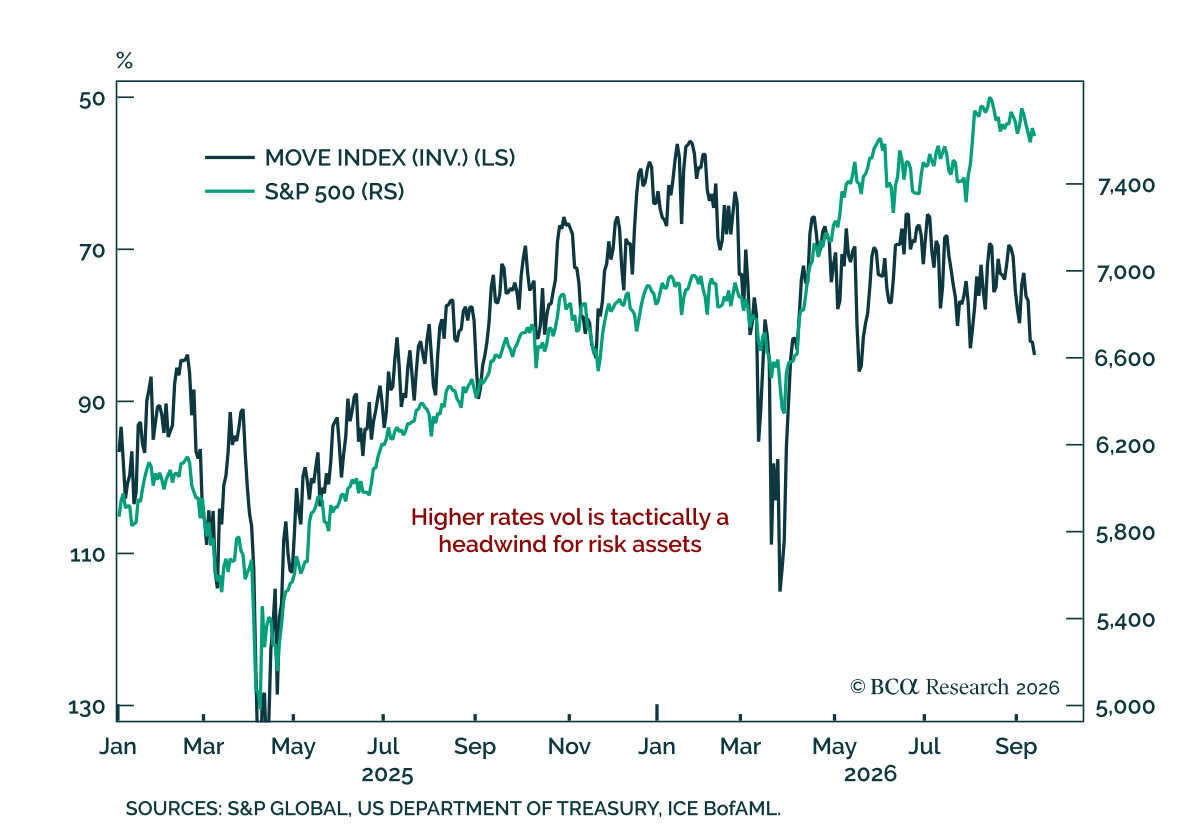
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
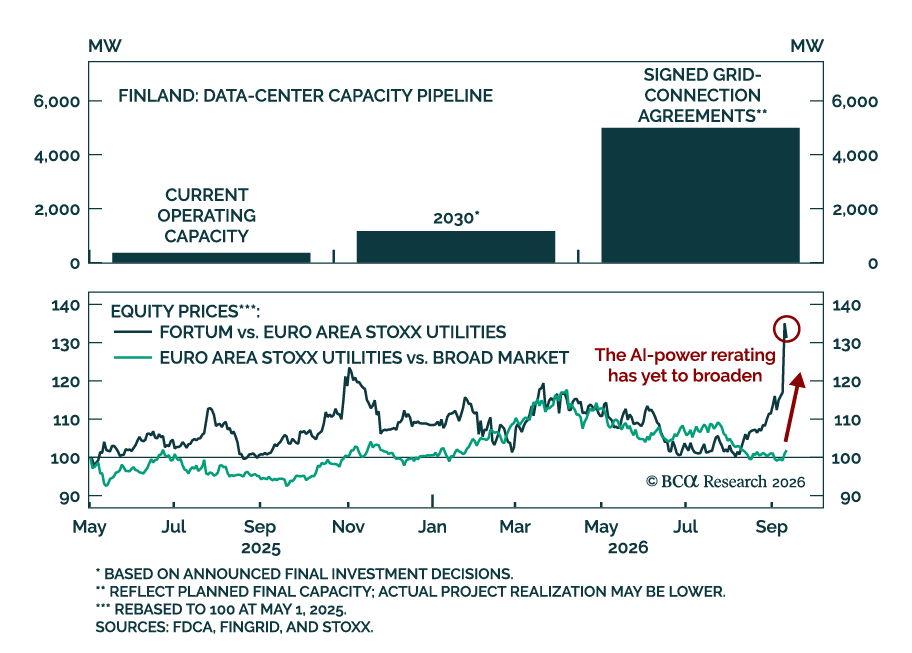
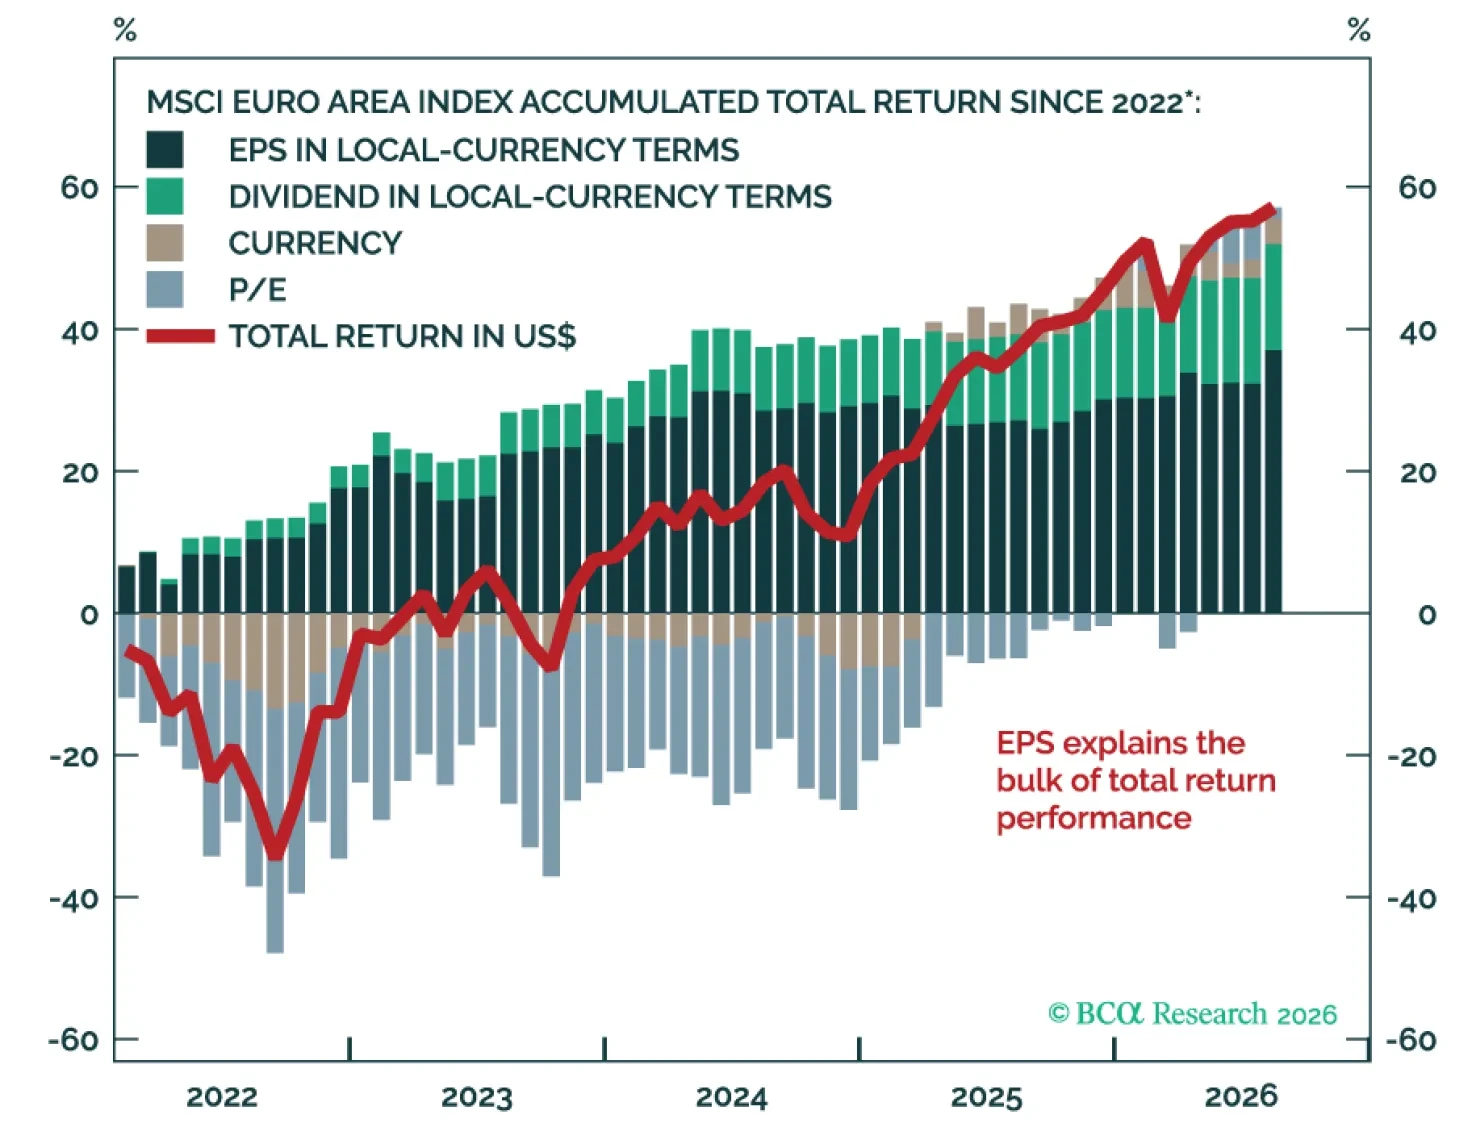
Europe’s earnings recovery is increasingly difficult to dismiss. Margins, ROE, ROIC, and capital efficiency have all improved, while banks have re-emerged as an earnings engine. Cyclical conditions remain supportive, and the structural picture continues to improve: higher investment, improving productivity, and EU reforms could give the recovery staying power.
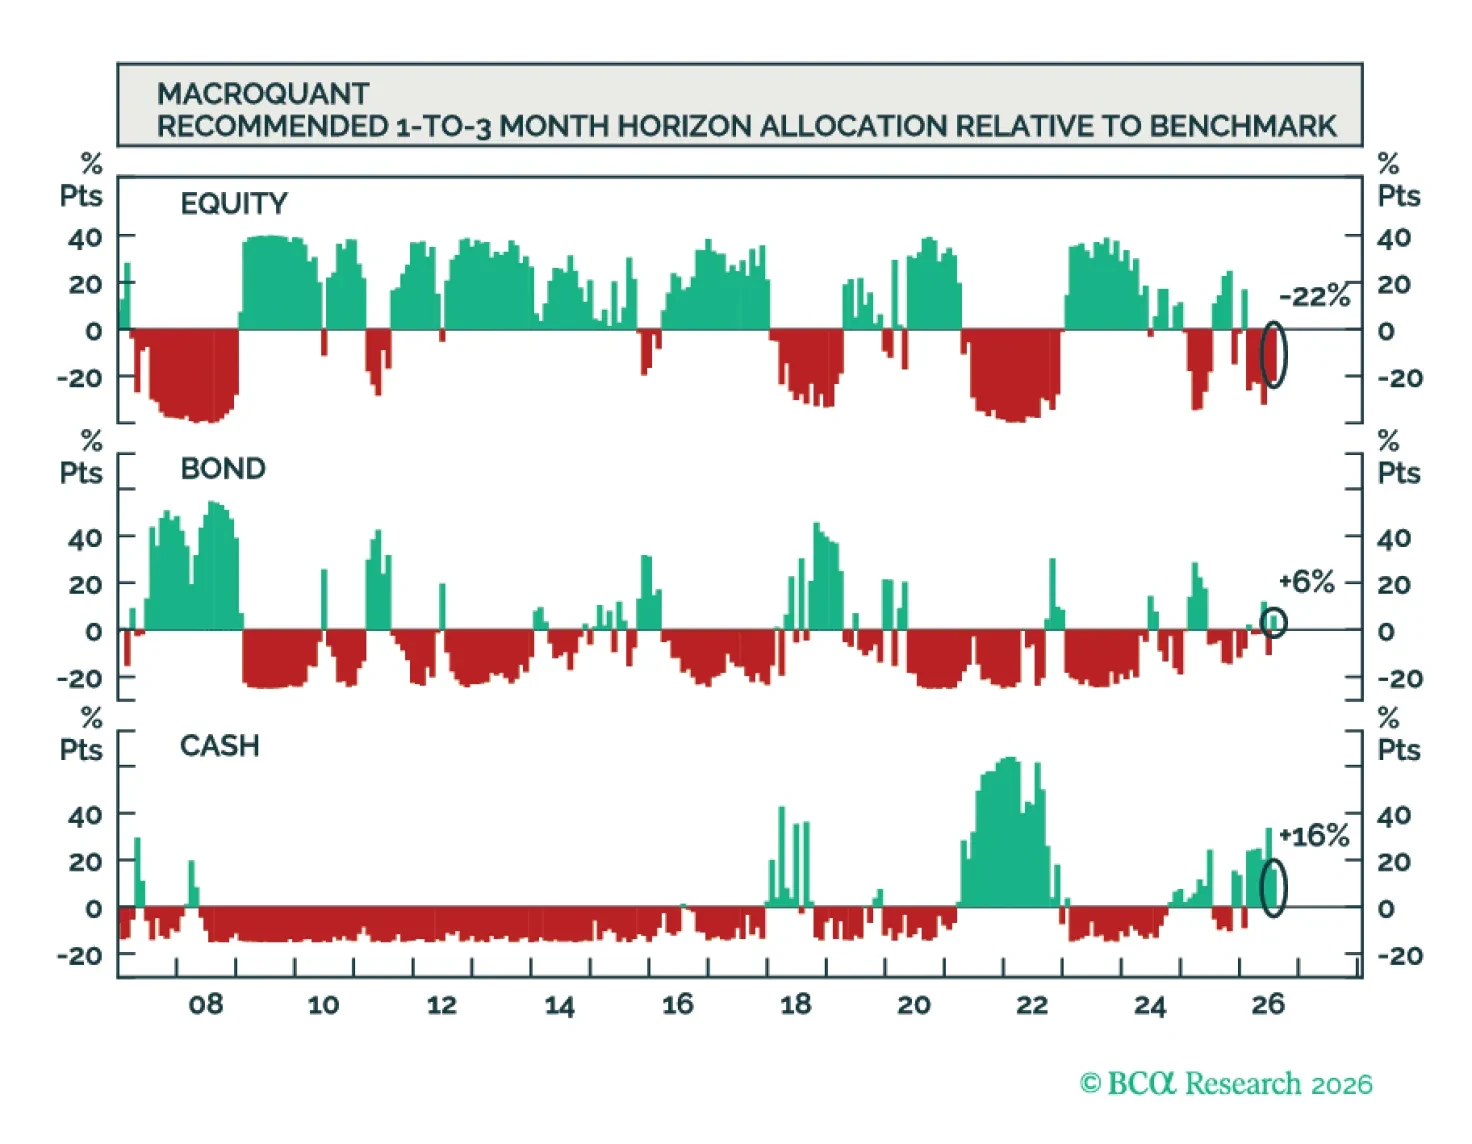
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.