Fixed Income
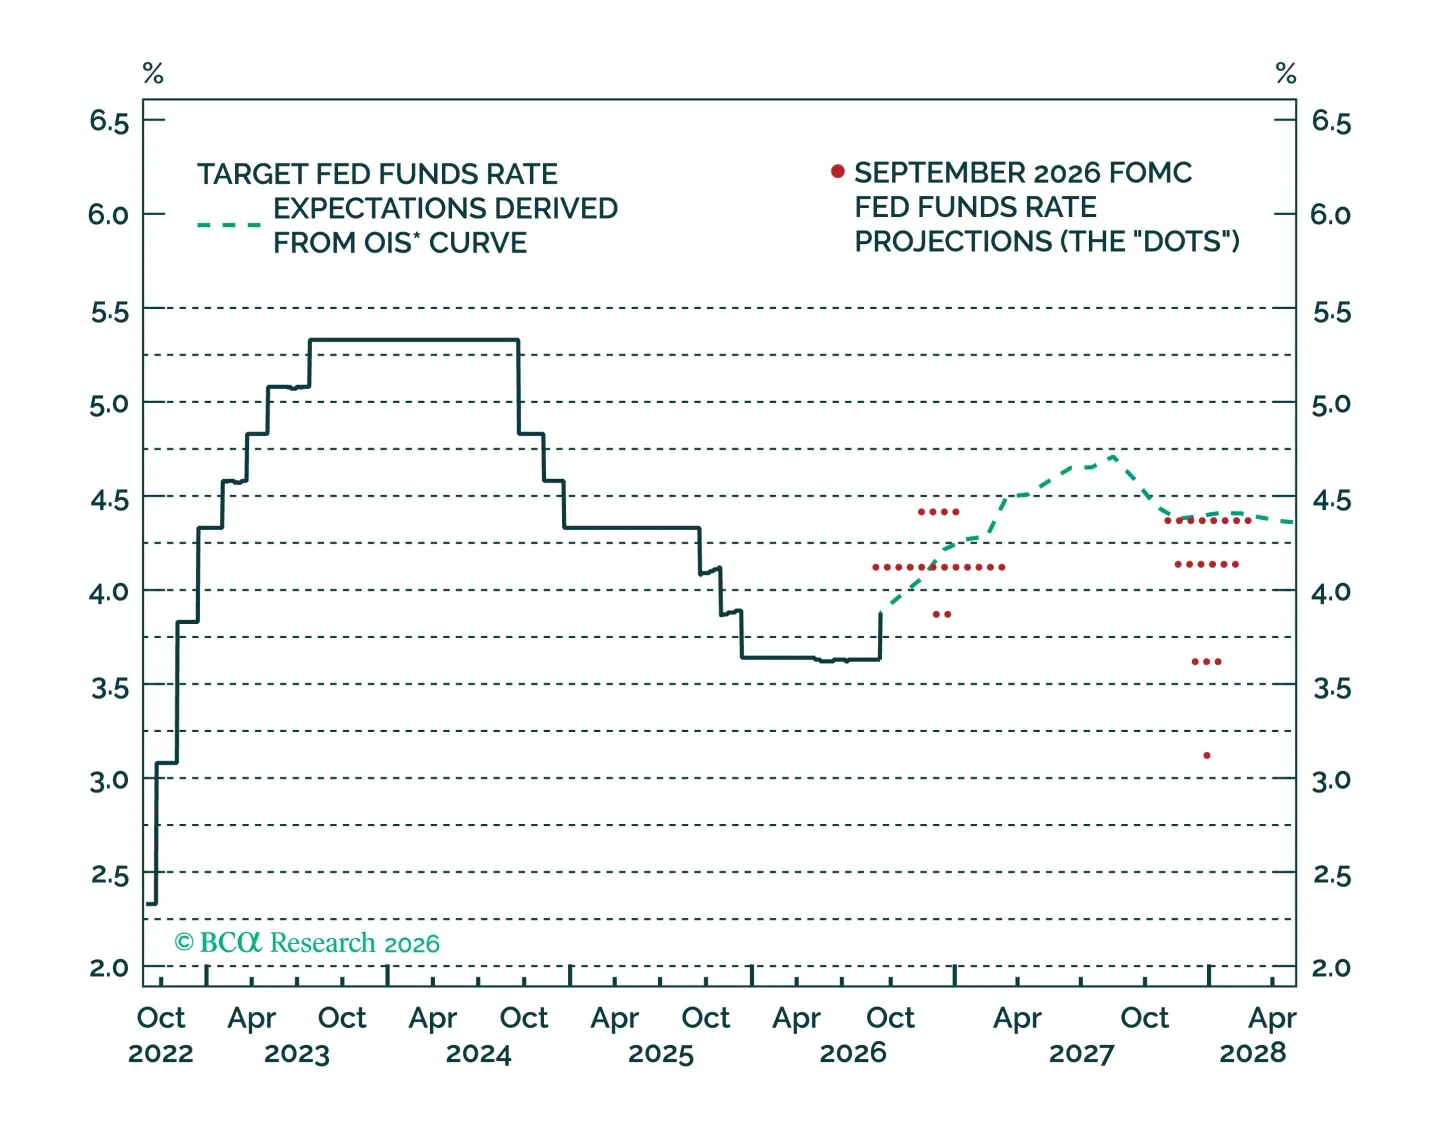
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
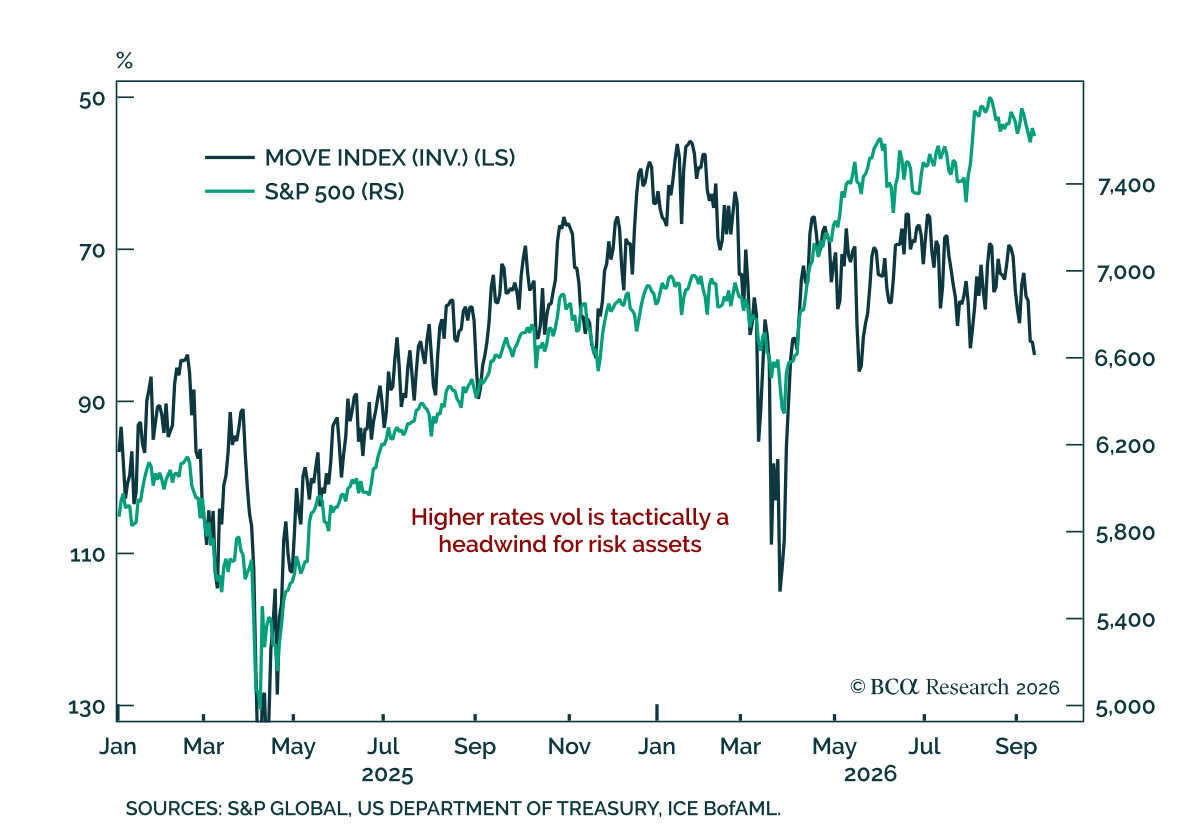
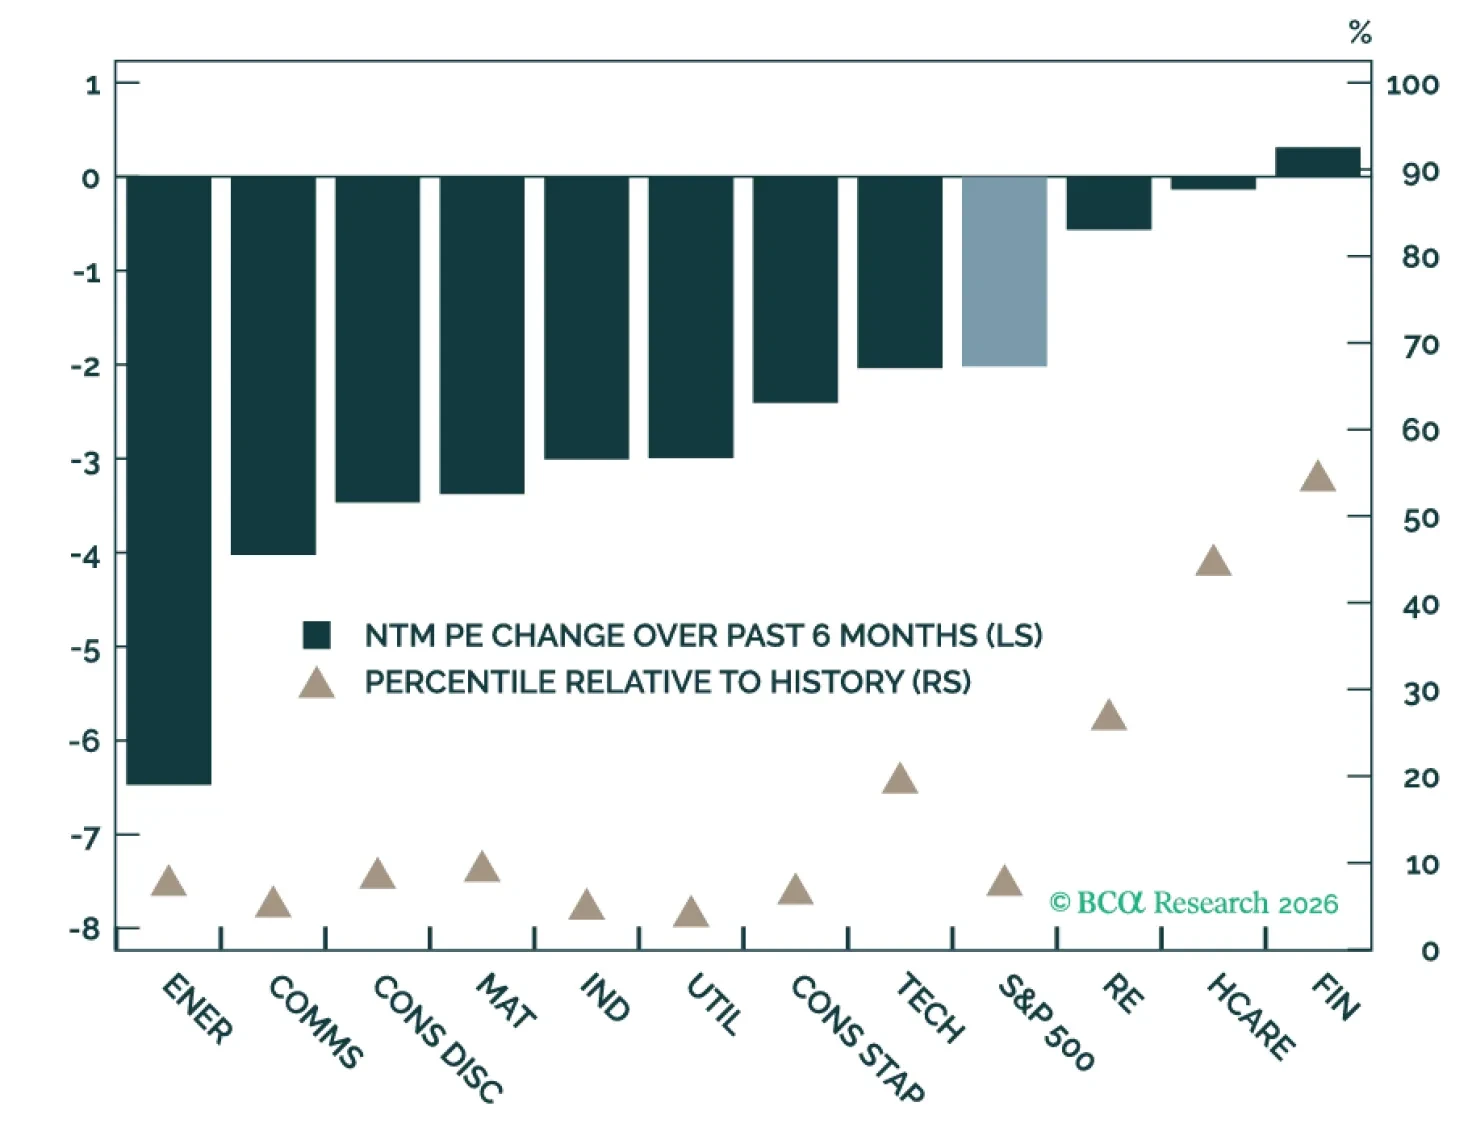
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
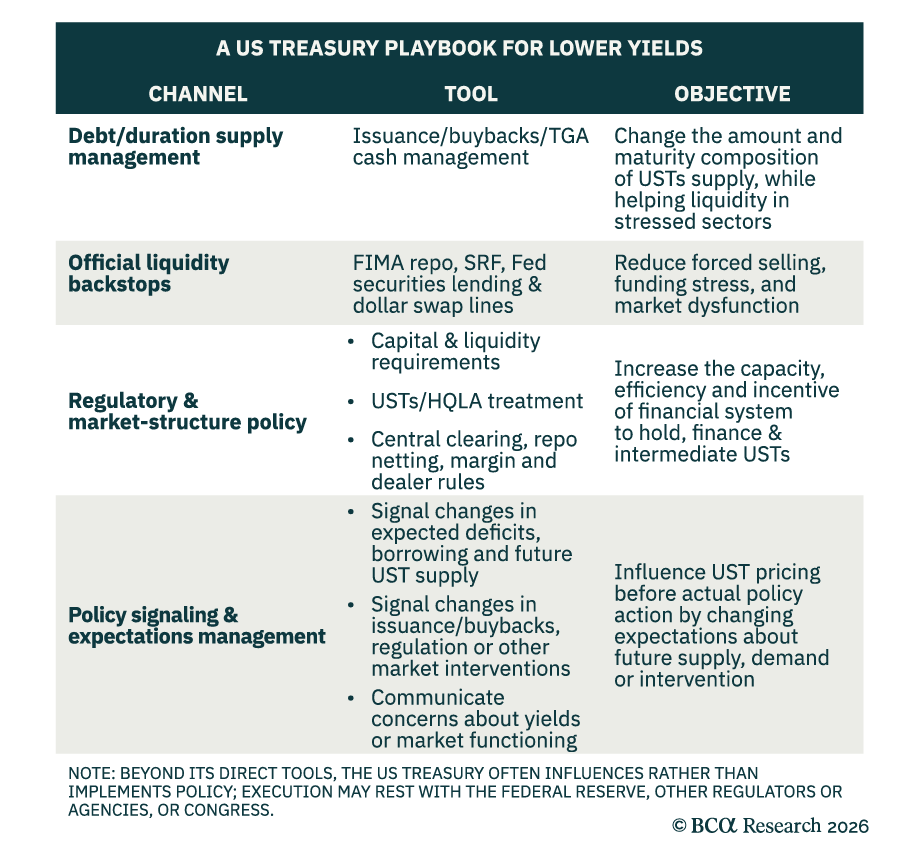
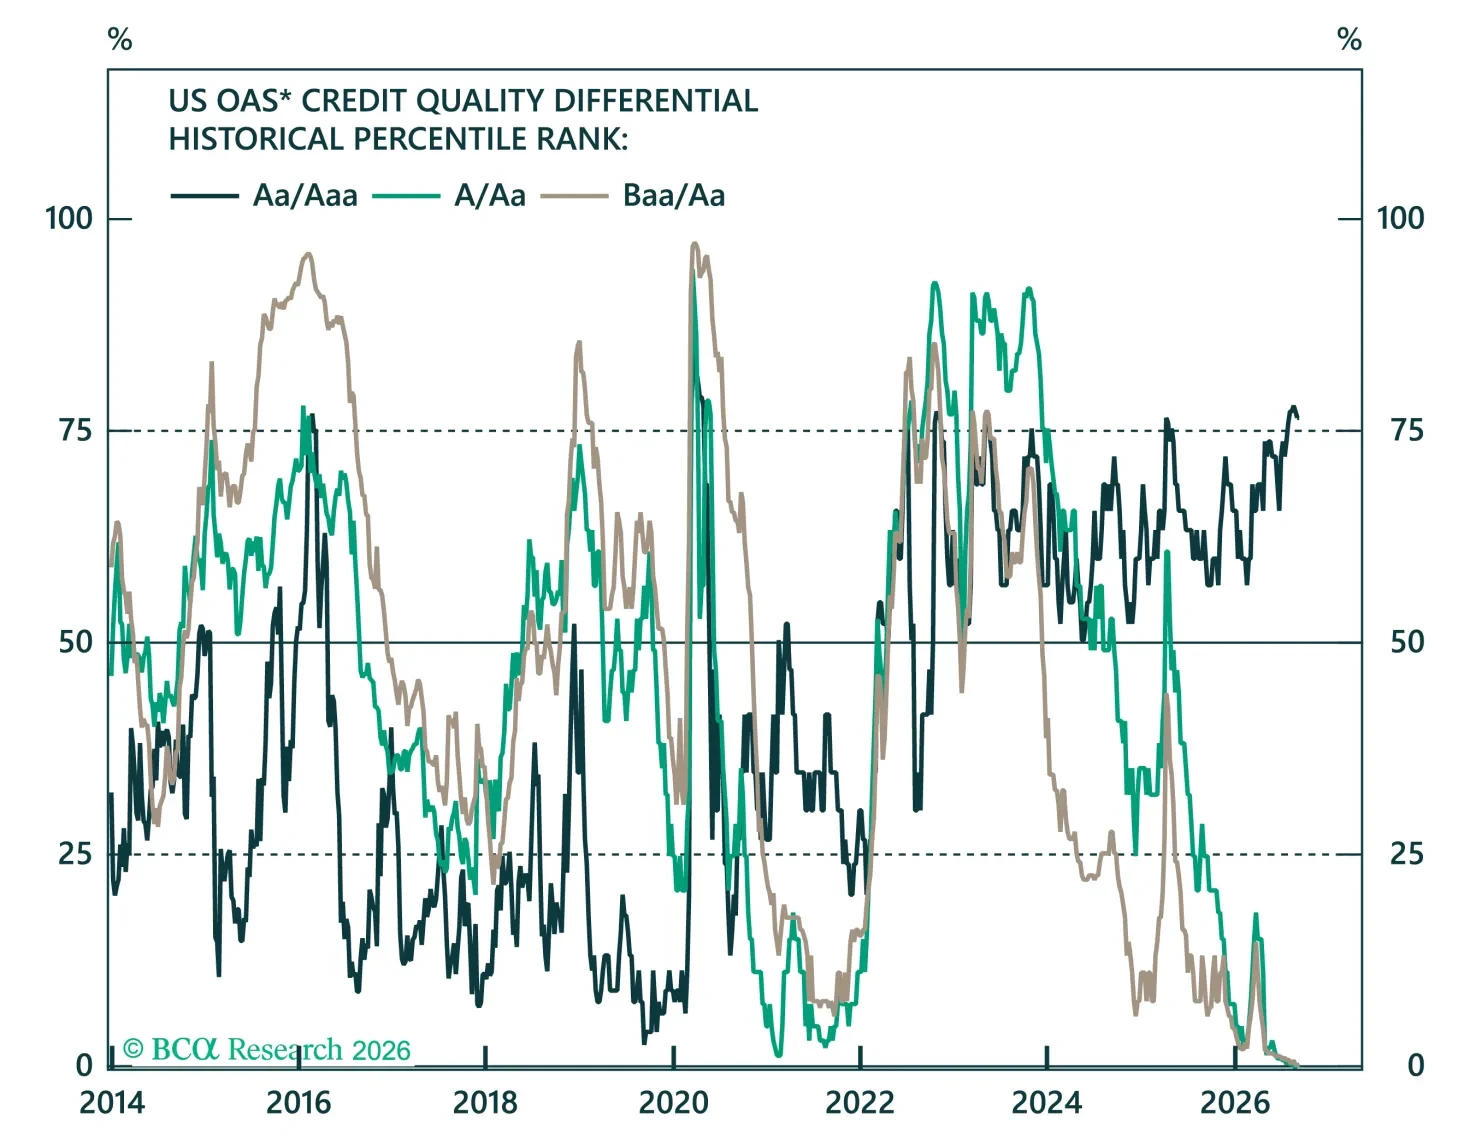
After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
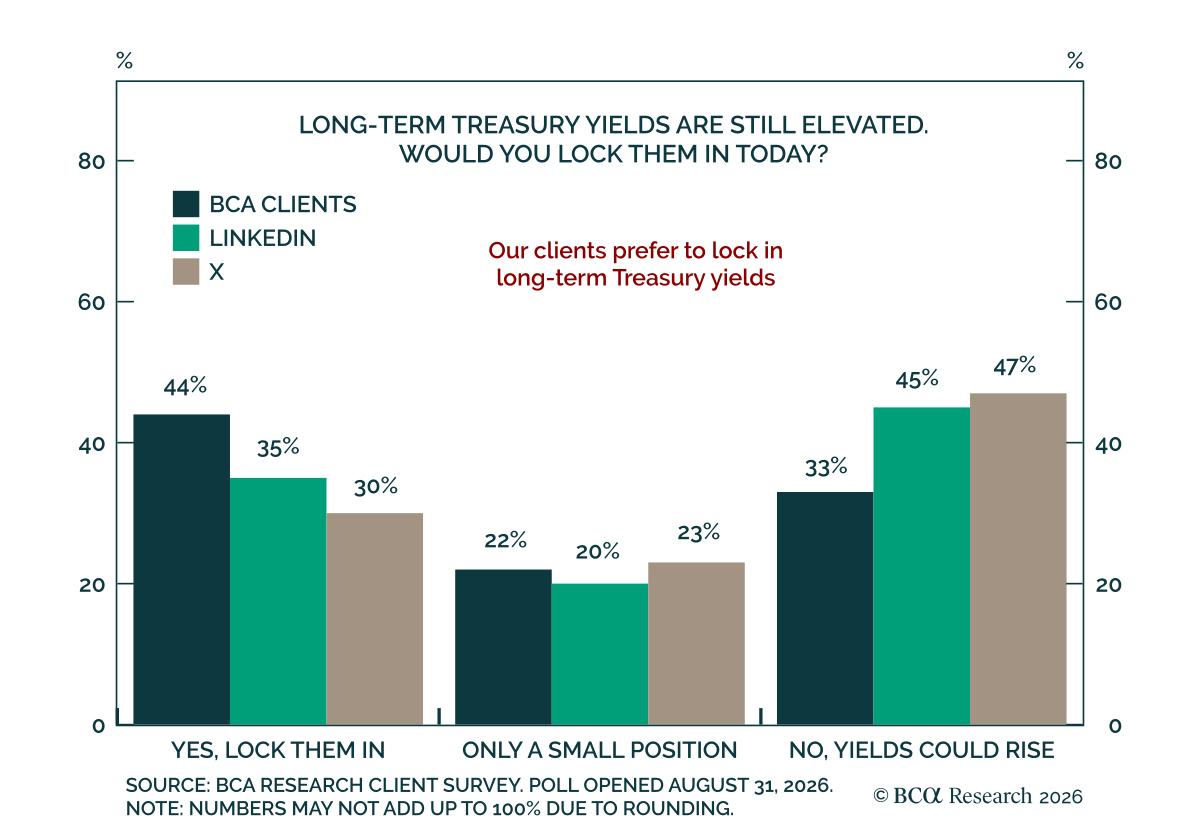
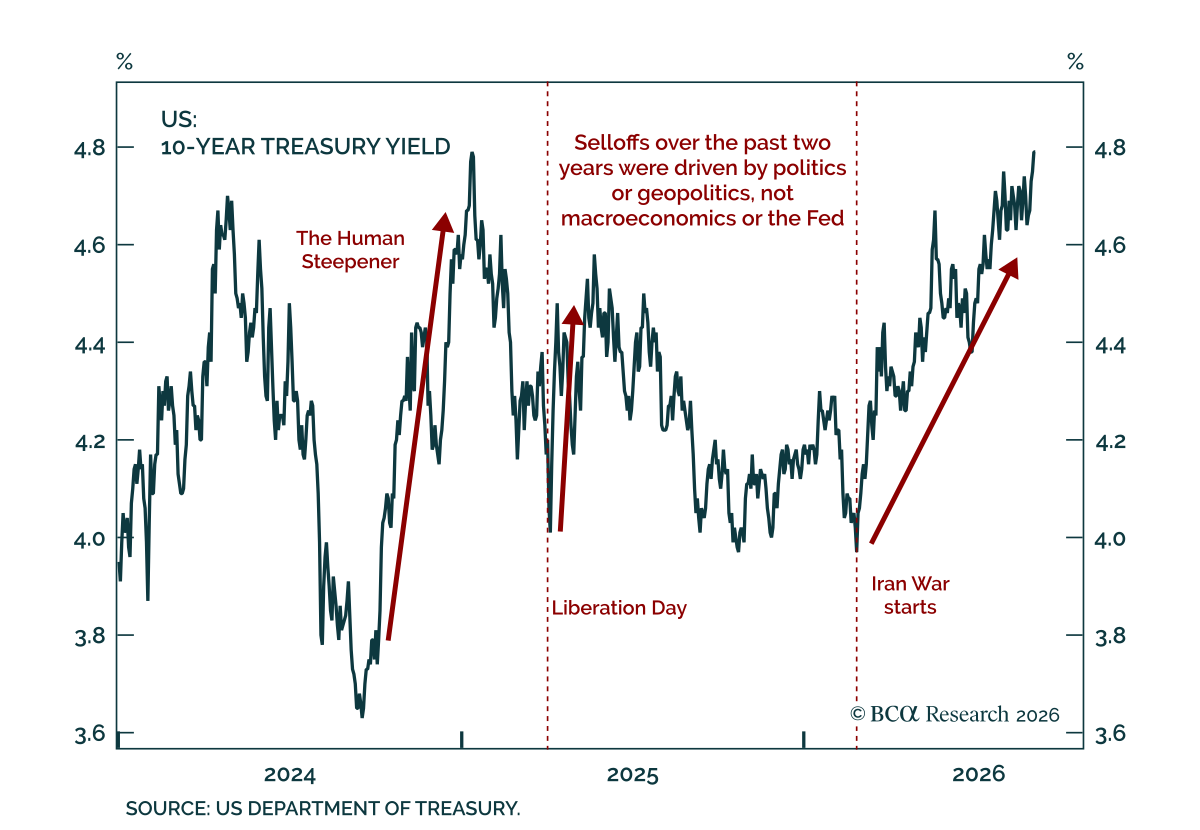
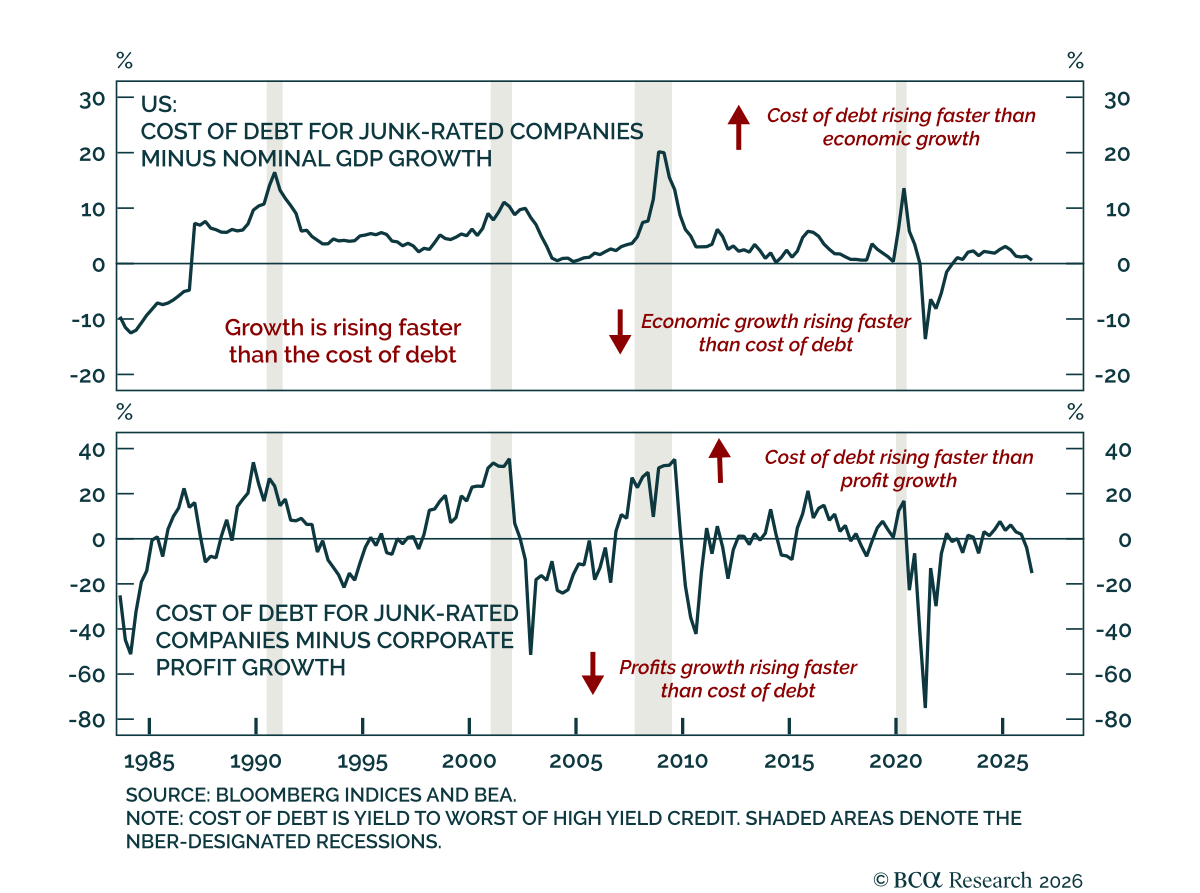
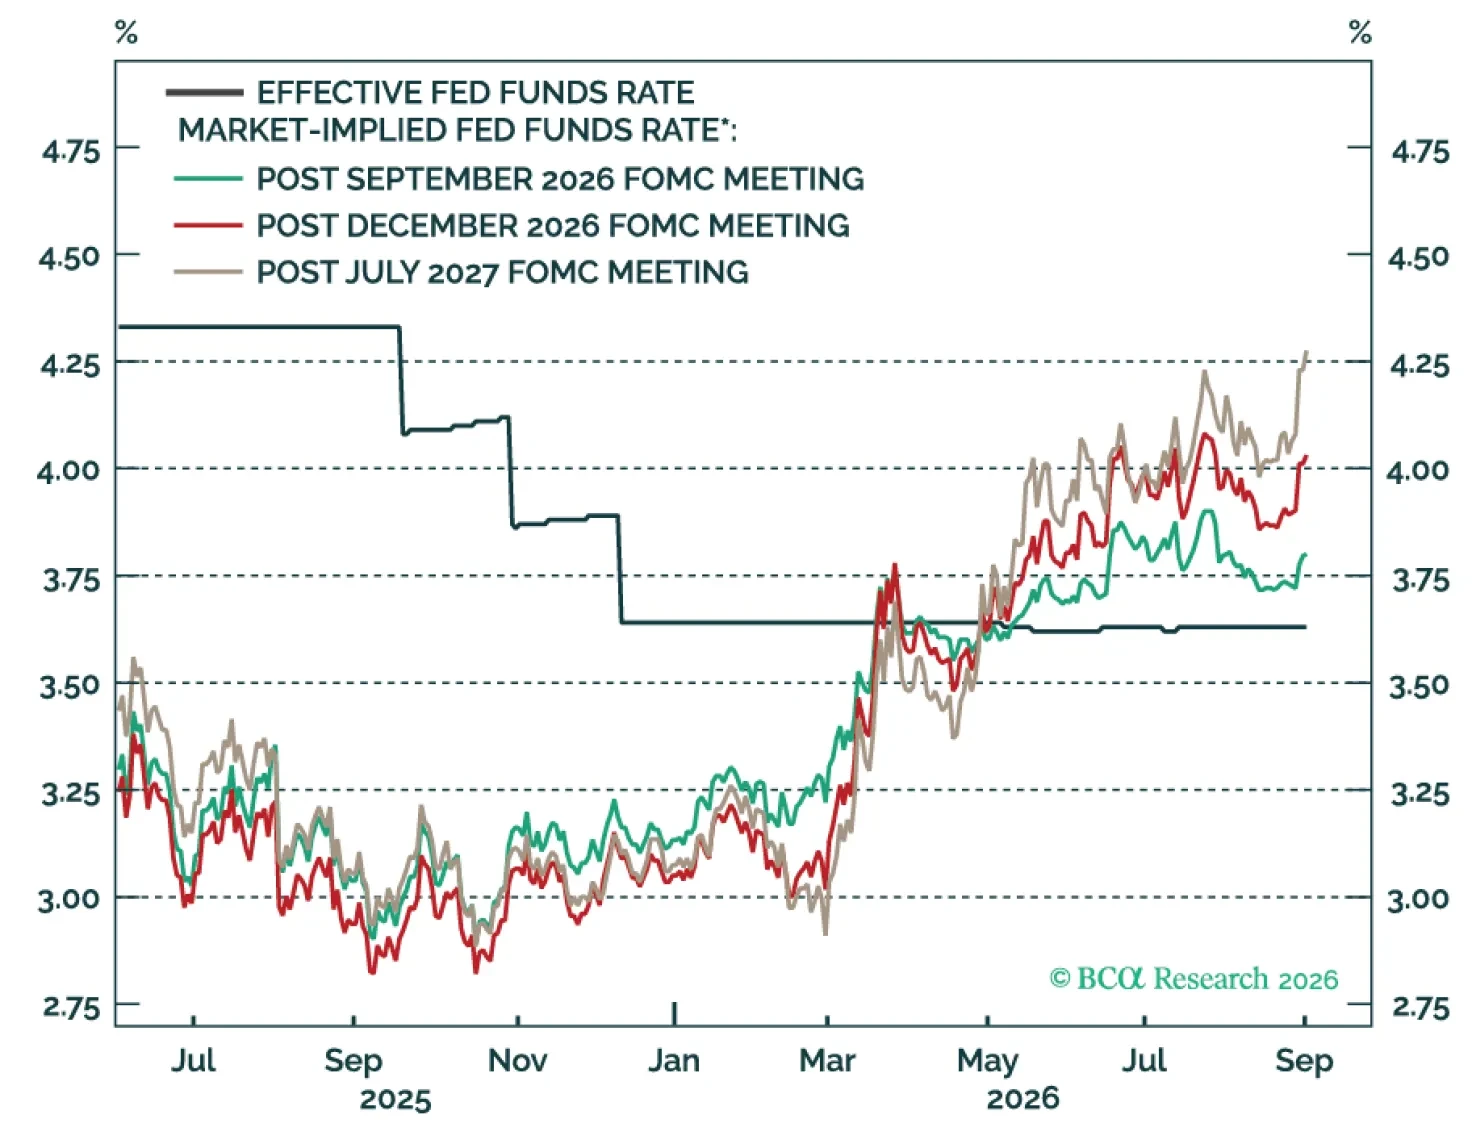
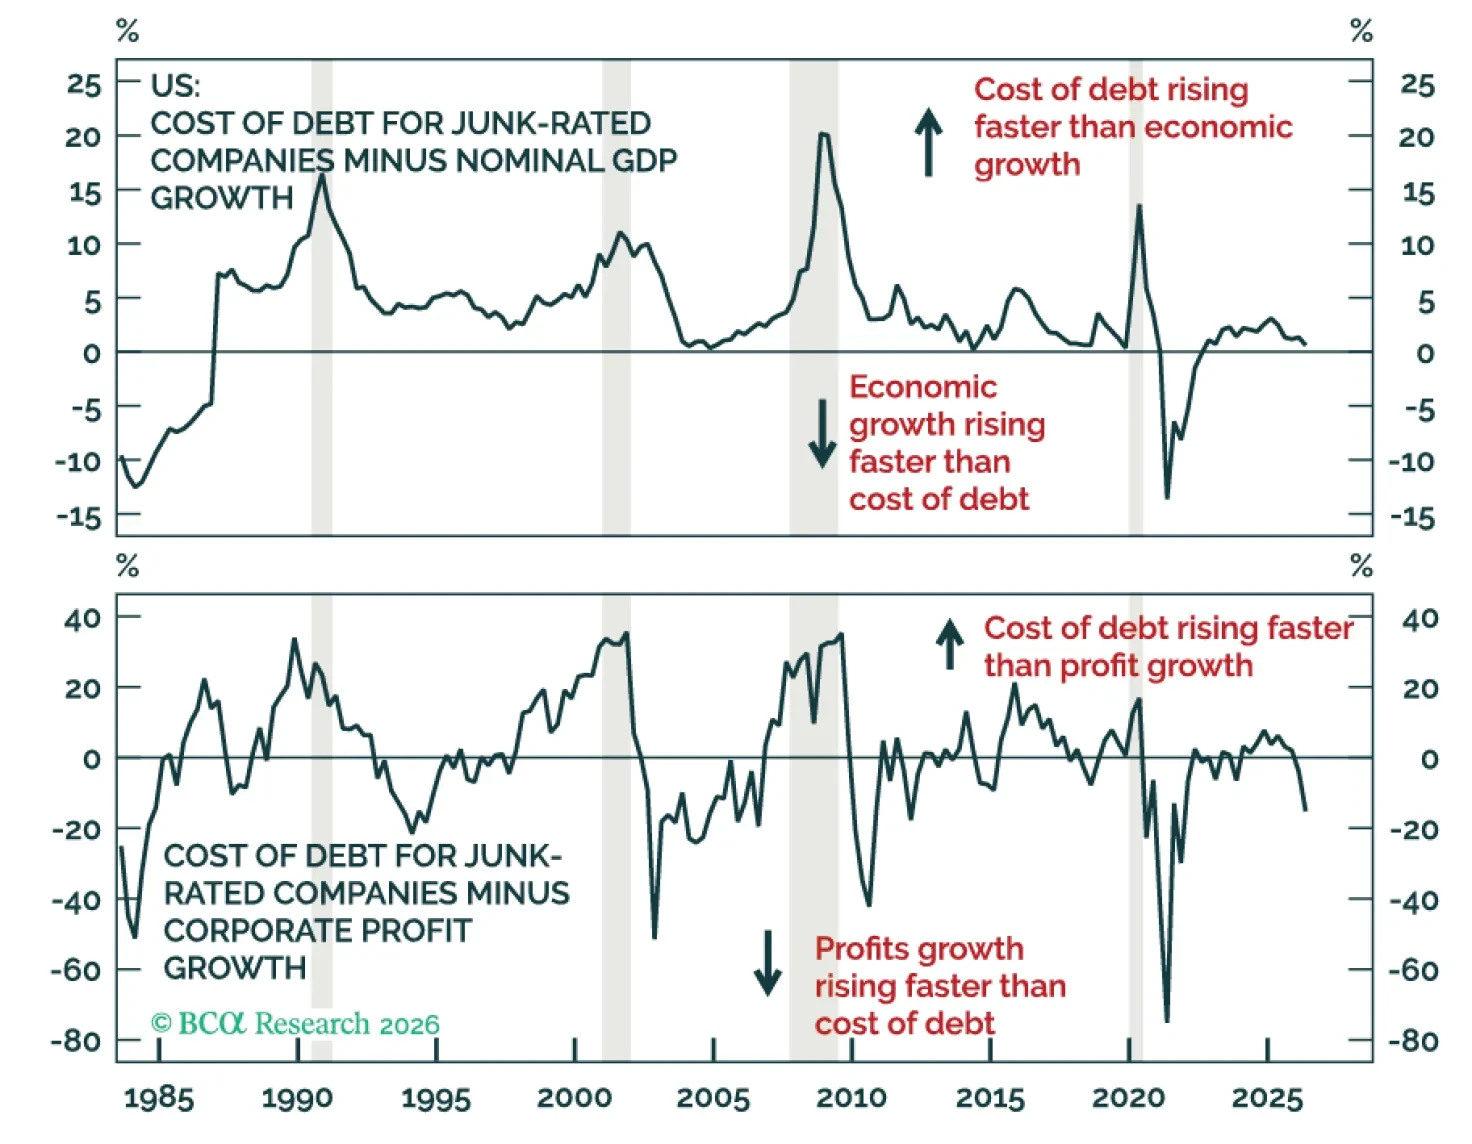
Investors overestimate the threat current interest rate levels pose to both equities and the economy. Despite a rising long end, the gap between high-yield borrowing costs and both nominal growth and corporate profits is at five-year lows and falling. Remain overweight equities. Within Fixed Income, Upgrade High Yield and Downgrade Government Bonds and EM Debt. Downgrade Chinese Equities to Neutral.