
Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Manufacturing

Flash estimates for several European PMIs were released Tuesday. The results for manufacturing activity were somewhat disappointing. The German manufacturing PMI increased from 41.9 to 42.2, but underperformed expectations of 42.7. France’s manufacturing…
Preliminary S&P PMIs for the US showed the manufacturing index declined to contraction territory of 49.9 from 51.9, falling short of expectations of 52. The services PMI also disappointed coming in at 50.9, versus expectations it would improve from 51.7…

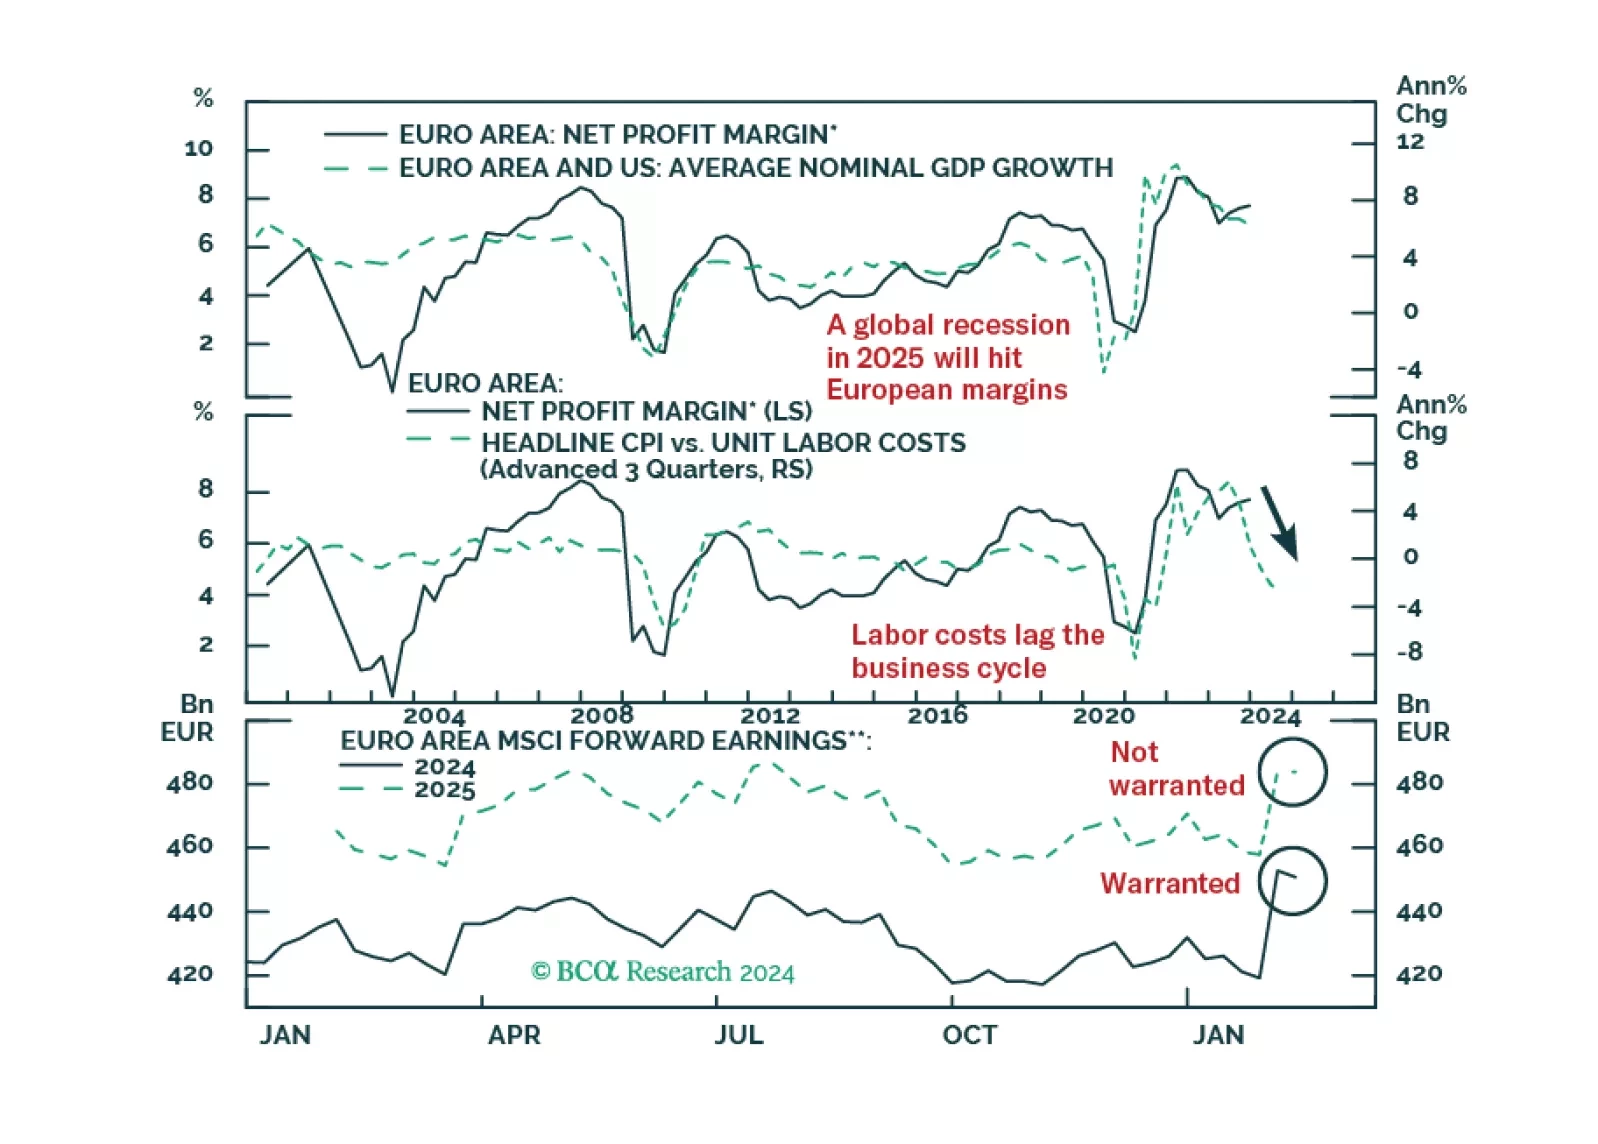
European profits margins are elevated. Will a mild recession be enough to bring them down?
The headline Philadelphia Fed manufacturing survey for April delivered a positive surprise on Thursday, increasing from 3.2 to a twelve-month high of 15.5 and beating expectations it would soften to 2.0. Measures of demand improved with new orders and…

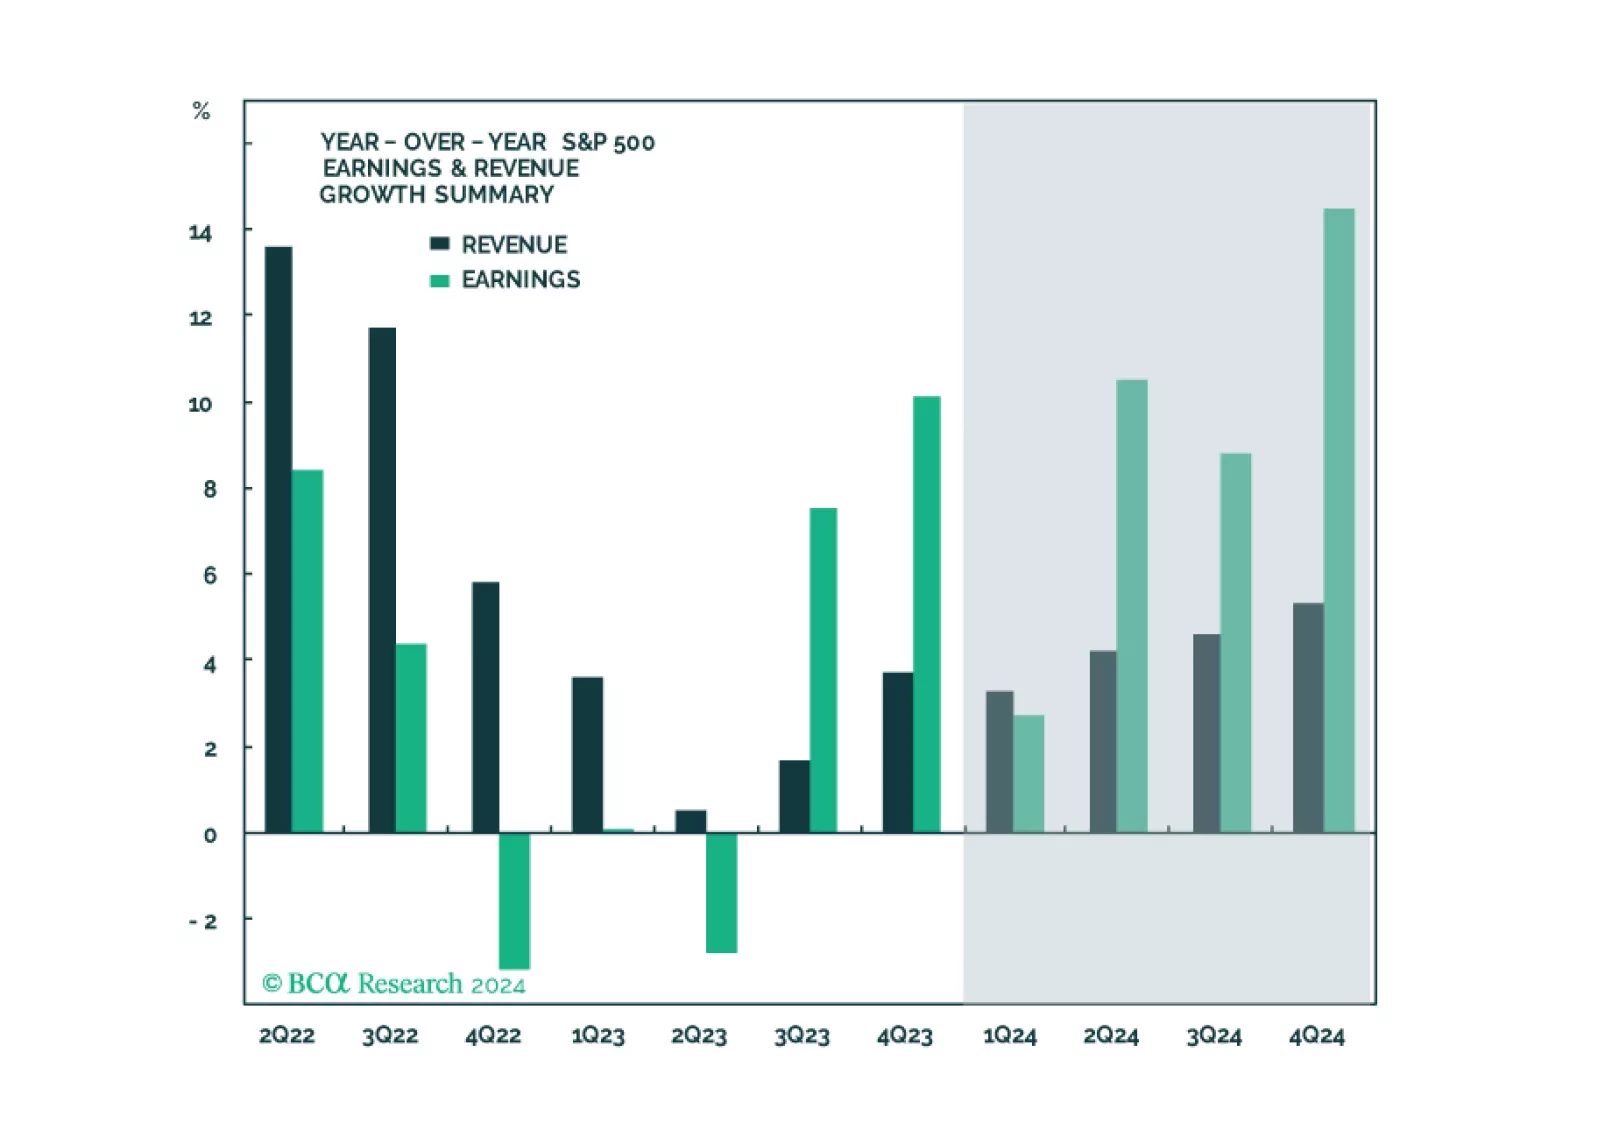
In this note, we preview the Q1-2024 earnings season, give our take on expectations and share what we will be watching.
Optimism about the future continues to boost investor confidence in the Euro Area.  The ZEW Expectations series for the Eurozone (+10.4 to 43.9) and Germany (+11.2 to 42.9) surged and are now both at their highest in 26 months. Although investors’…

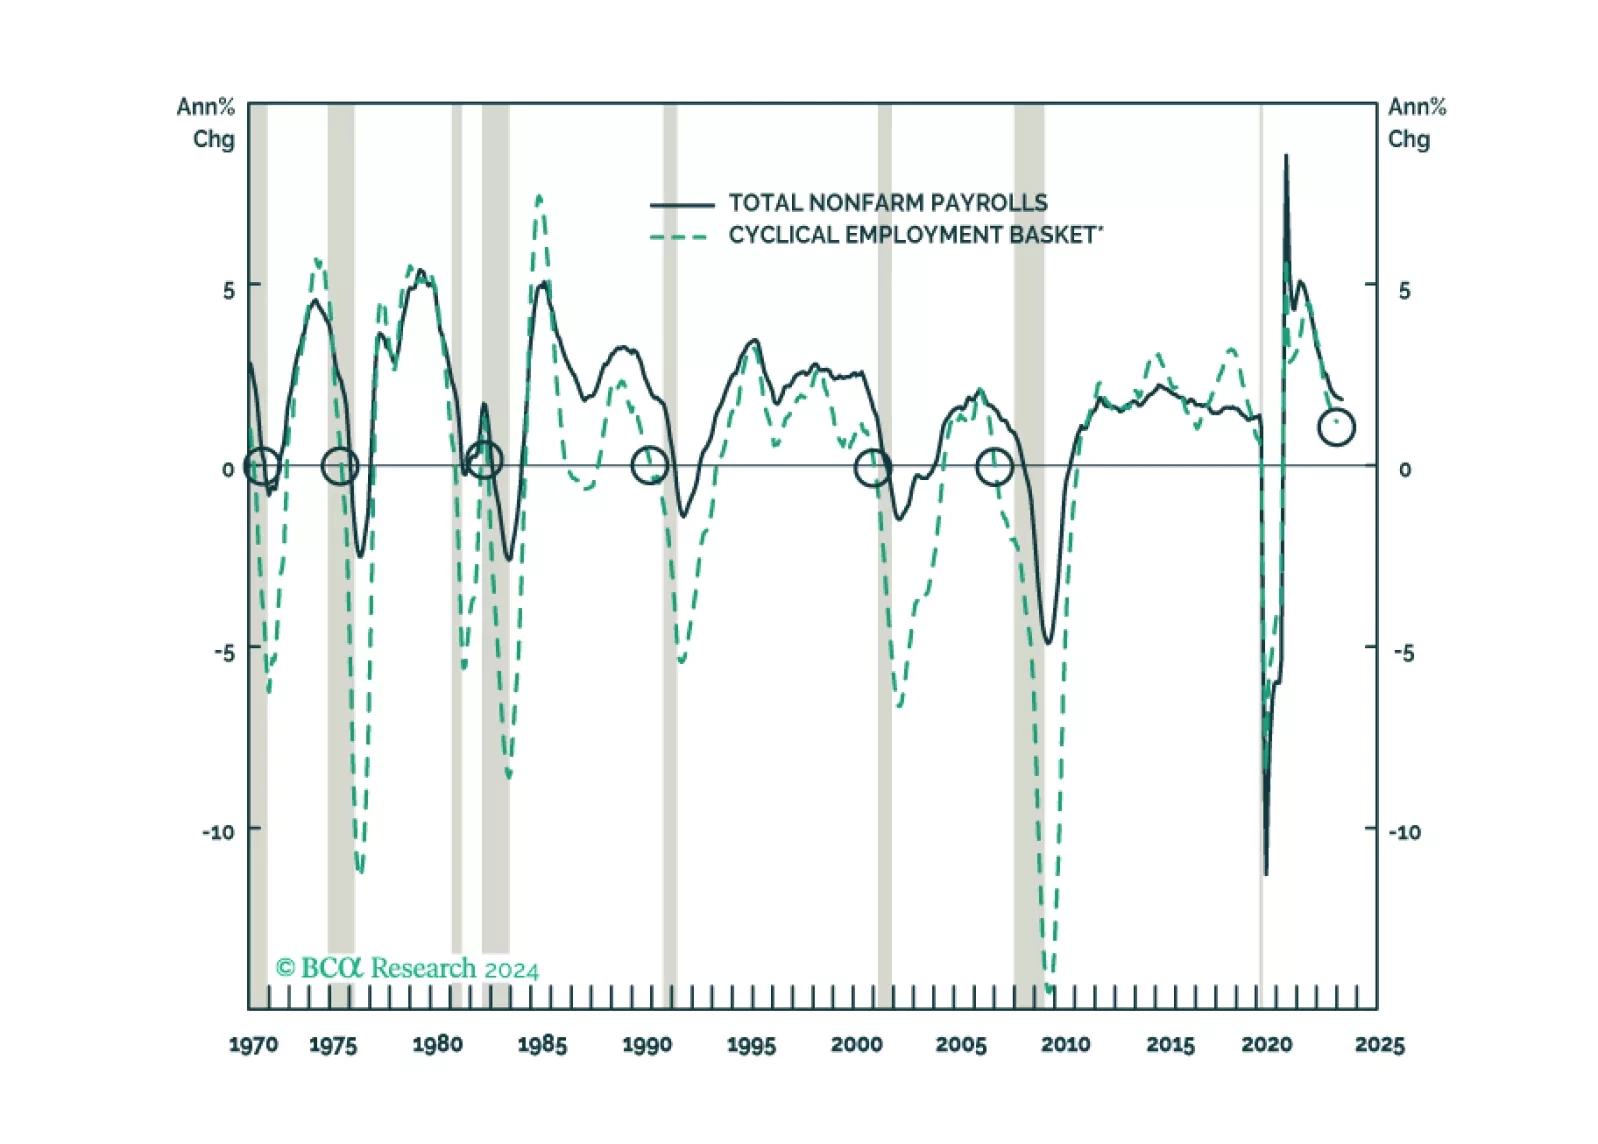
We look beneath headline data to assess the state of the labor market in cyclical goods-producing industries that have previously led overall nonfarm payrolls and in the services segments that have recently been leading the charge. The bottom-up view looks a lot like the top-down view: the labor market is softening, but very slowly, and offers no indications that a recession is at hand.
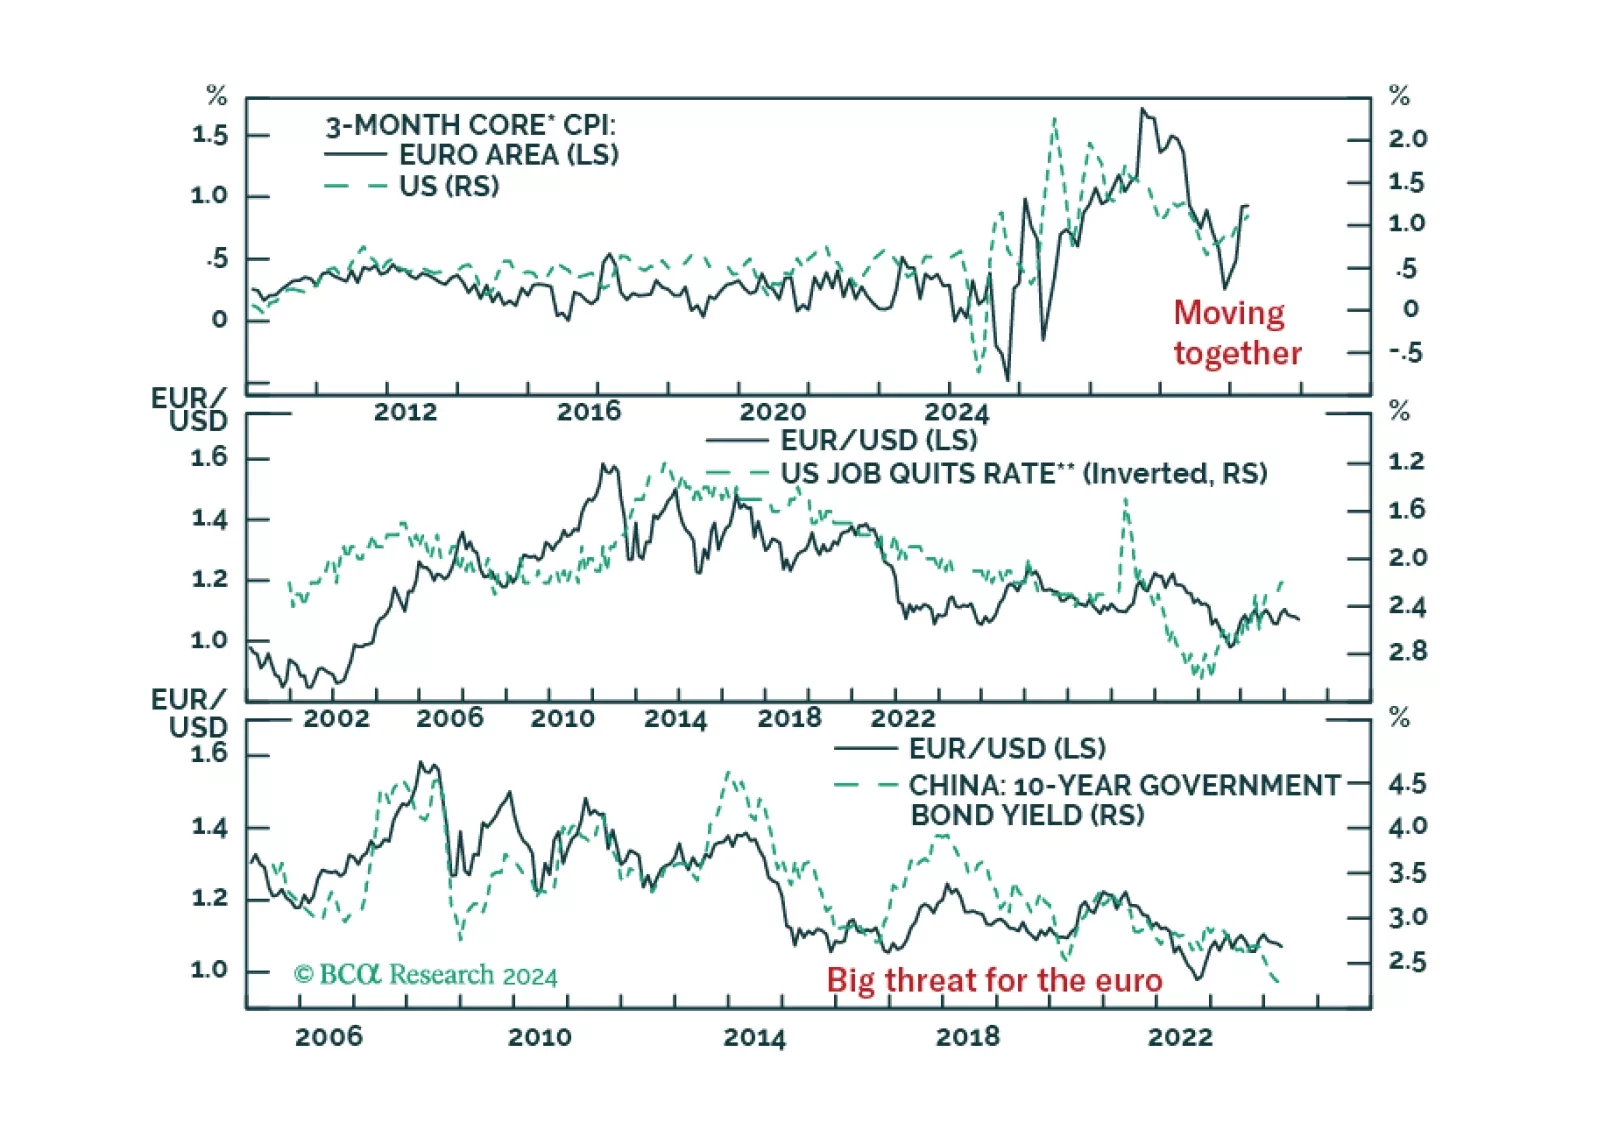
EUR/USD collapsed in the wake of last week’s hotter-than-expected US CPI report. Is this pessimism warranted and will the euro’s trading range that has prevailed since 2023 breakdown?
German industrial production growth accelerated from an upwardly revised 1.3% m/m to 2.1% m/m in February, registering the fastest pace in 13 months and largely beating expectations of a slowdown. A 7.9% m/m increase in the construction sector was the top…

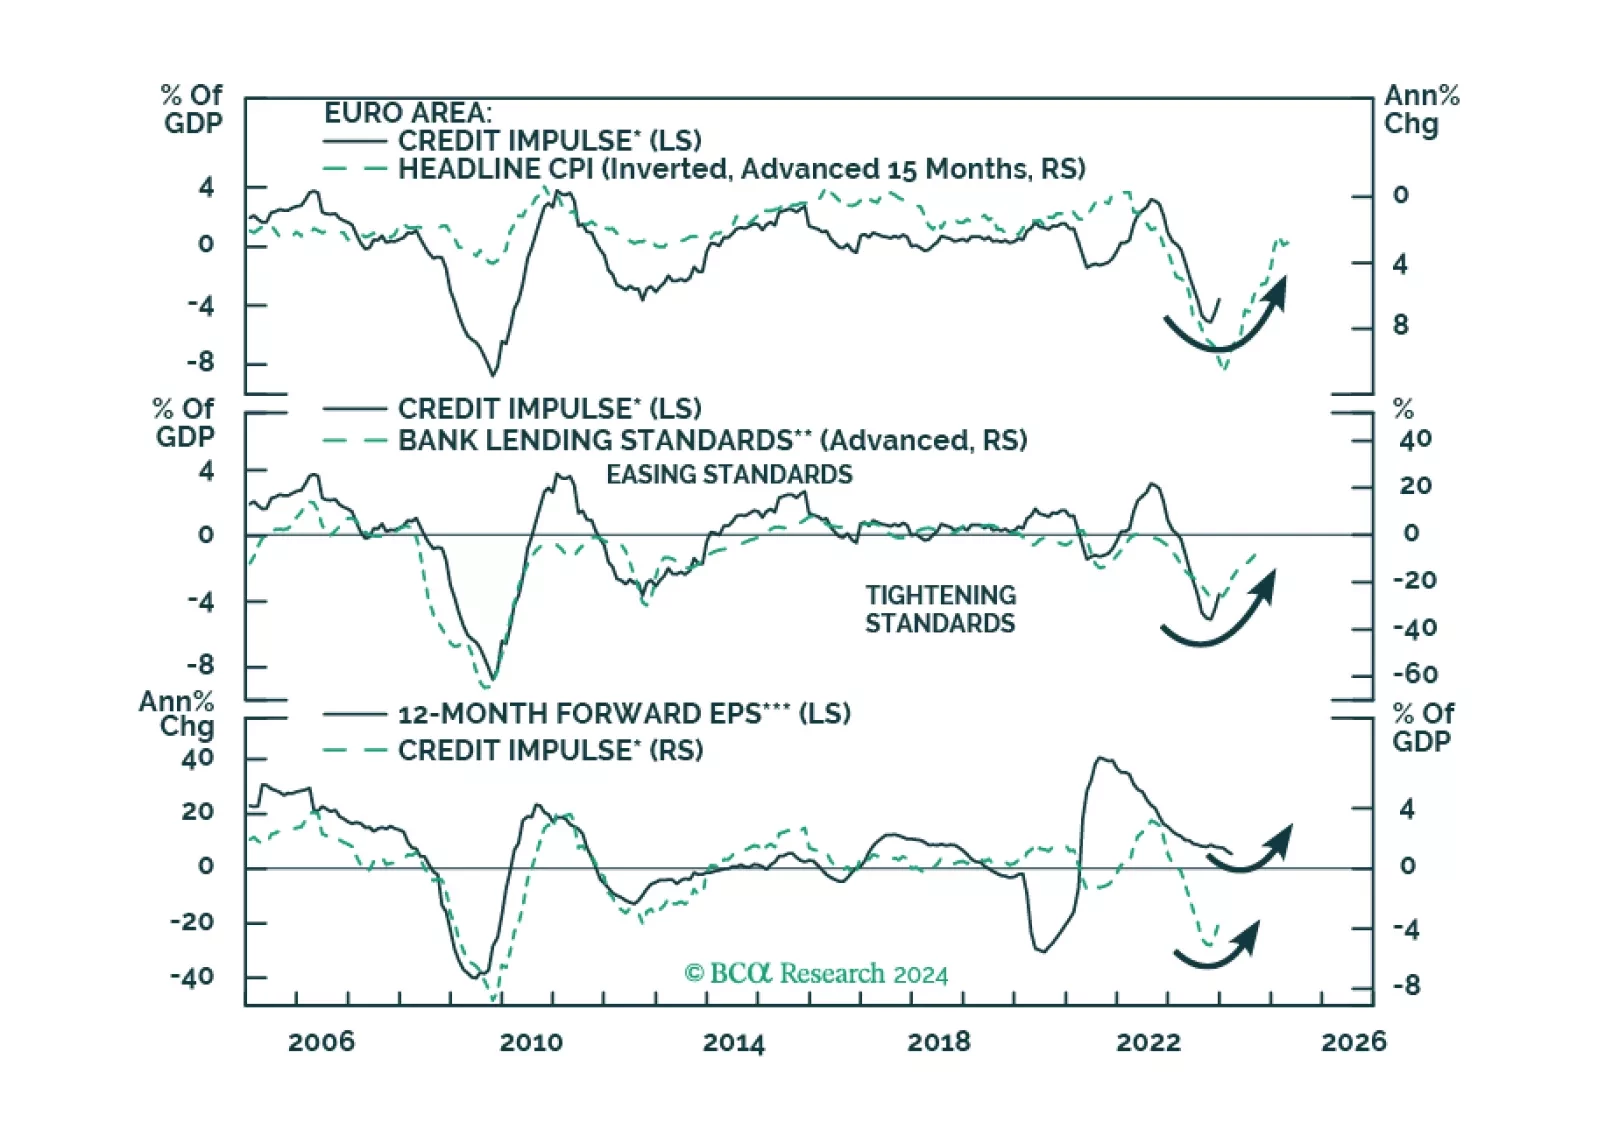
Europe credit flows are stabilizing, hence a major drag on the region’s growth will dissipate. What does this development imply for European equities?