Insights
Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
Report
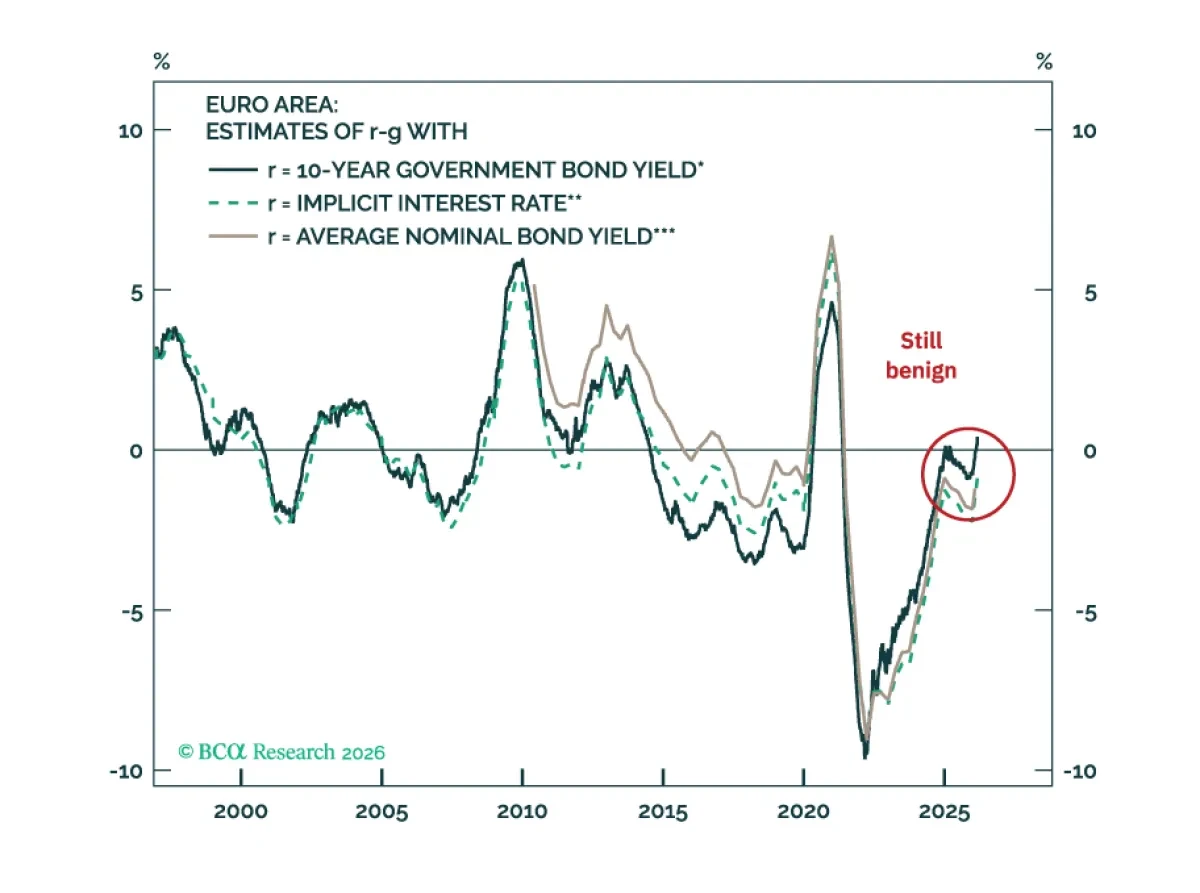
Europe’s fiscal debate has resurfaced as interest rates normalize and new spending pressures emerge. Yet alarmism is misplaced. Aggregate debt levels are high but broadly stable, servicing costs remain historically low, and r–g dynamics are broadly benign. Fiscal space matters less as the ECB and EU...
Read more
Report
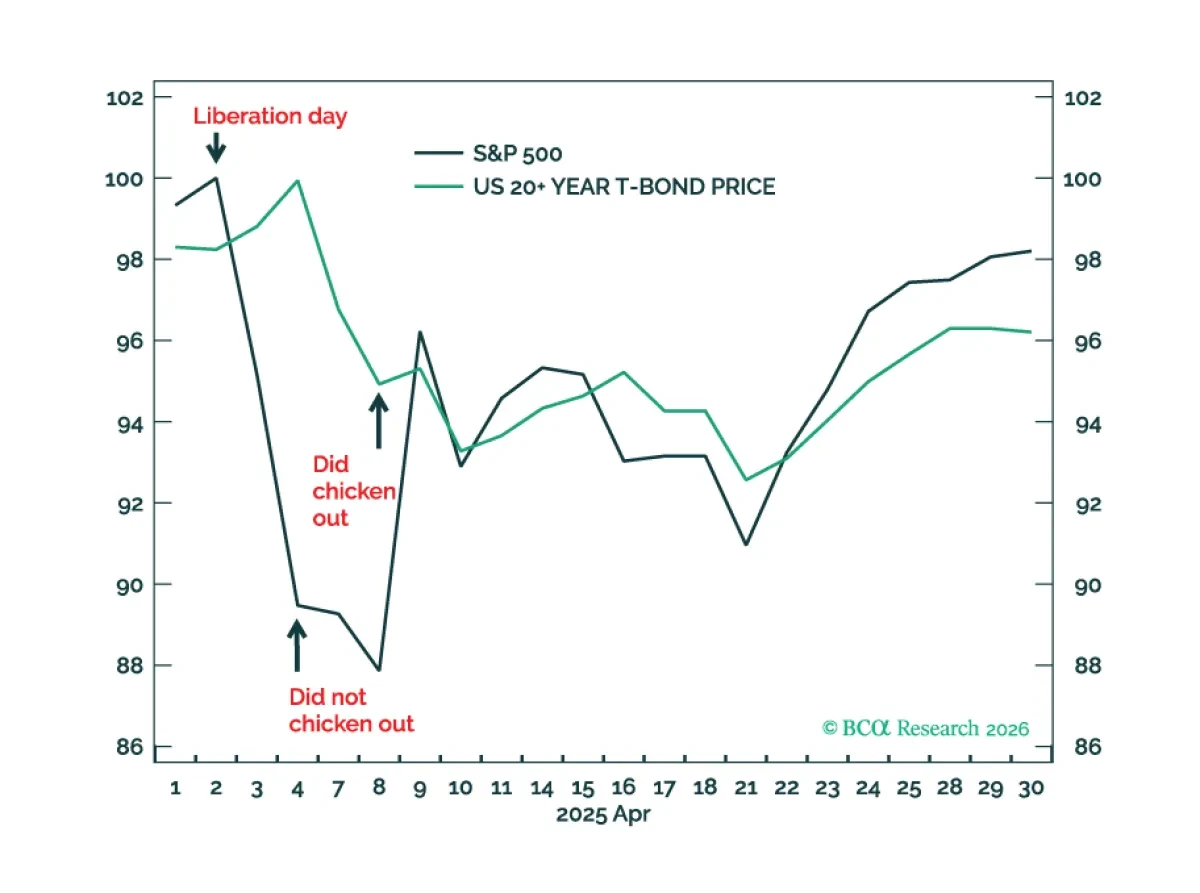
Iran doesn’t need to sink a single US warship; it could inflict much more damage by sinking the US stock and bond markets by disrupting shipping, trade, and oil tankers with decentralised low-tech drone warfare. We discuss why it is not the direct pain of higher oil prices, but the knock-on repercus...
Read more
Report
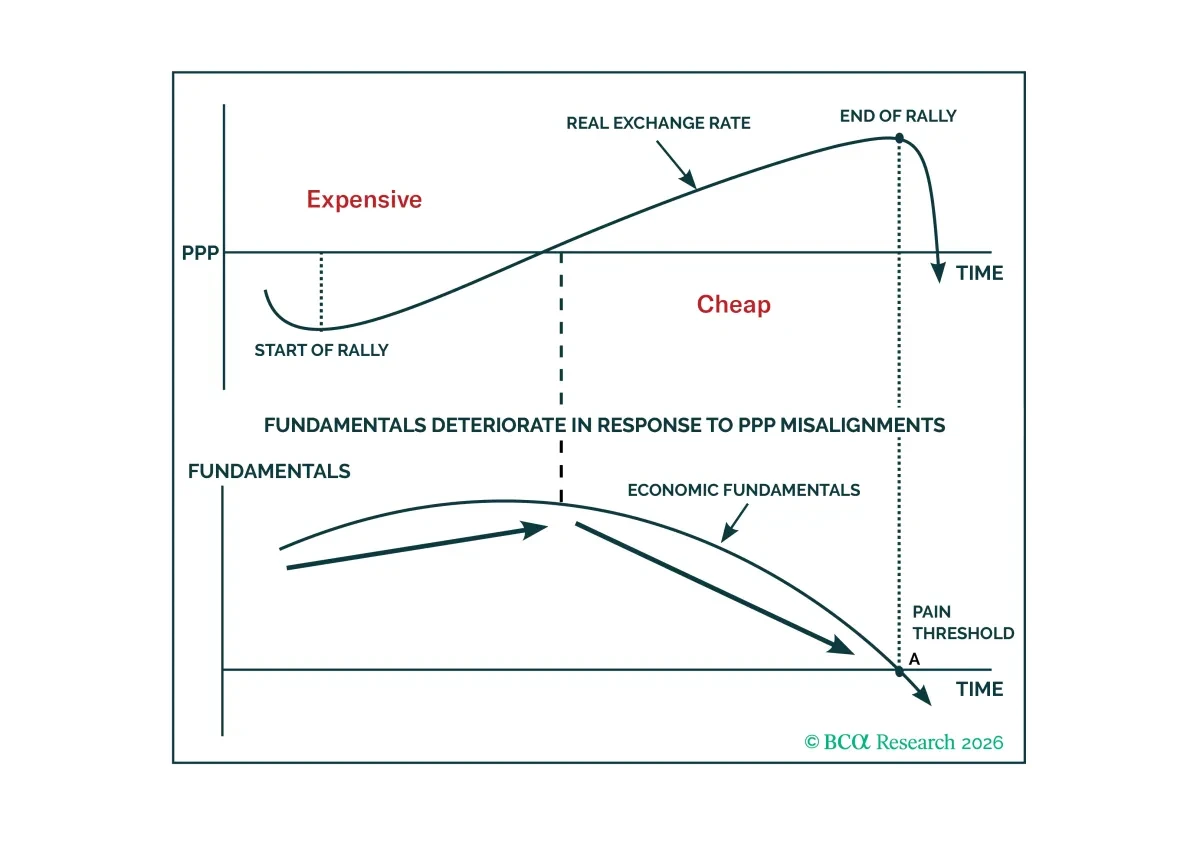
FX often looks random because no single model dominates across regimes. We lay out our long-term framework anchored in valuation, productivity, external balances, and the fiscal-monetary mix to identify when currencies are likely to mean-revert and where the long-run risk-reward is asymmetric....
Read more
Report
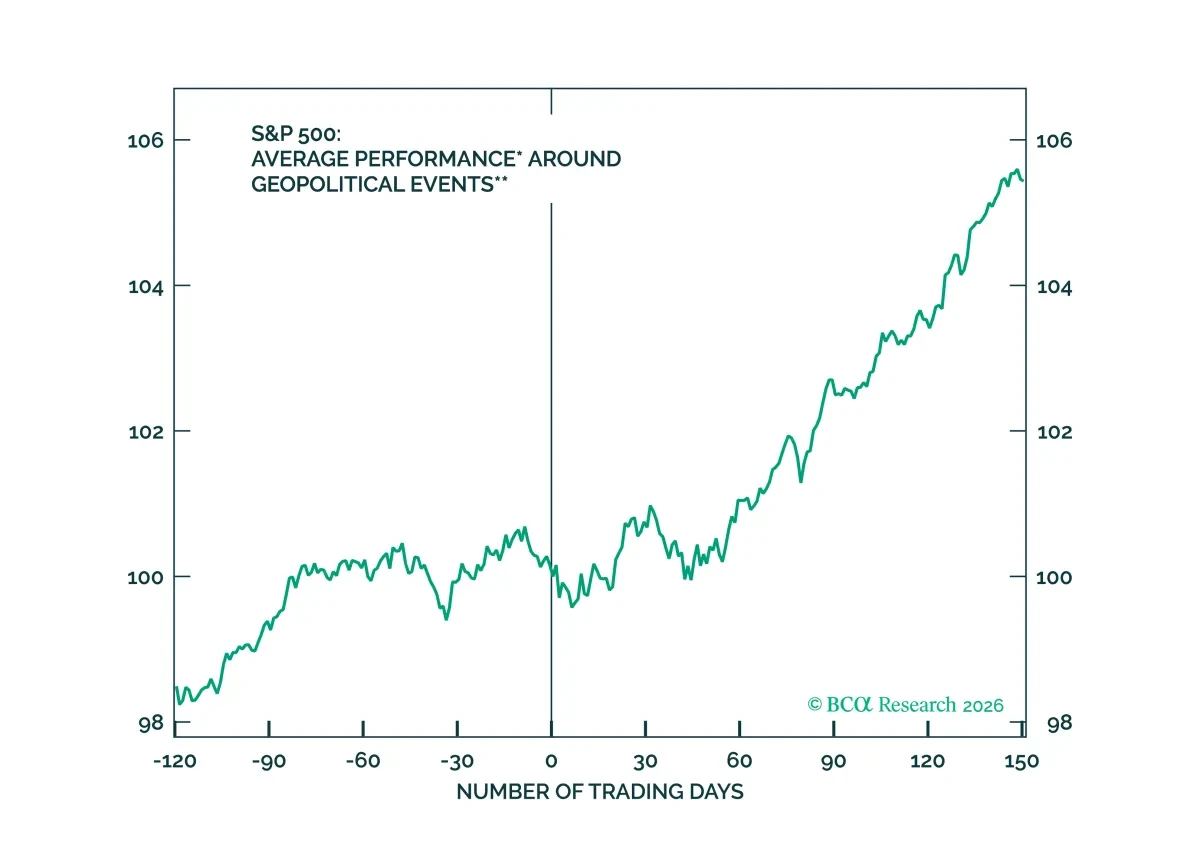
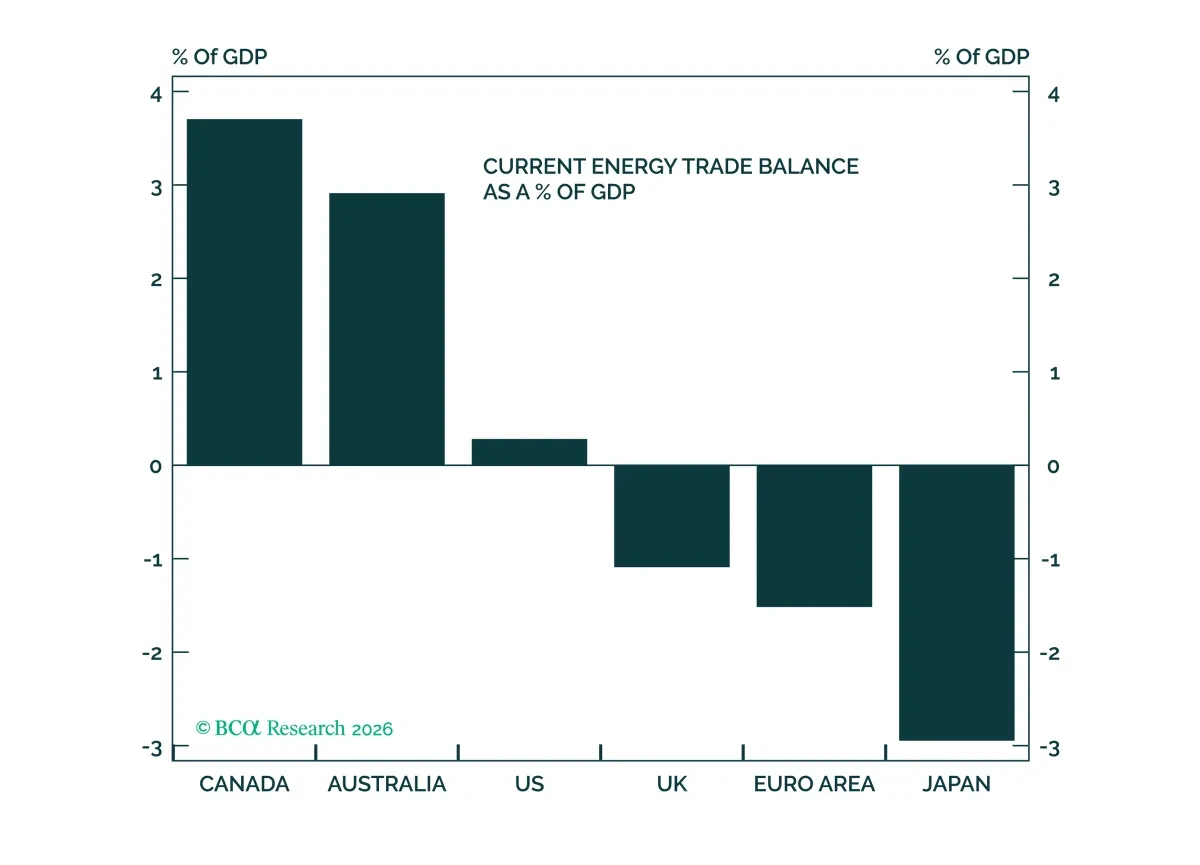
A key risk to our view has materialized. Our base case remains constructive, but risks have increased. Upgrade Tail Risk Strategies from overweight to max overweight. Upgrade Canadian equities and the Canadian dollar to overweight. Upgrade Australian equities and the Australian dollar to overweight....
Read more
Report
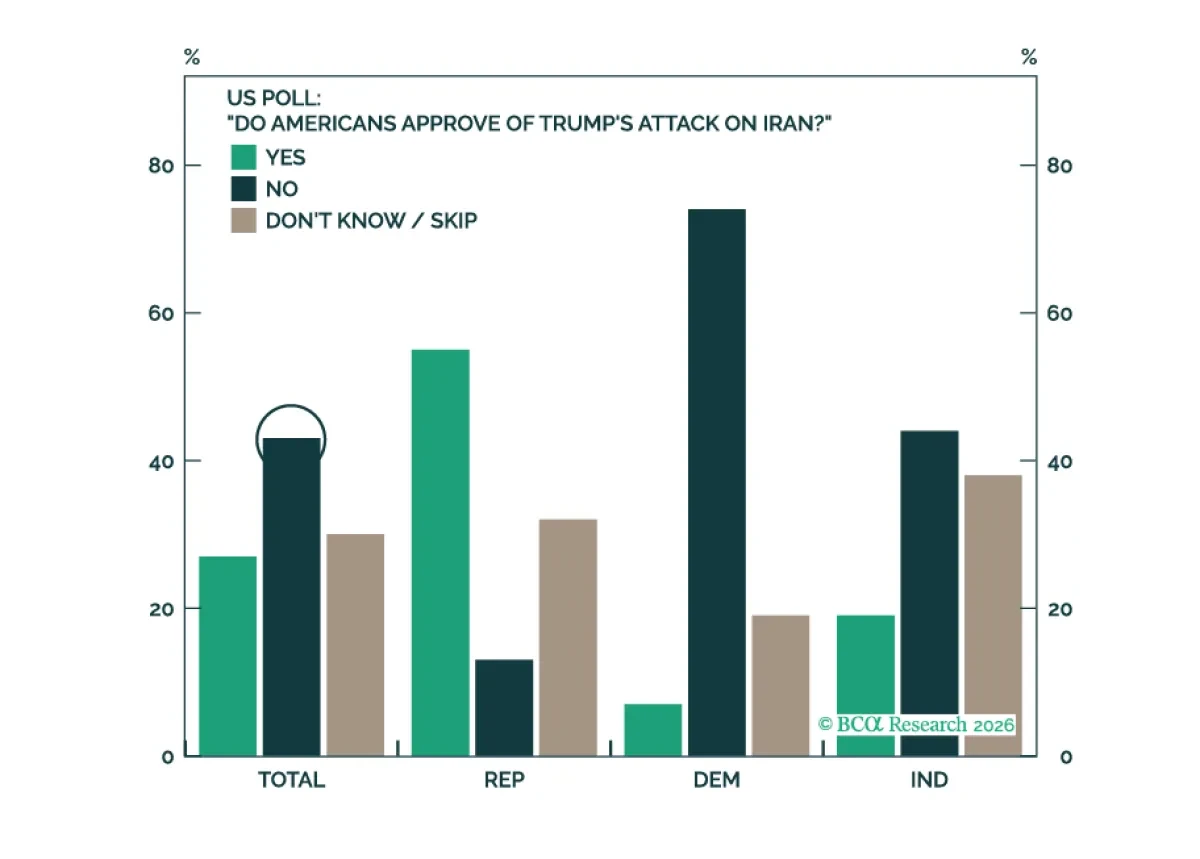
Clients are universally asking us when we expect President Trump to activate the legendary “Trump Put.” We believe that the S&P 500 would have to correct by more than 10% to practically guarantee a put. We are open minded that it could occur before; it could also occur later. But a double-digit ...
Read more
Report
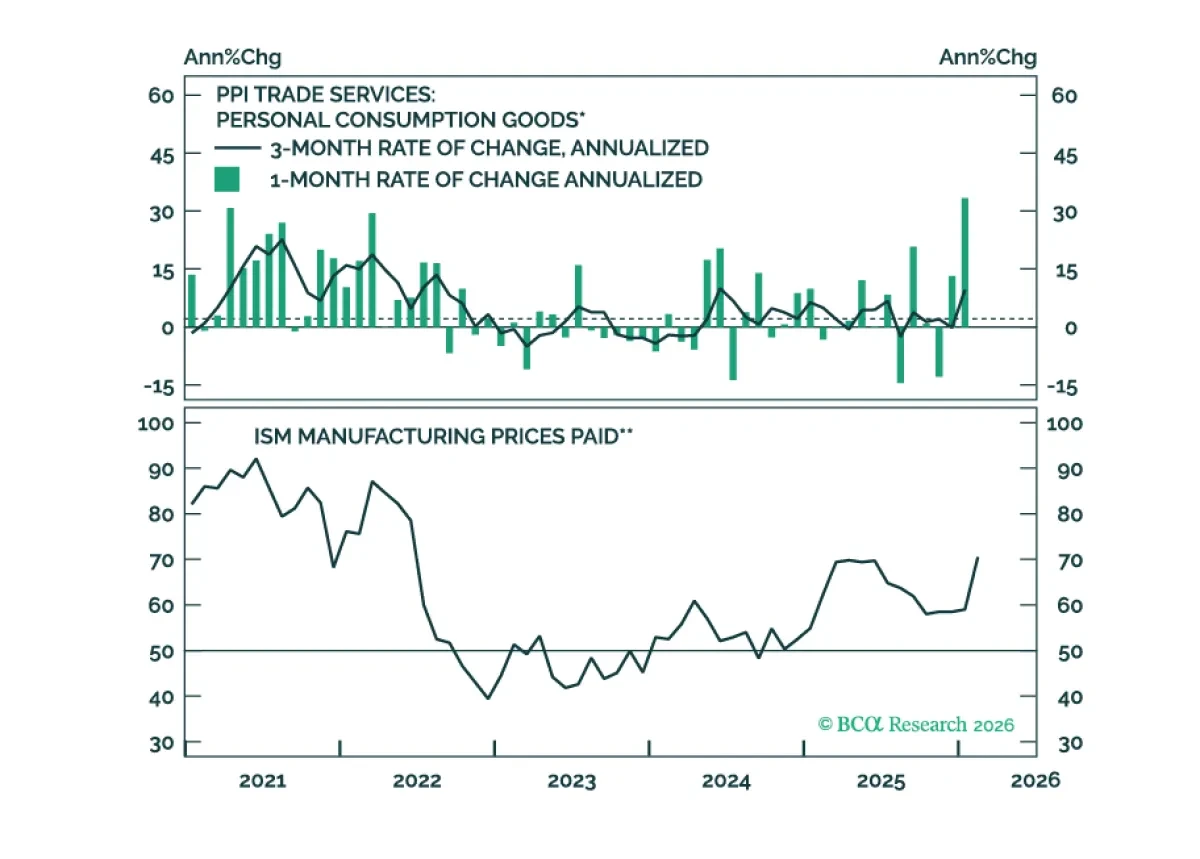
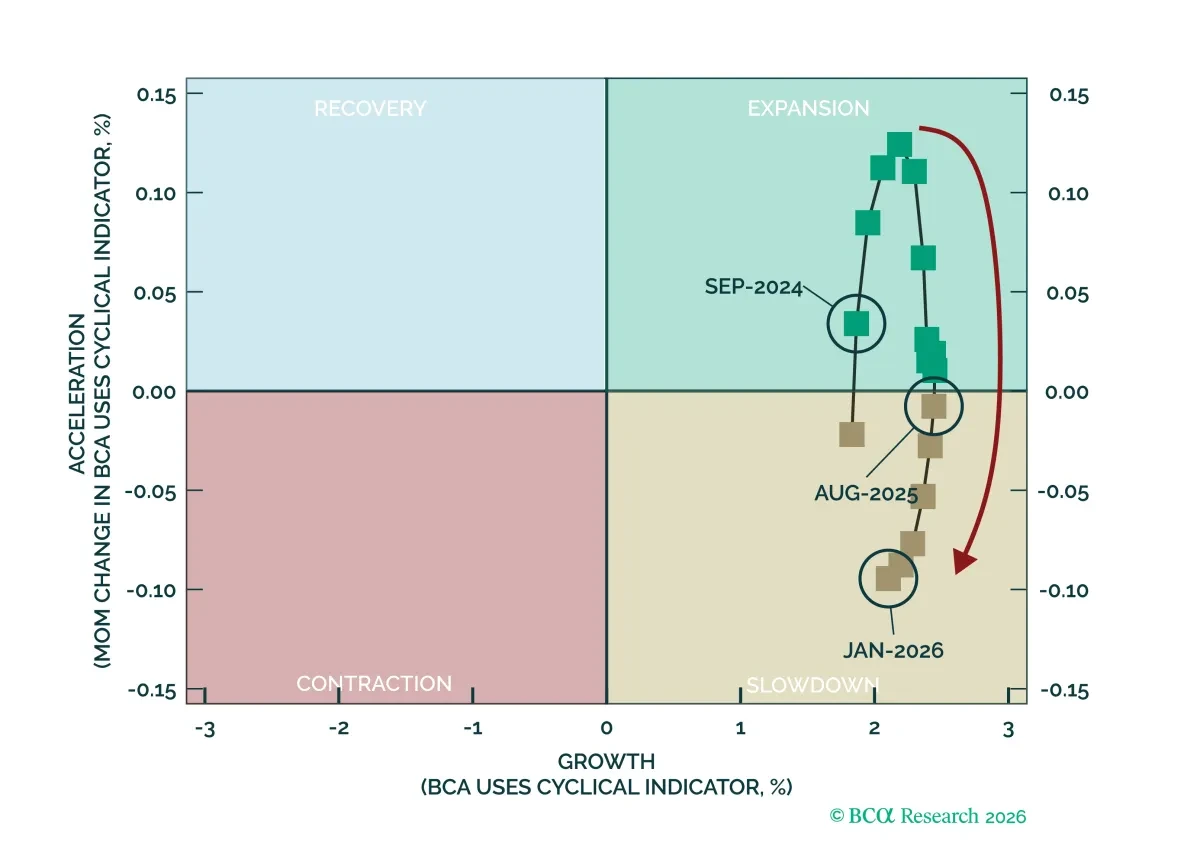
This screener report builds on the US Equity Strategy and Equity Analyzer collaboration published on 23 February 2026, where we introduced our latest framework for assessing the US business cycle. Here, we apply the framework to our screener to identify how bottom-up equity positioning should adapt ...
Read more