Latest from BCA Research
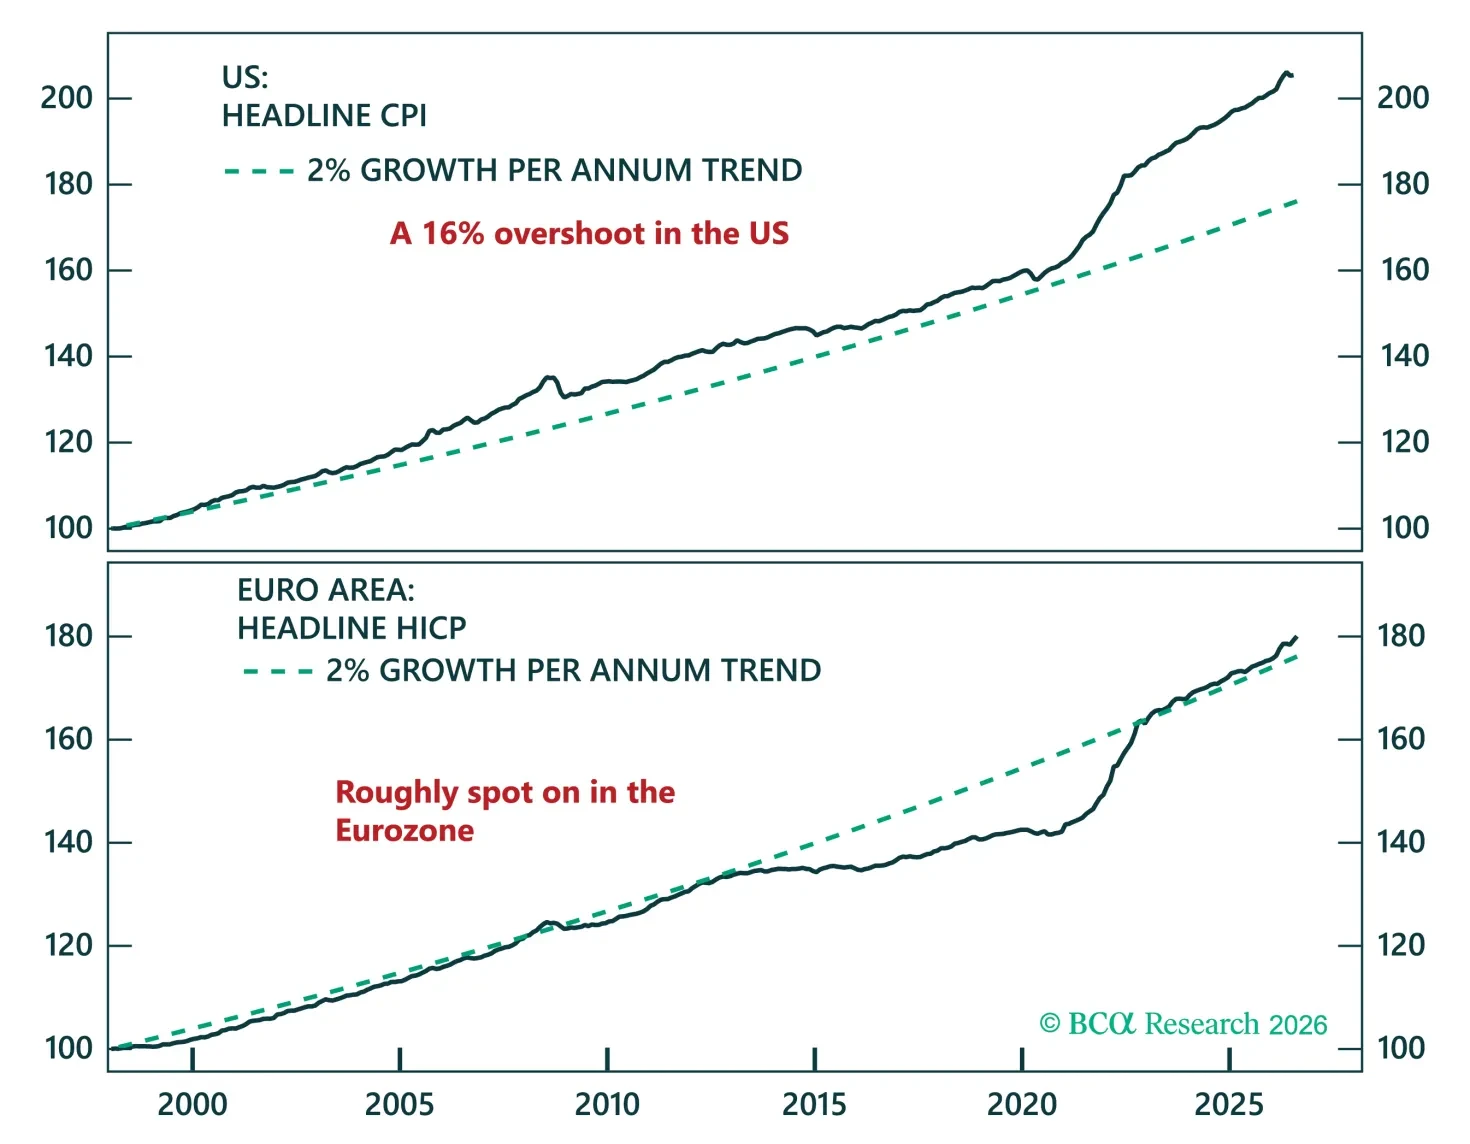
The ECB is winning, and almost nobody's pricing it in. A flatter Phillips curve, a shrinking term premium, a euro built to shrug off France, credibility is the trade.
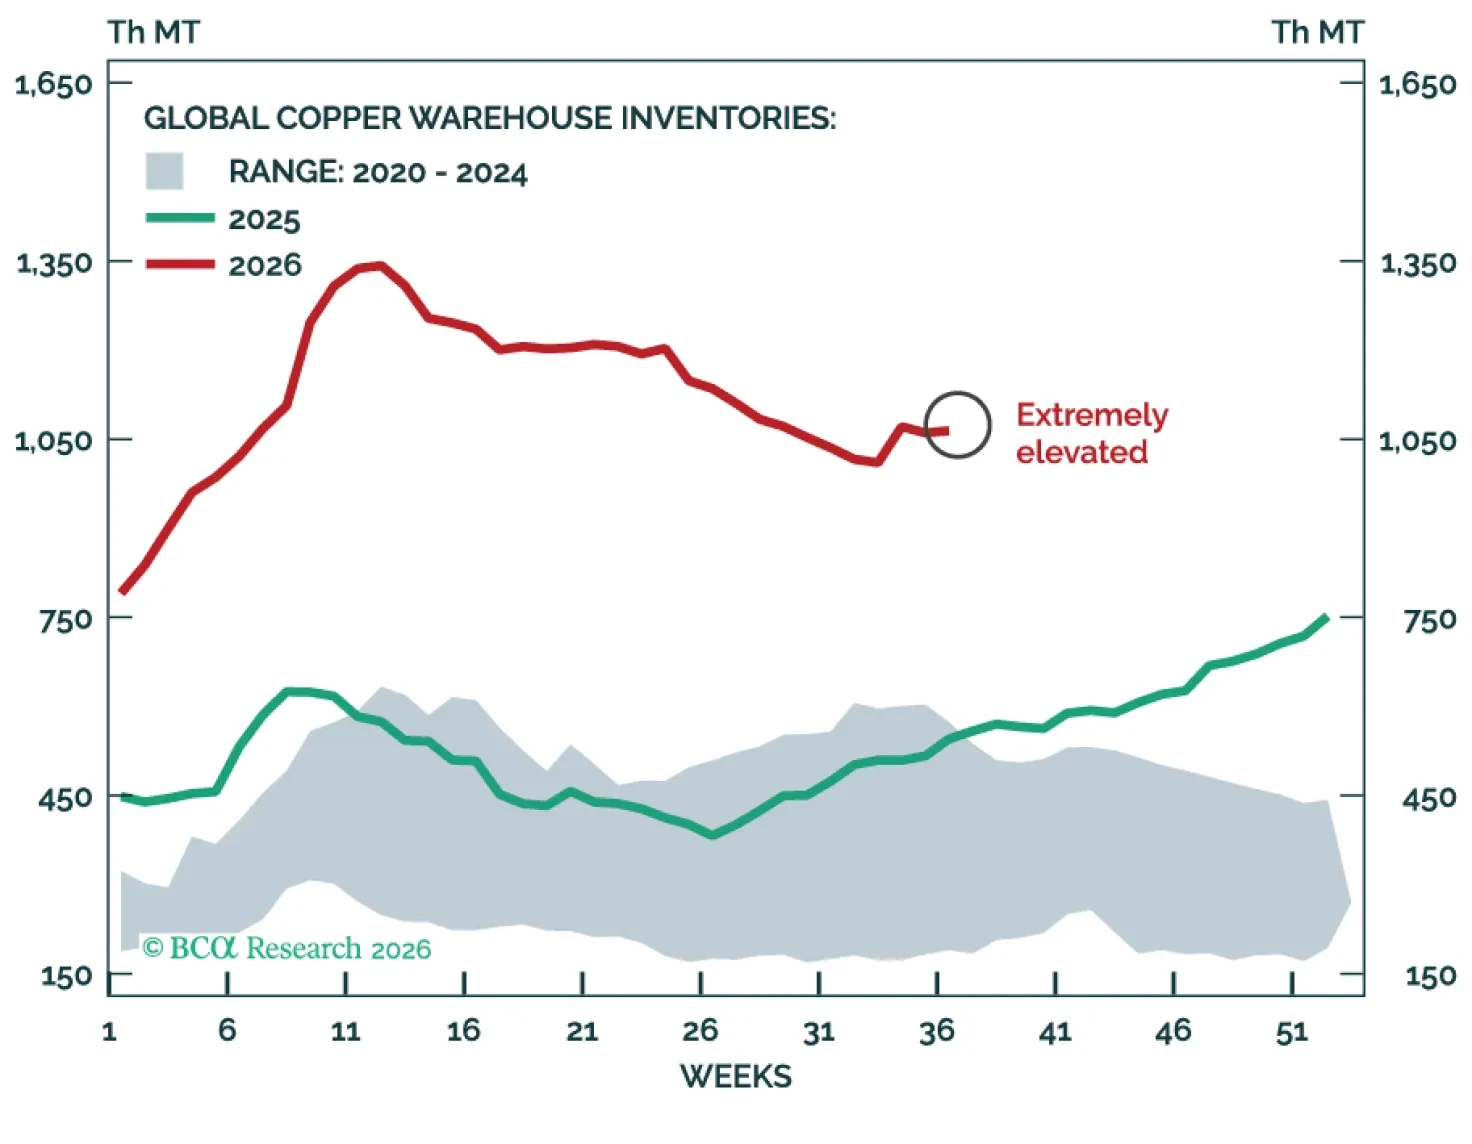
Thursday's sharp pullback in the COMEX copper price from an all-time high underscores a key risk to the red metal's resilience. An eventual resolution of US copper tariff uncertainty would likely trigger a price relapse. That drawdown, however, would offer an attractive opportunity to increase structural exposure to the metal.
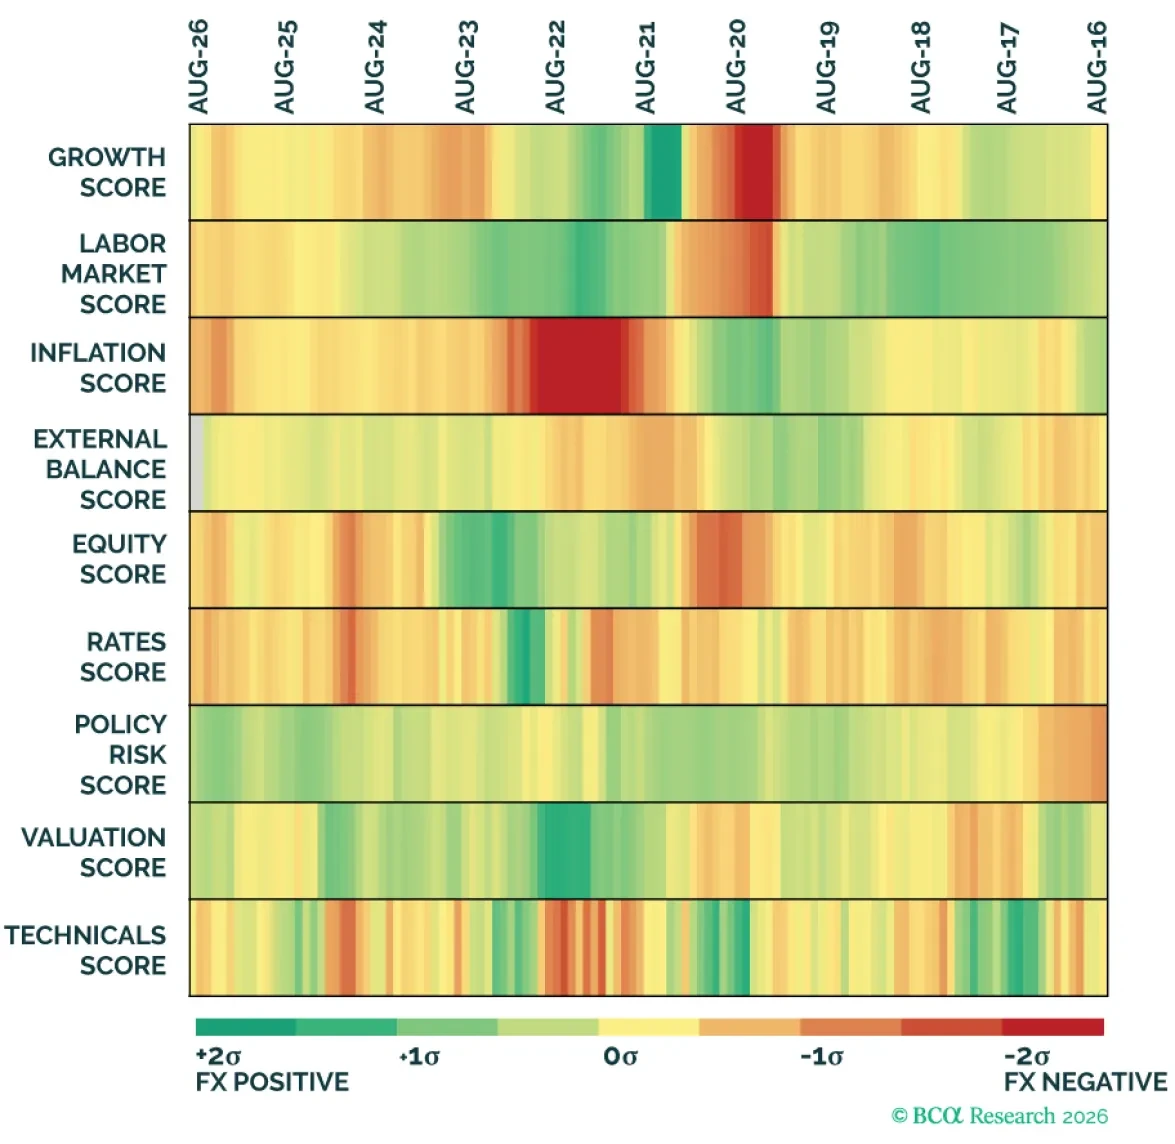
Foreign exchange markets are shaped by a wide range of macro influences. The sheer breadth of relevant information makes systematically assessing where a currency stands at any point in time a challenging analytical task. We introduce an FX scorecard that condenses the full range of data into nine thematic scores, providing a clear visual snapshot of a currency's position and how it's evolving.
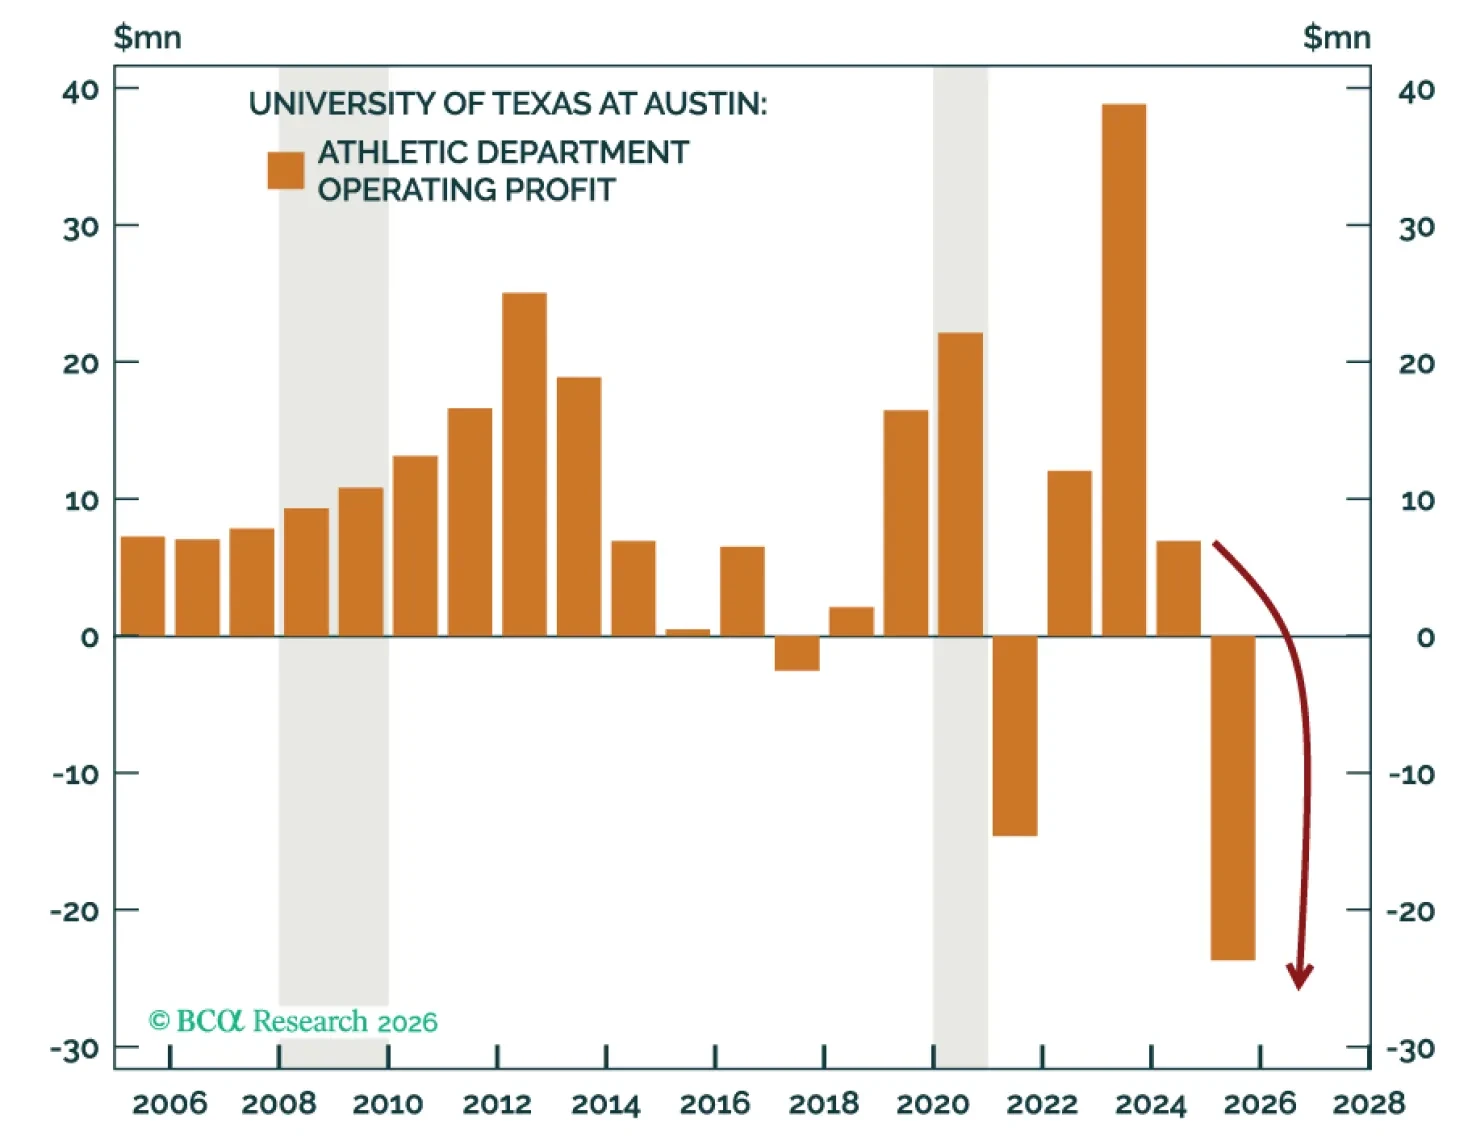
It is that time of year again for our annual Private Equity & Sports report. This year, we examine private capital's entry into college sports. Athletic departments generate significant revenue, but margins are under pressure. Colleges still hold untapped assets that private partners will help monetize.
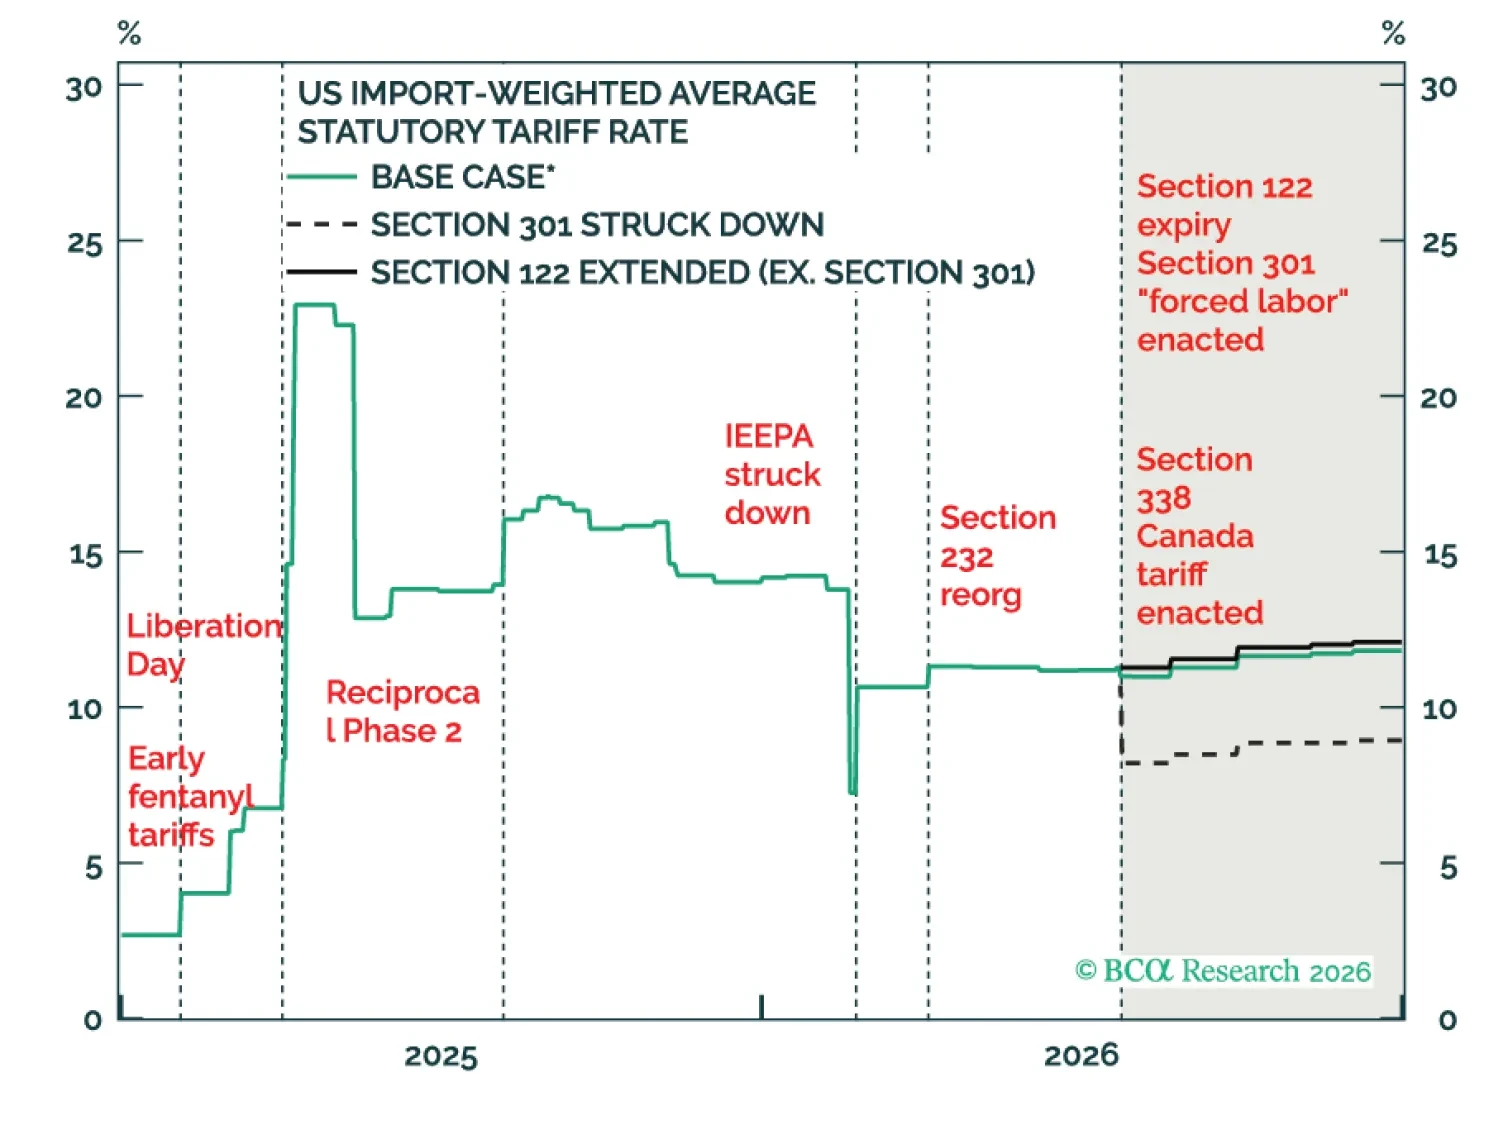
President Trump is raising tariffs again, now through 2027 – and more countries will retaliate this time. While markets can climb over “Liberation Day 2.0,” investors should be wary of today's aggressive policies engendering drastic policy change in 2028.
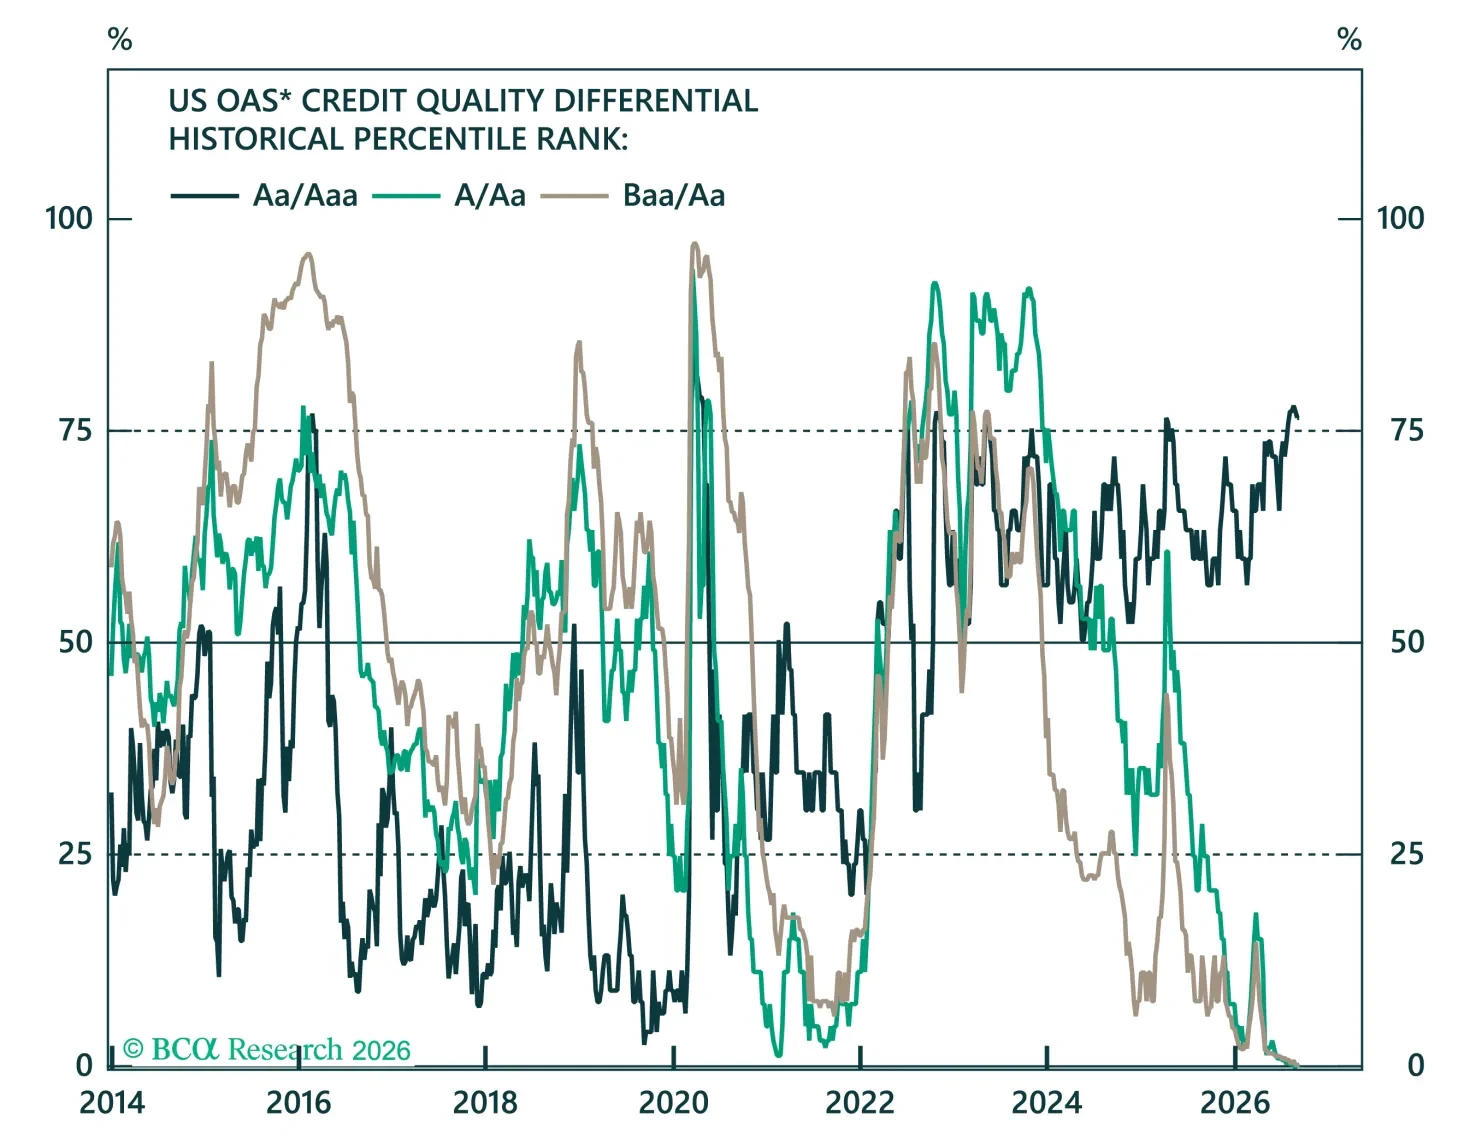
After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
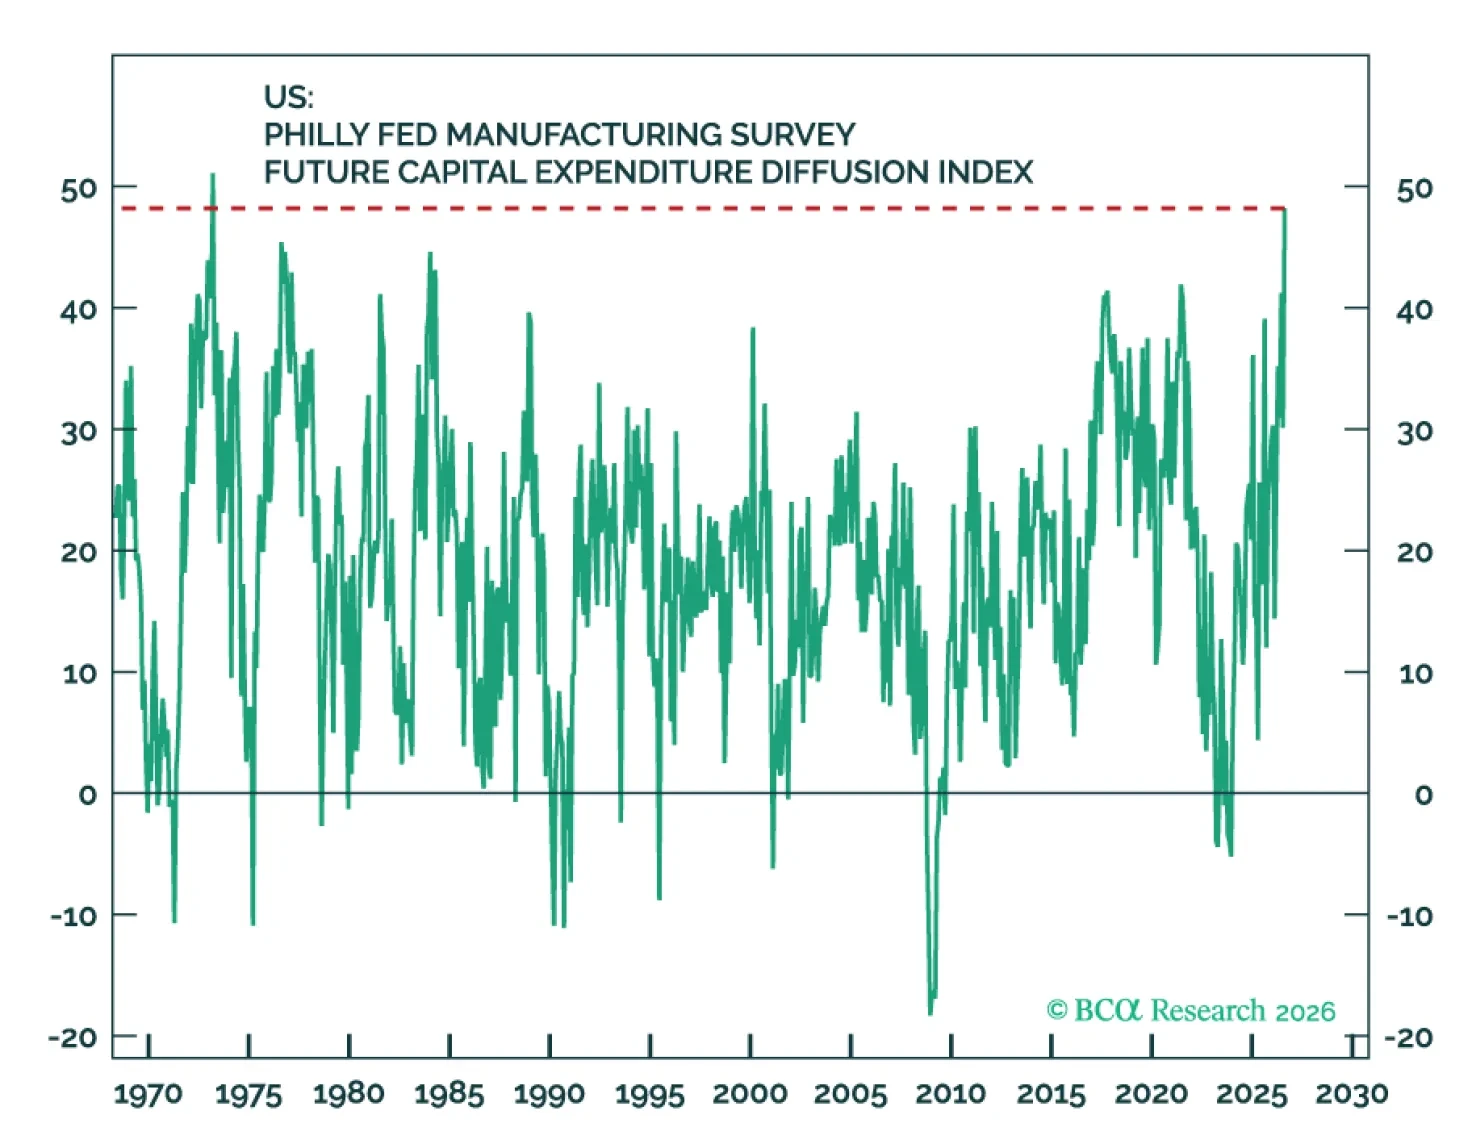
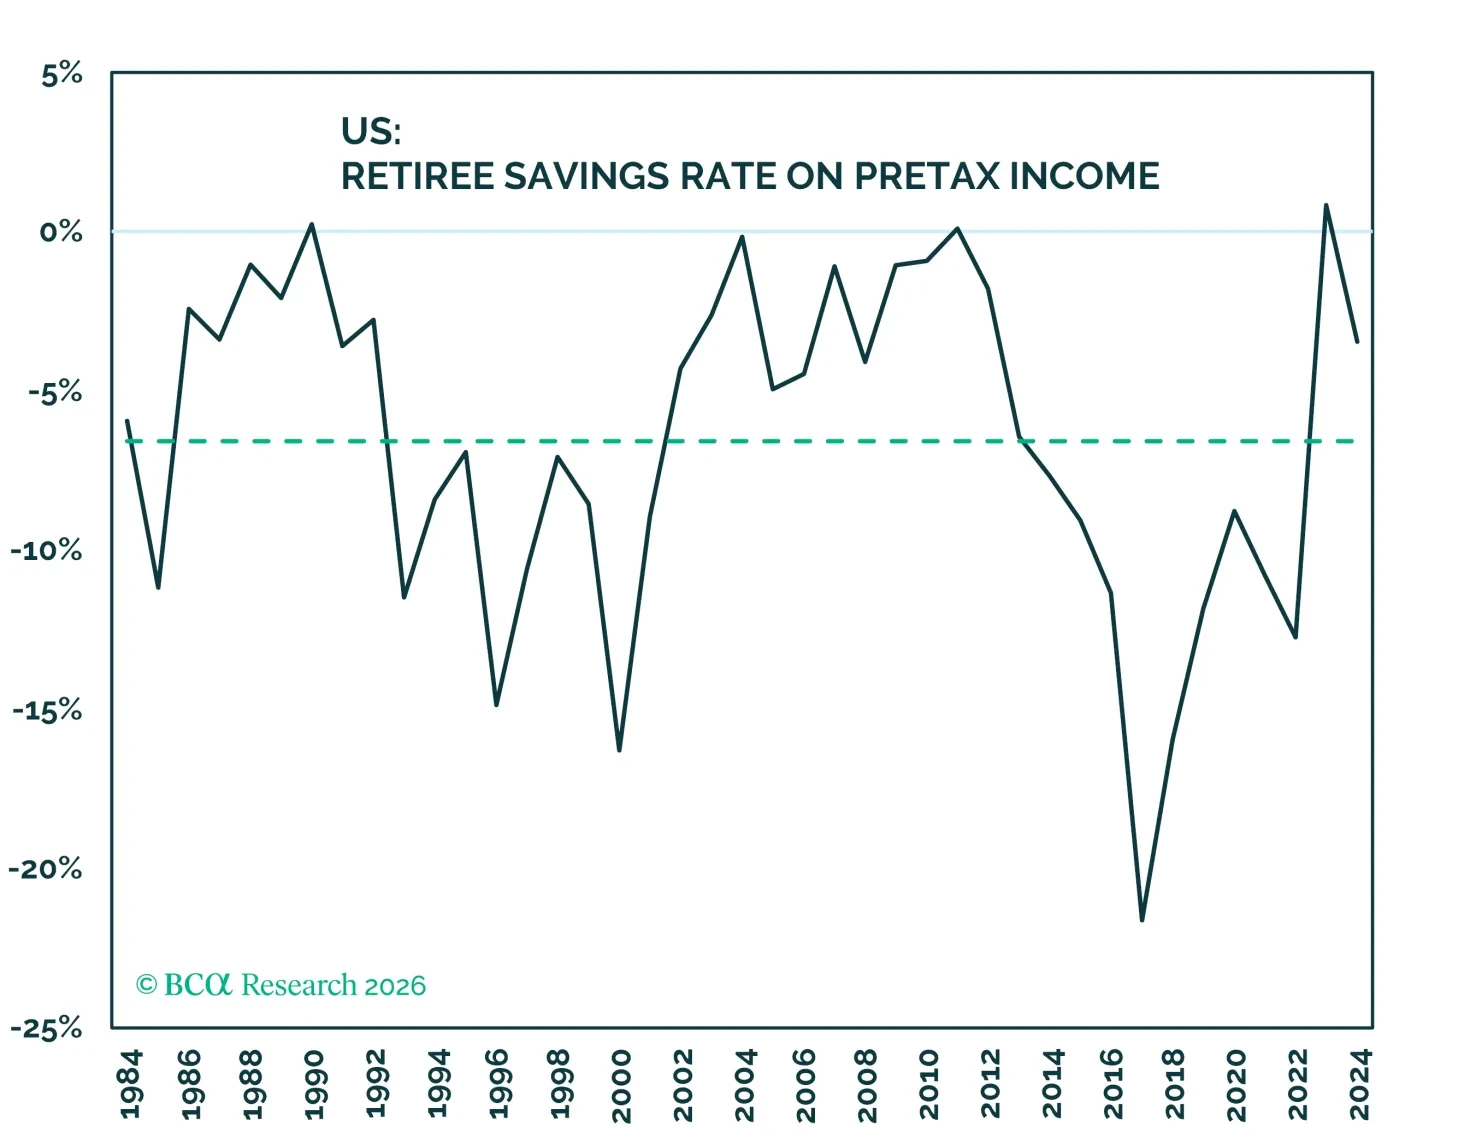
Concerns about the savings rate’s sustainability ease after adjusting for retirements and capital gains. The US economy continues to grow at a pace that is neither too hot nor too cold and investors should remain fully invested in risk assets.
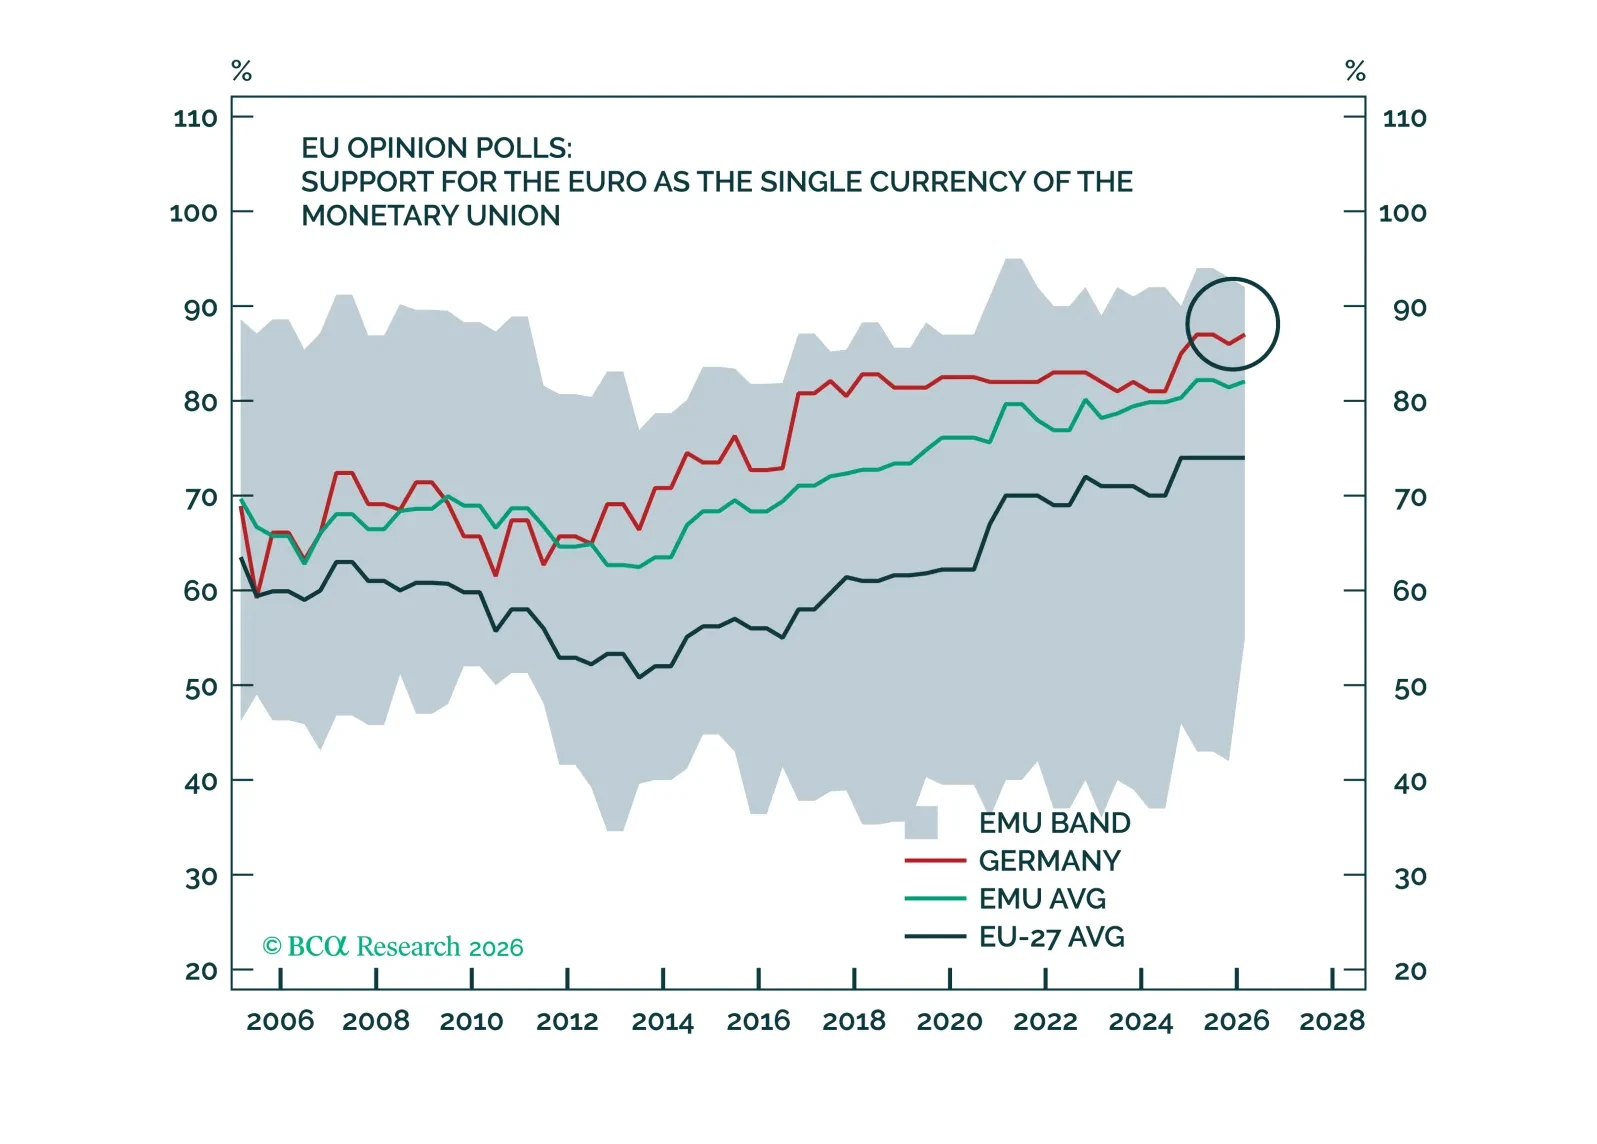
Alternative for Germany’s election win in the state of Saxony-Anhalt is overrated.
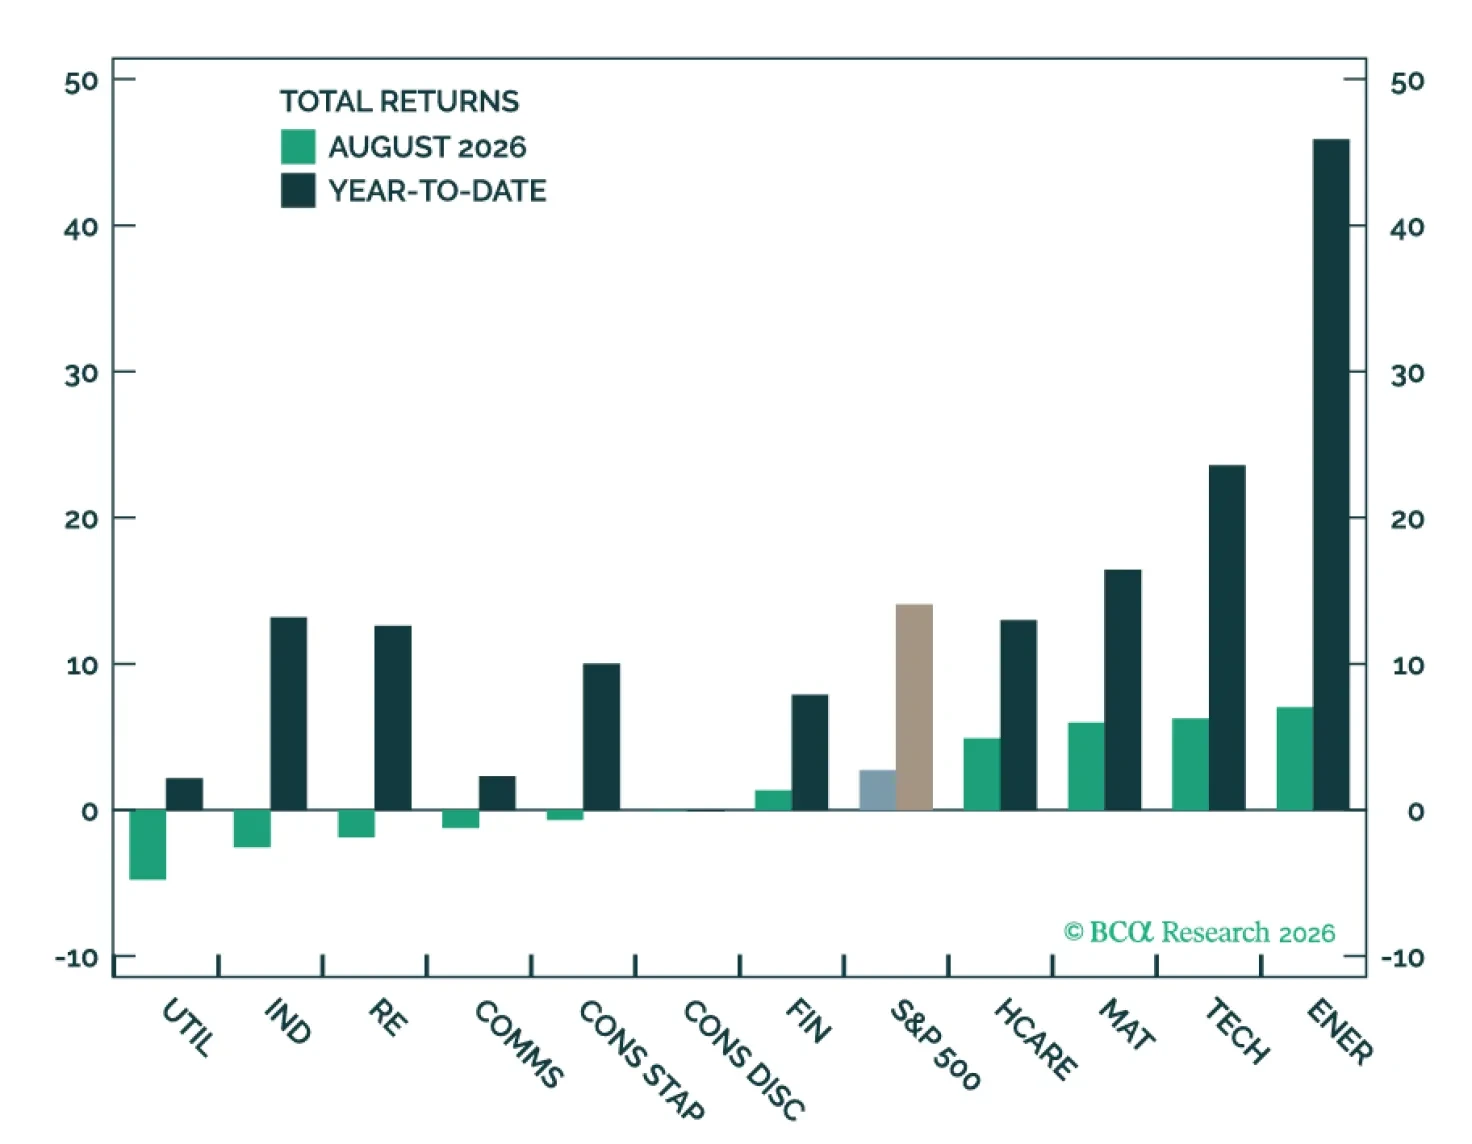
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.