Euro Area
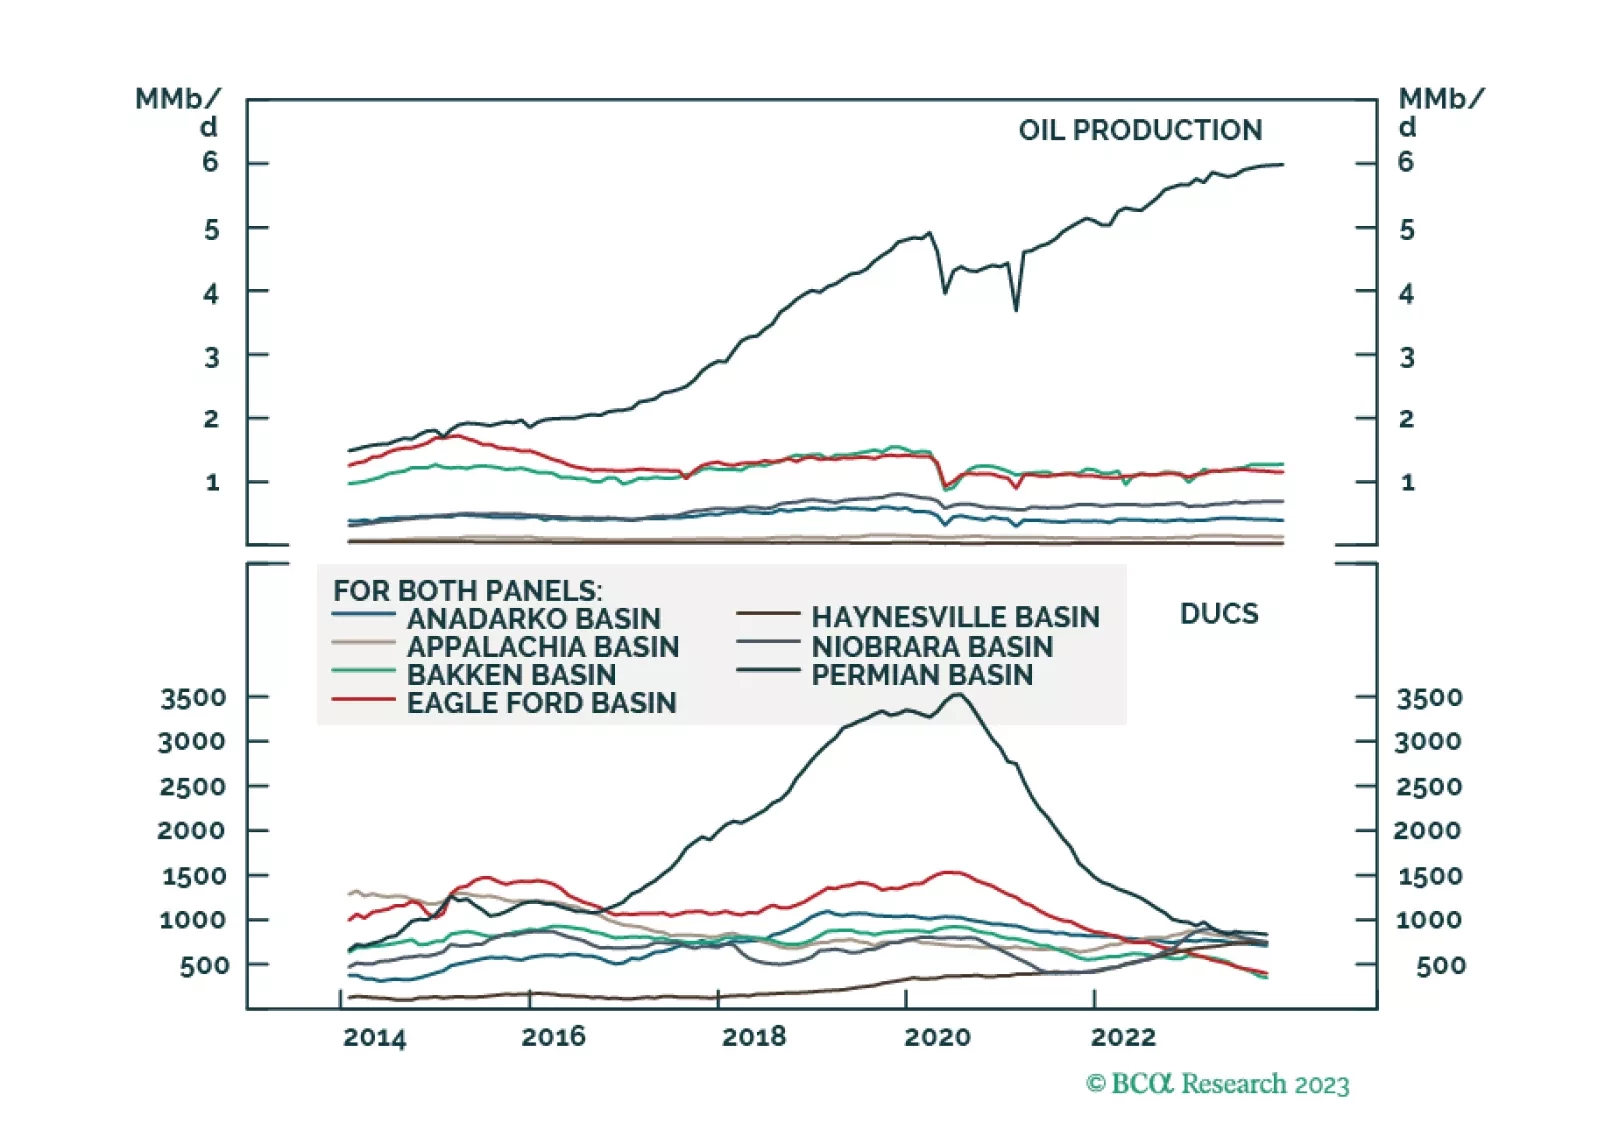
Political economy dominates fundamentals going into 2024, as states prepare for war and de-risk supply chains. Asynchronous global growth will elevate commodity-price volatility. We expect oil to trade above $100/bbl in 2024 and continue to favor equity exposure to oil-and-gas producers. Given weak capex, we also favor metals miners and refiners. We remain long the Gold, the XME and COMT ETFs We were stopped out of our XOP ETF with a 12.5% gain; we will re-establish it at tonight’s close.

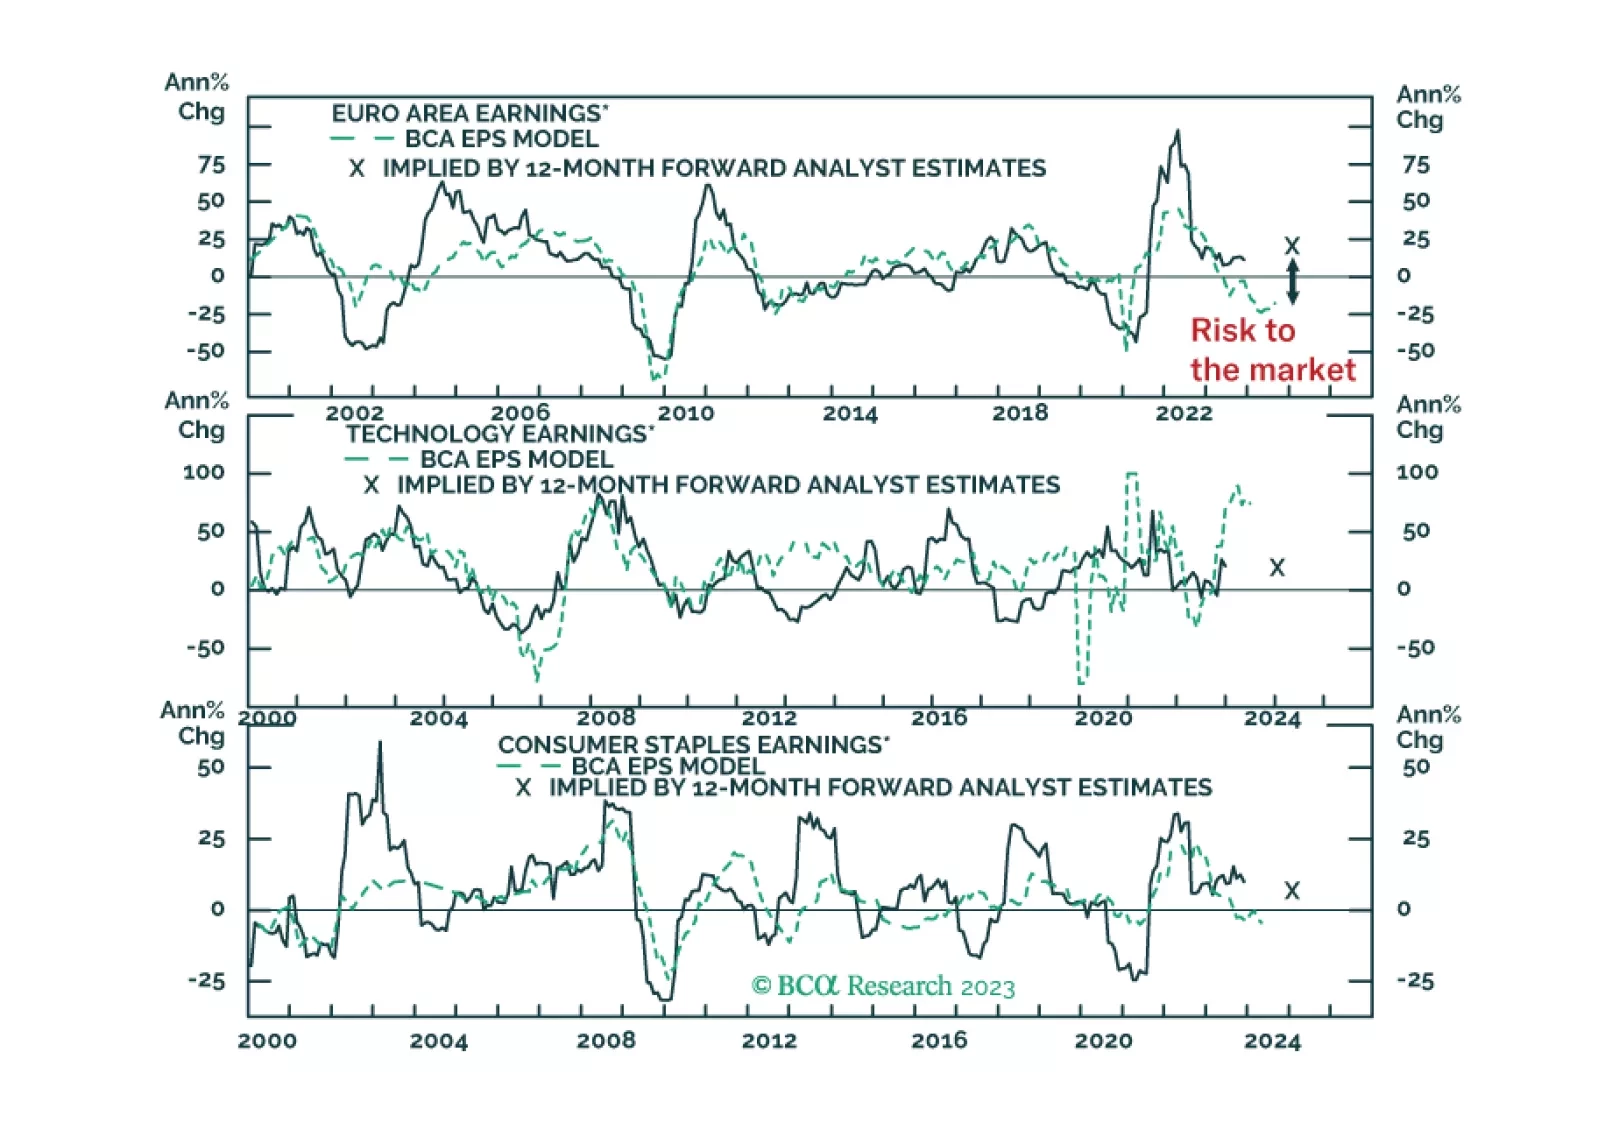
The recent decline in yields has powered European equities higher, however, this rally cannot last if earnings decline meaningfully. With this in mind, are our earnings models flagging risks for stocks next year?
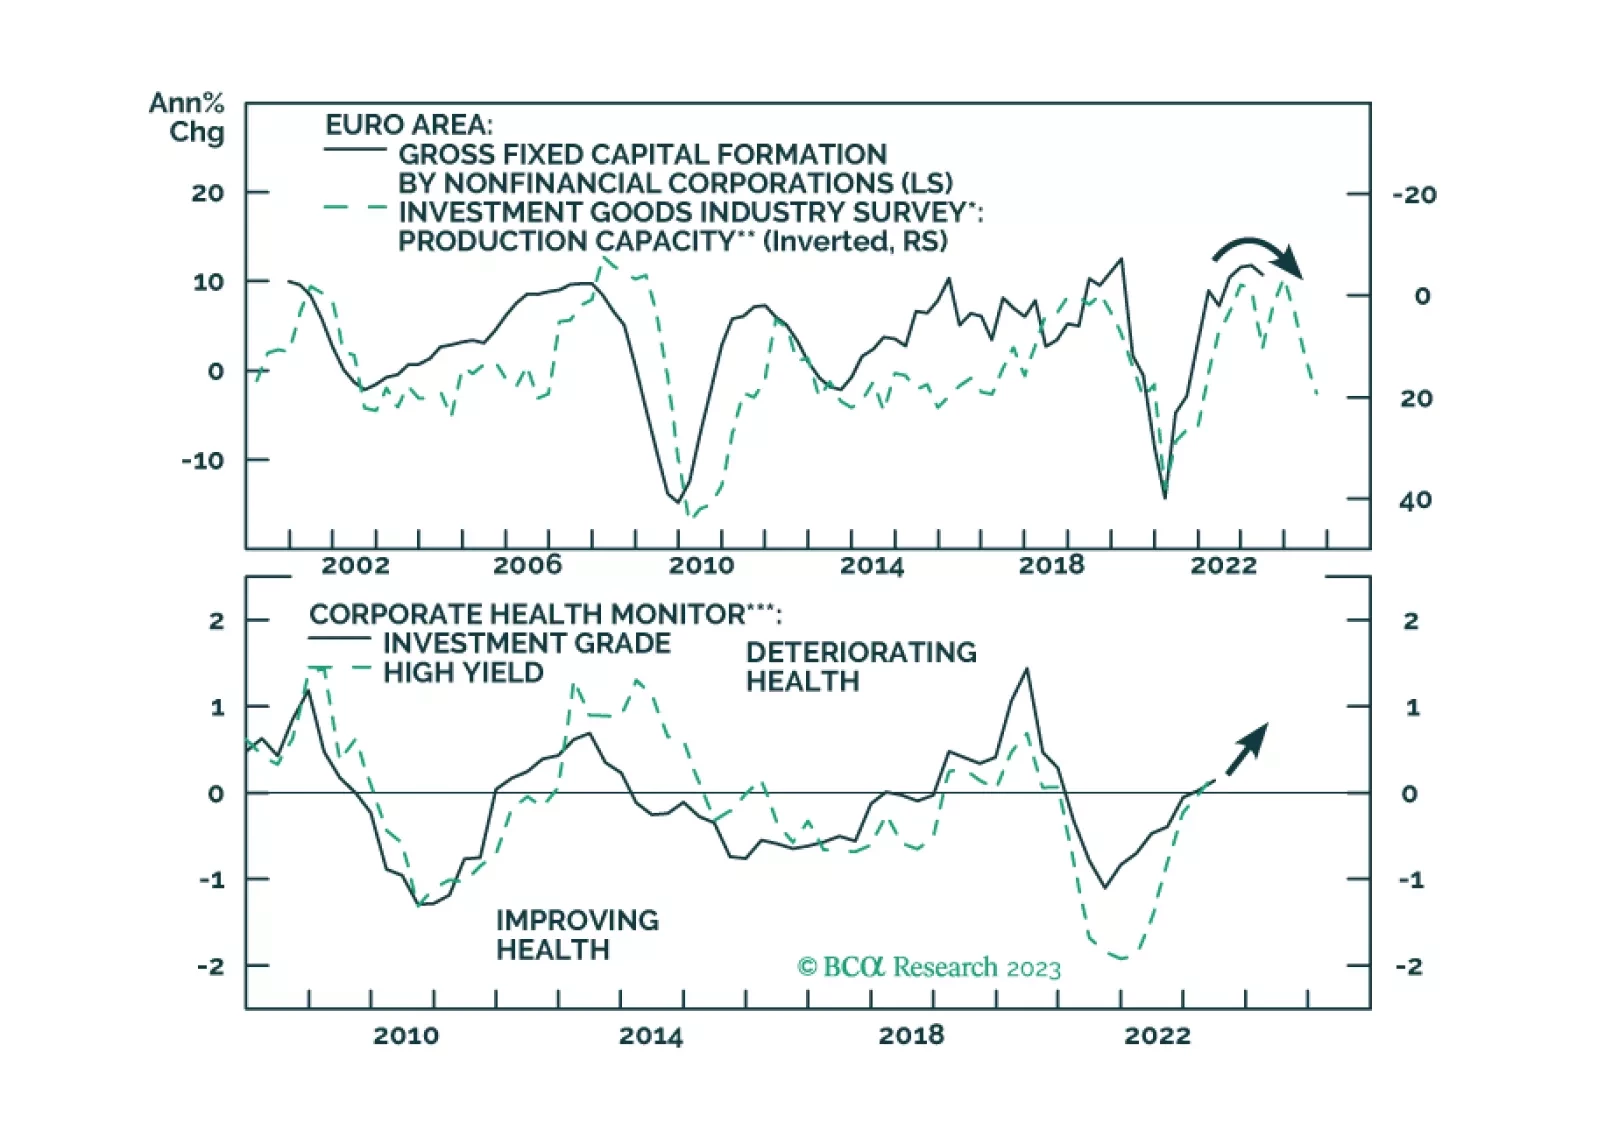
The recent uptick in European economic data will not last beyond the next six months. How will European corporate credit perform in this context?