Insights
Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
Webcast Replay
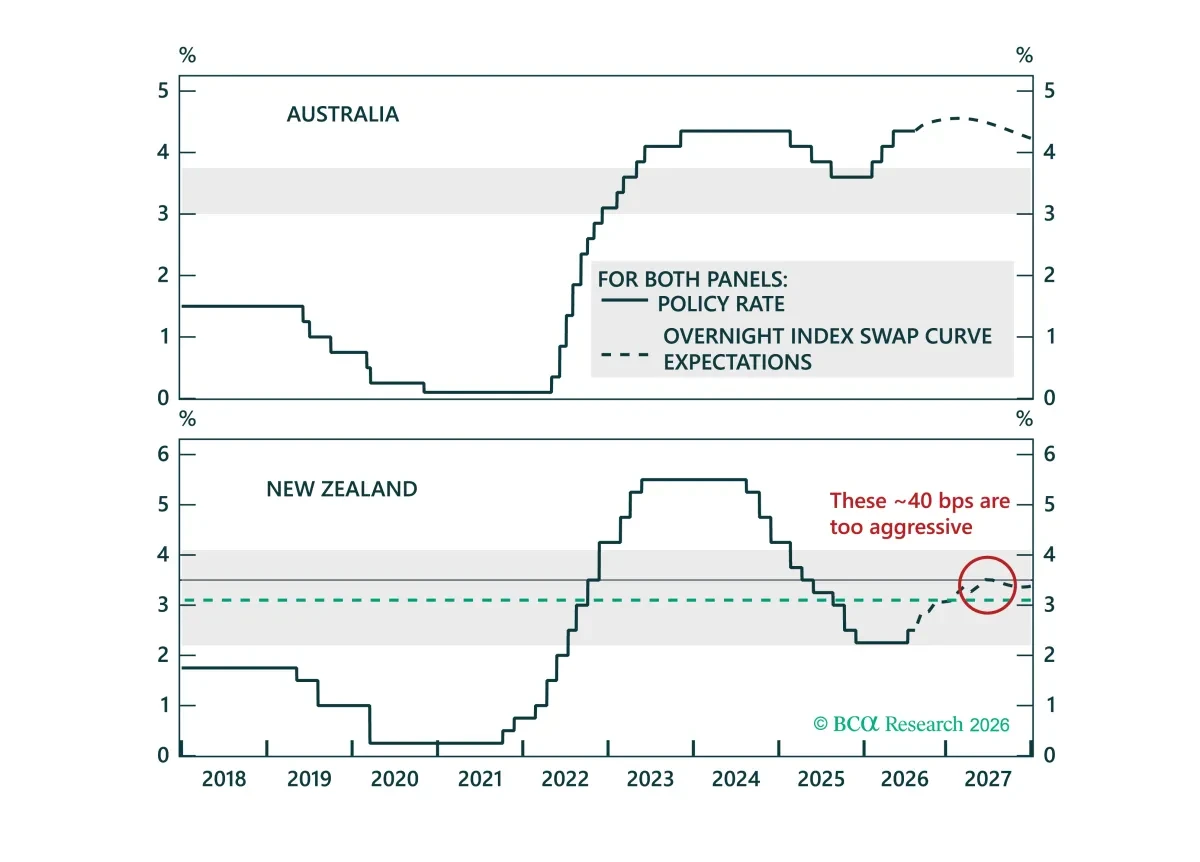
Arthur discussed:
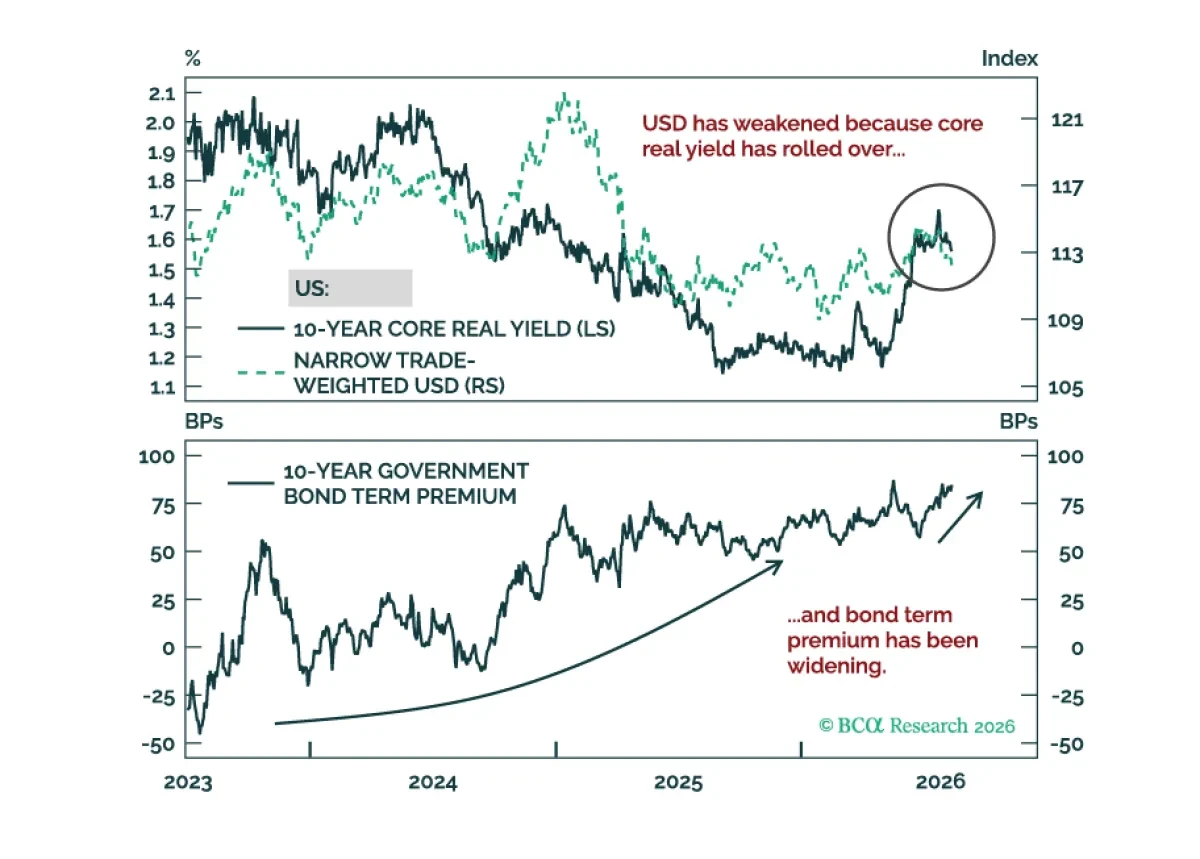
- Global currency markets are on the edge: the US dollar will become pro-cyclical, and the euro will become counter-cyclical.
- This regime shift would upend financial market correlations, and most investment portfolios are not positioned for it.
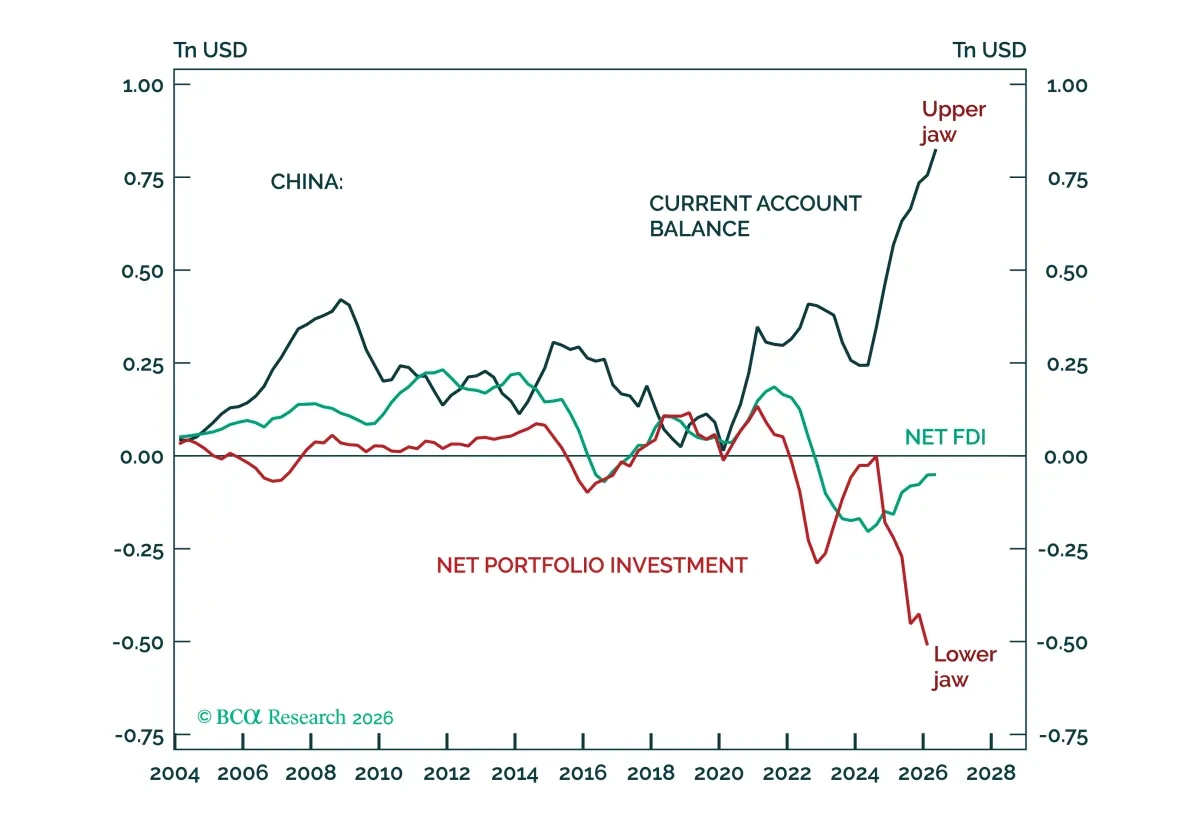
- The main driver of currency markets will change from interest rates to the balance of payments.
- The dollar’s dependence on net foreign flows into US equities is far greater today than ever.
- A low bar for US dollar depreciation: No net capital outflows necessary — just smaller inflows.
- A weaker US dollar will be deflationary, not reflationary, for the rest of the world.
- EM stocks will not rally in absolute terms despite a weak US dollar.
- Which asset classes and regions will perform the best during this US dollar devaluation?
Report
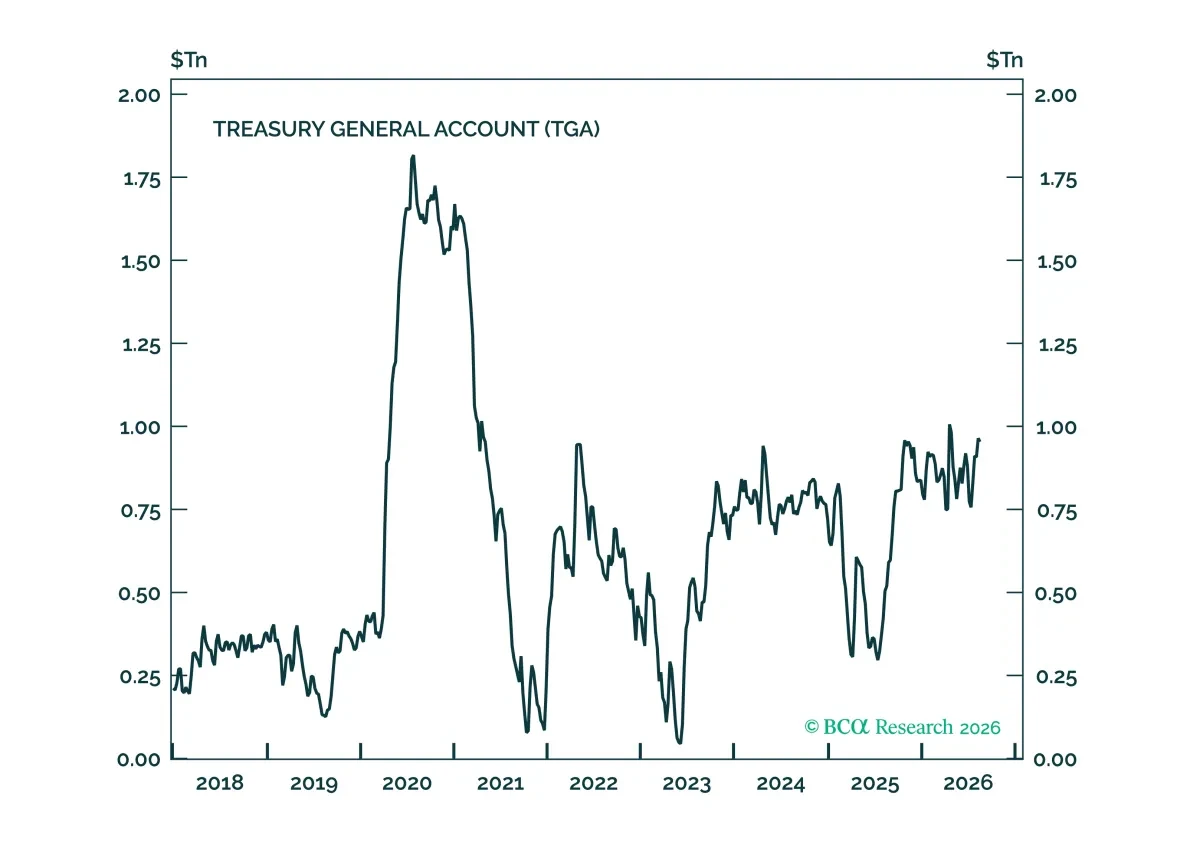
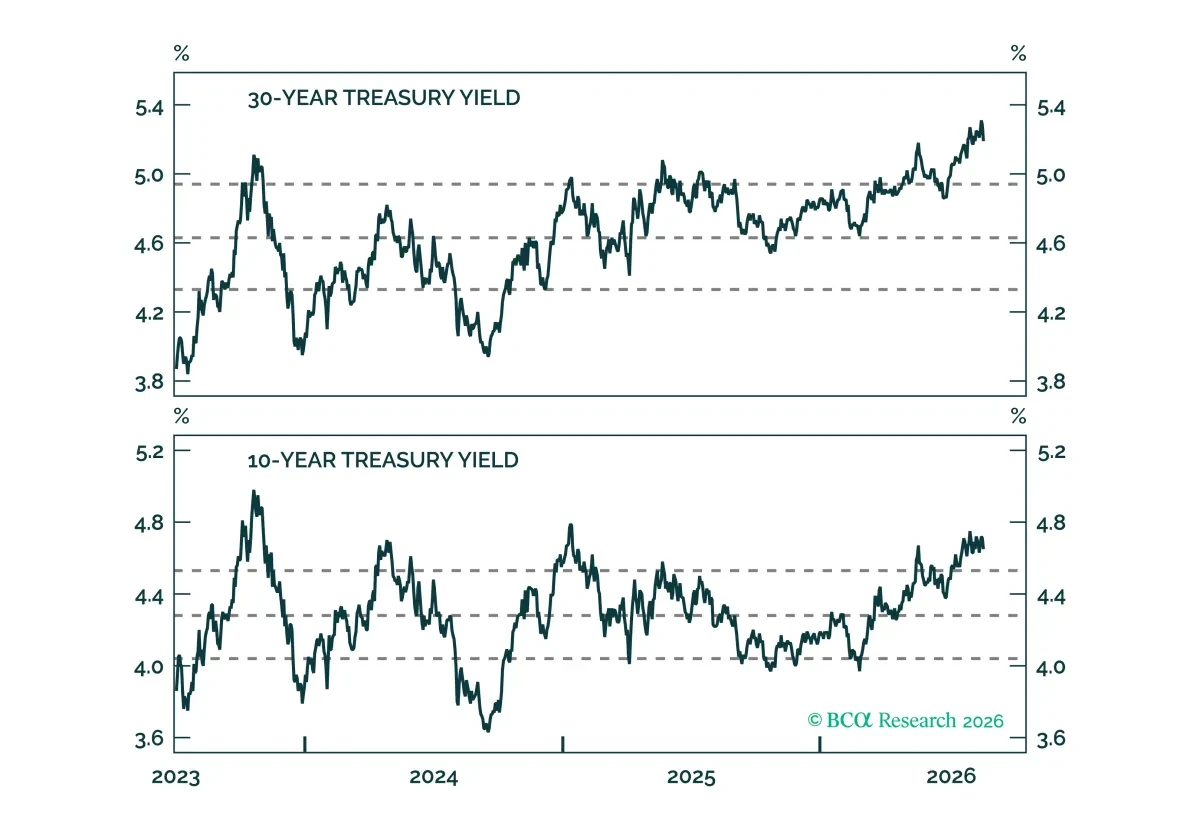
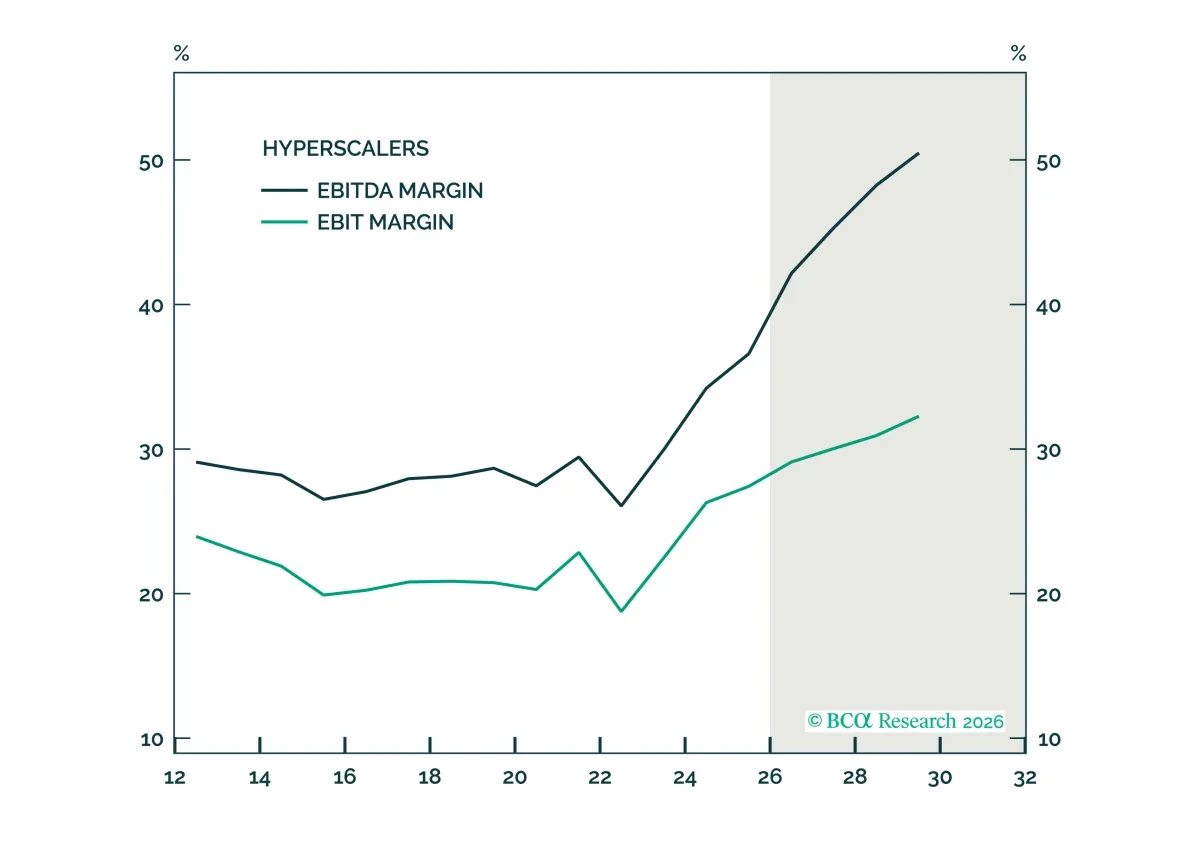
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury ...
Read more
Report
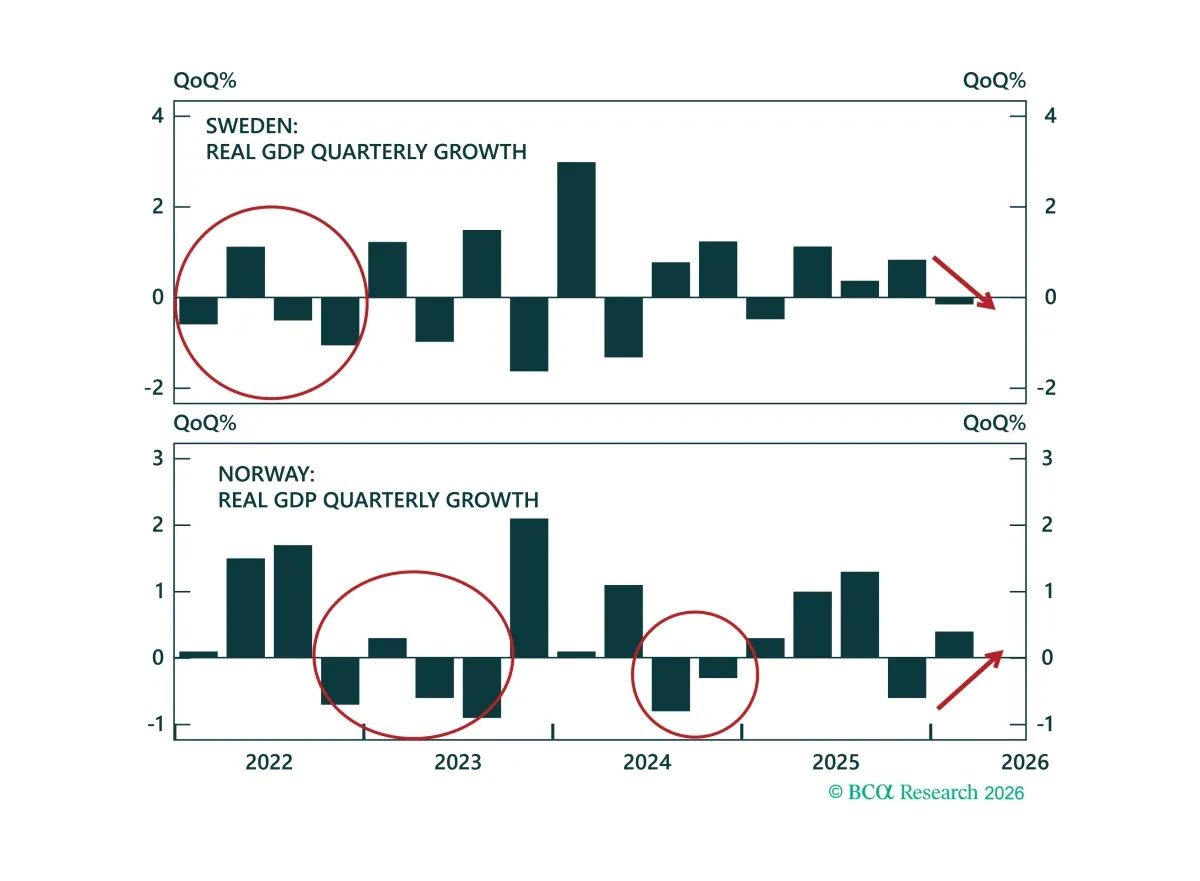
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian govern...
Read more
Report
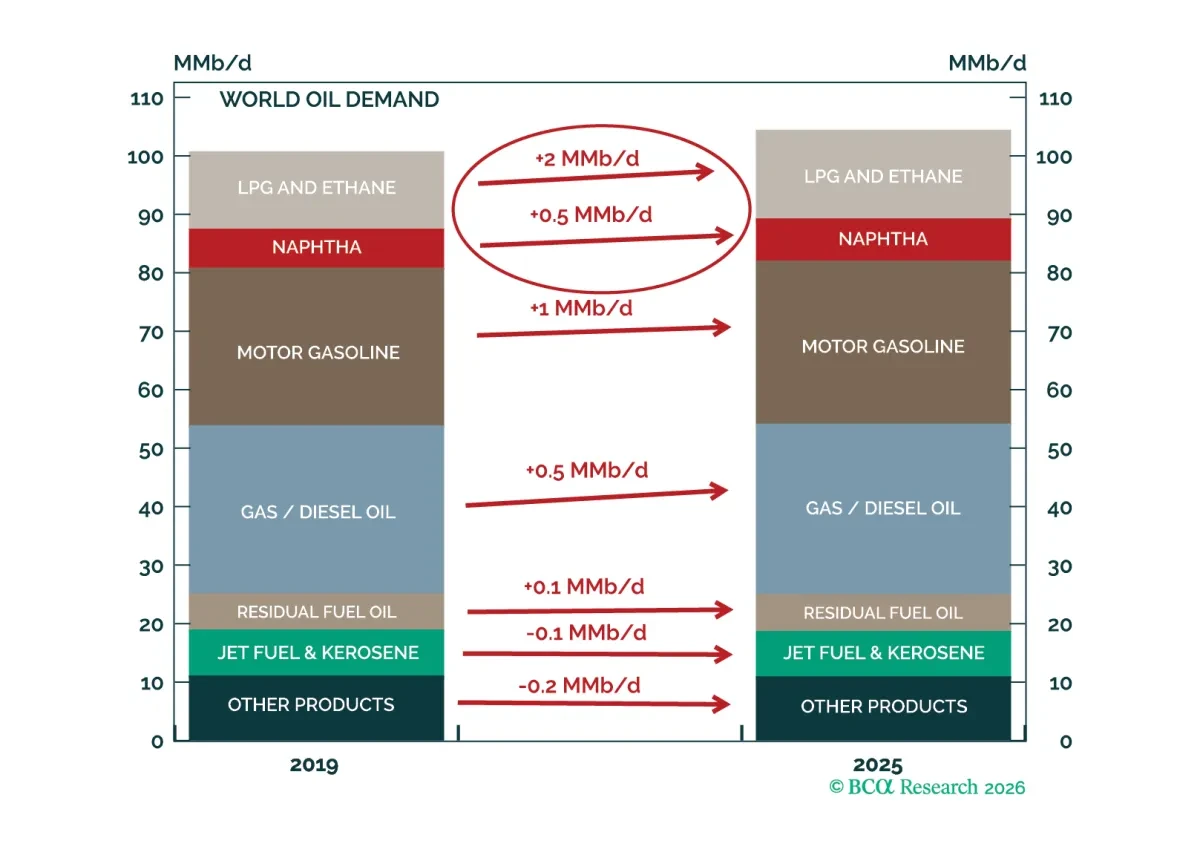
The Hormuz crisis has exposed a structural vulnerability in China's petrochemical value chain. Going forward, Beijing will look to build greater supply security by scaling up coal-to-olefins capacity — a shift that creates a structural tailwind for coal prices and a structural headwind for oil....
Read more