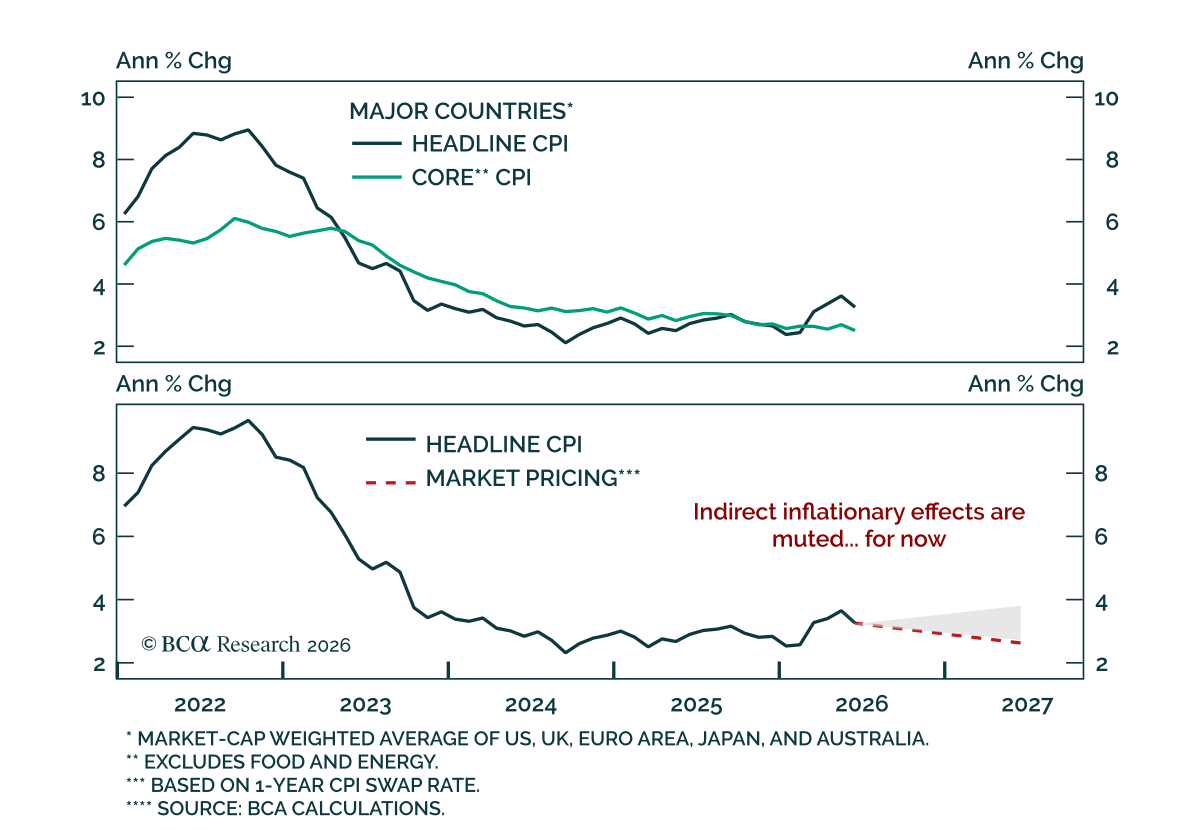
BCA Indicators/Model
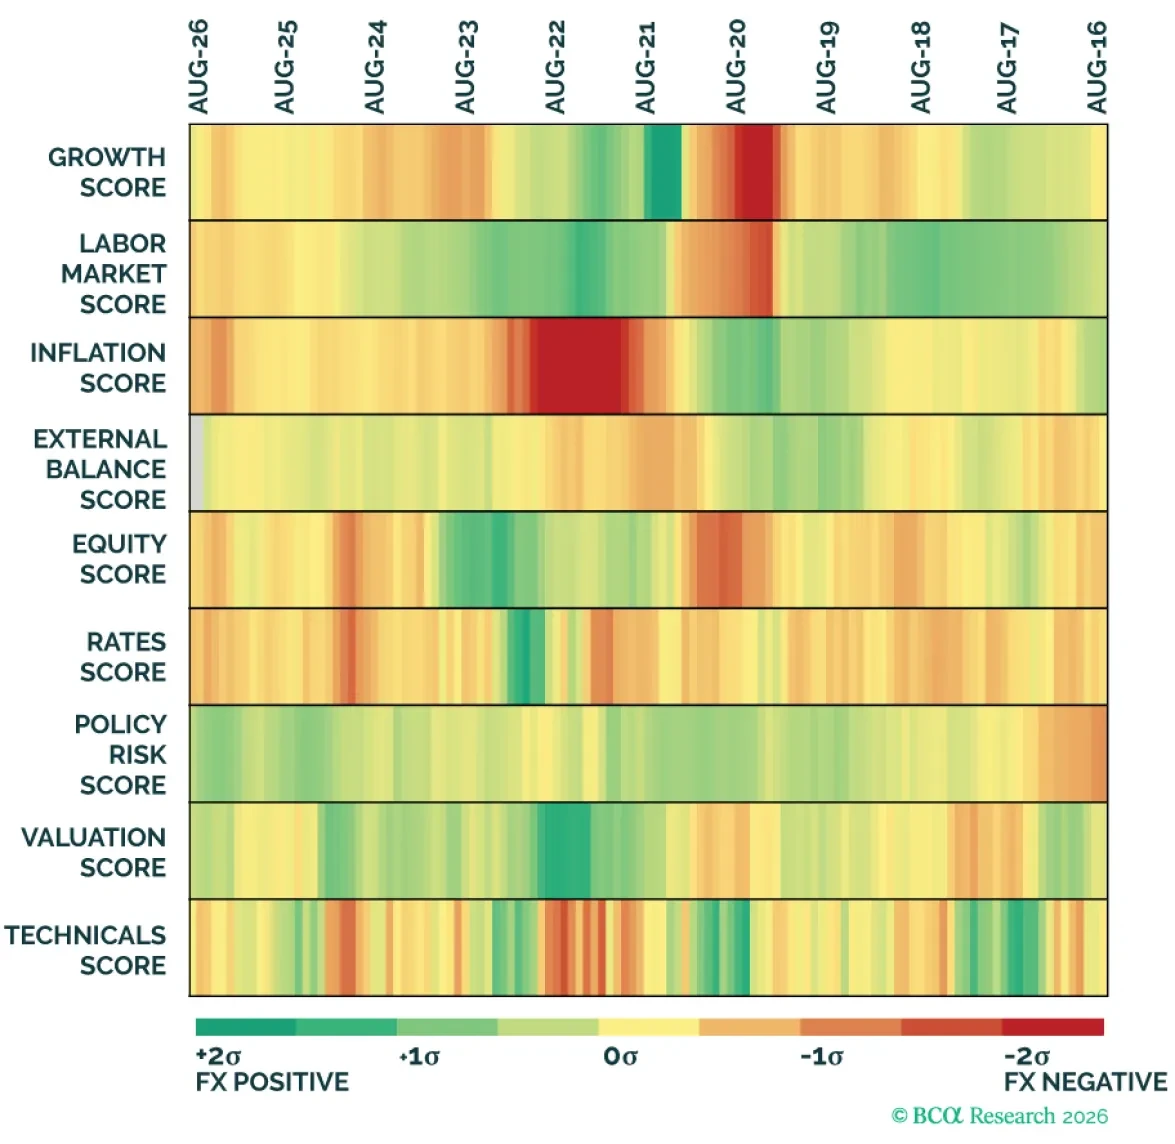
Foreign exchange markets are shaped by a wide range of macro influences. The sheer breadth of relevant information makes systematically assessing where a currency stands at any point in time a challenging analytical task. We introduce an FX scorecard that condenses the full range of data into nine thematic scores, providing a clear visual snapshot of a currency's position and how it's evolving.
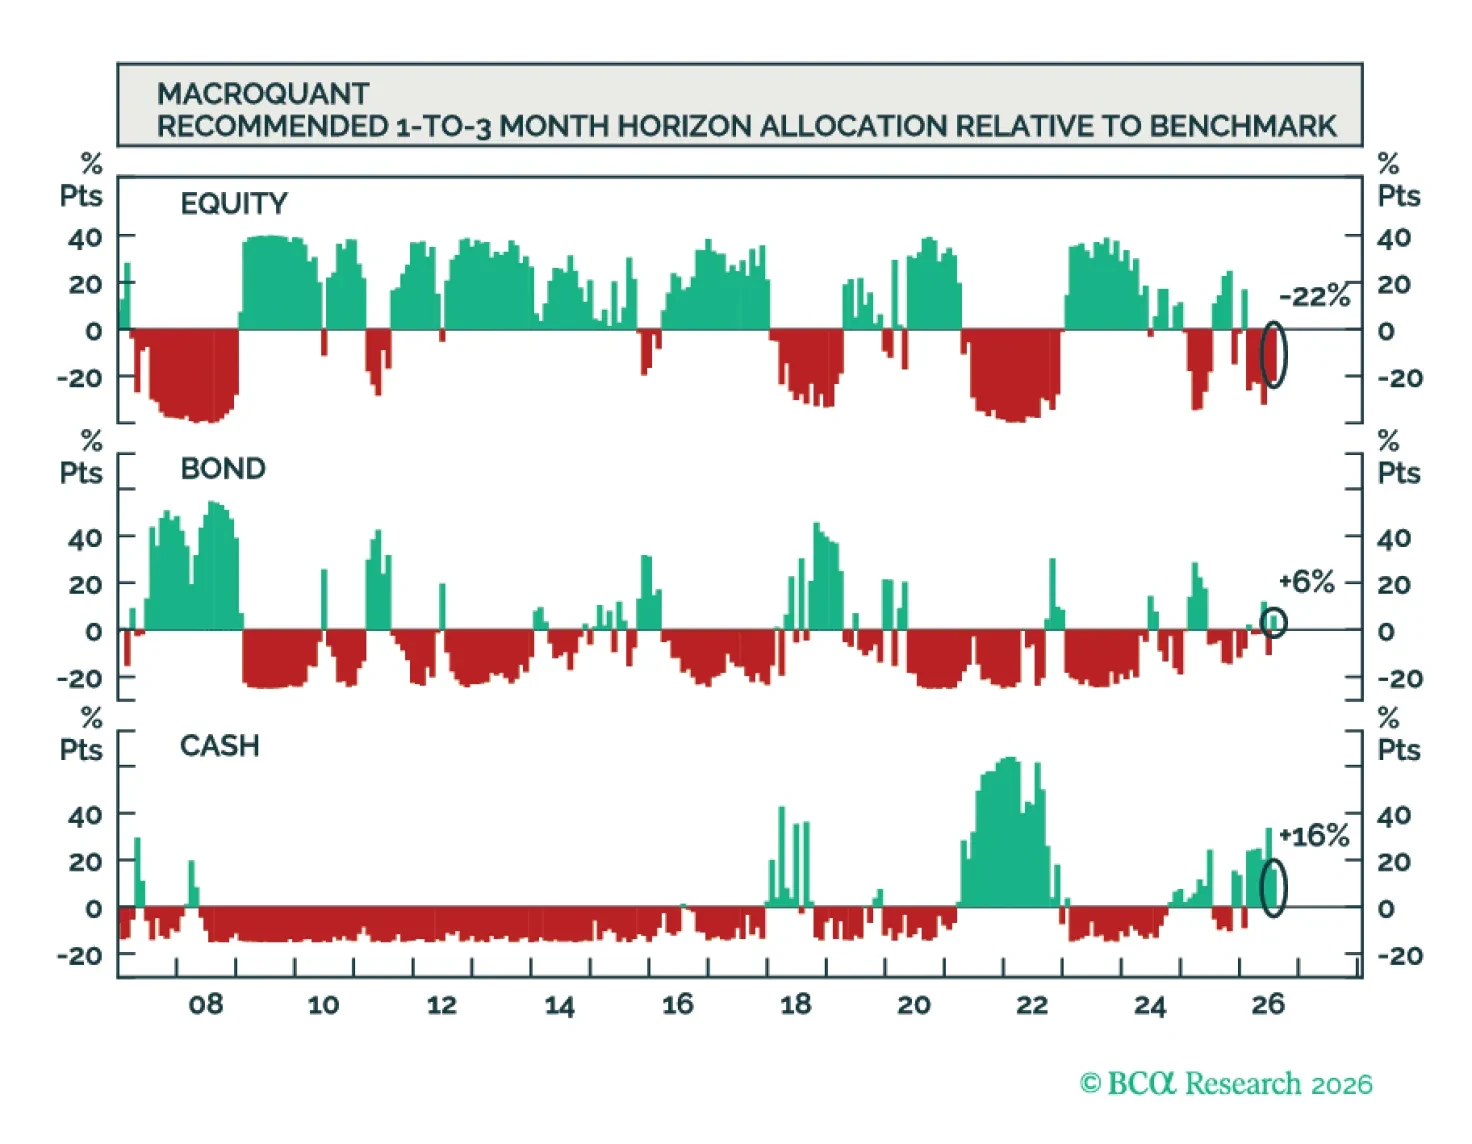
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
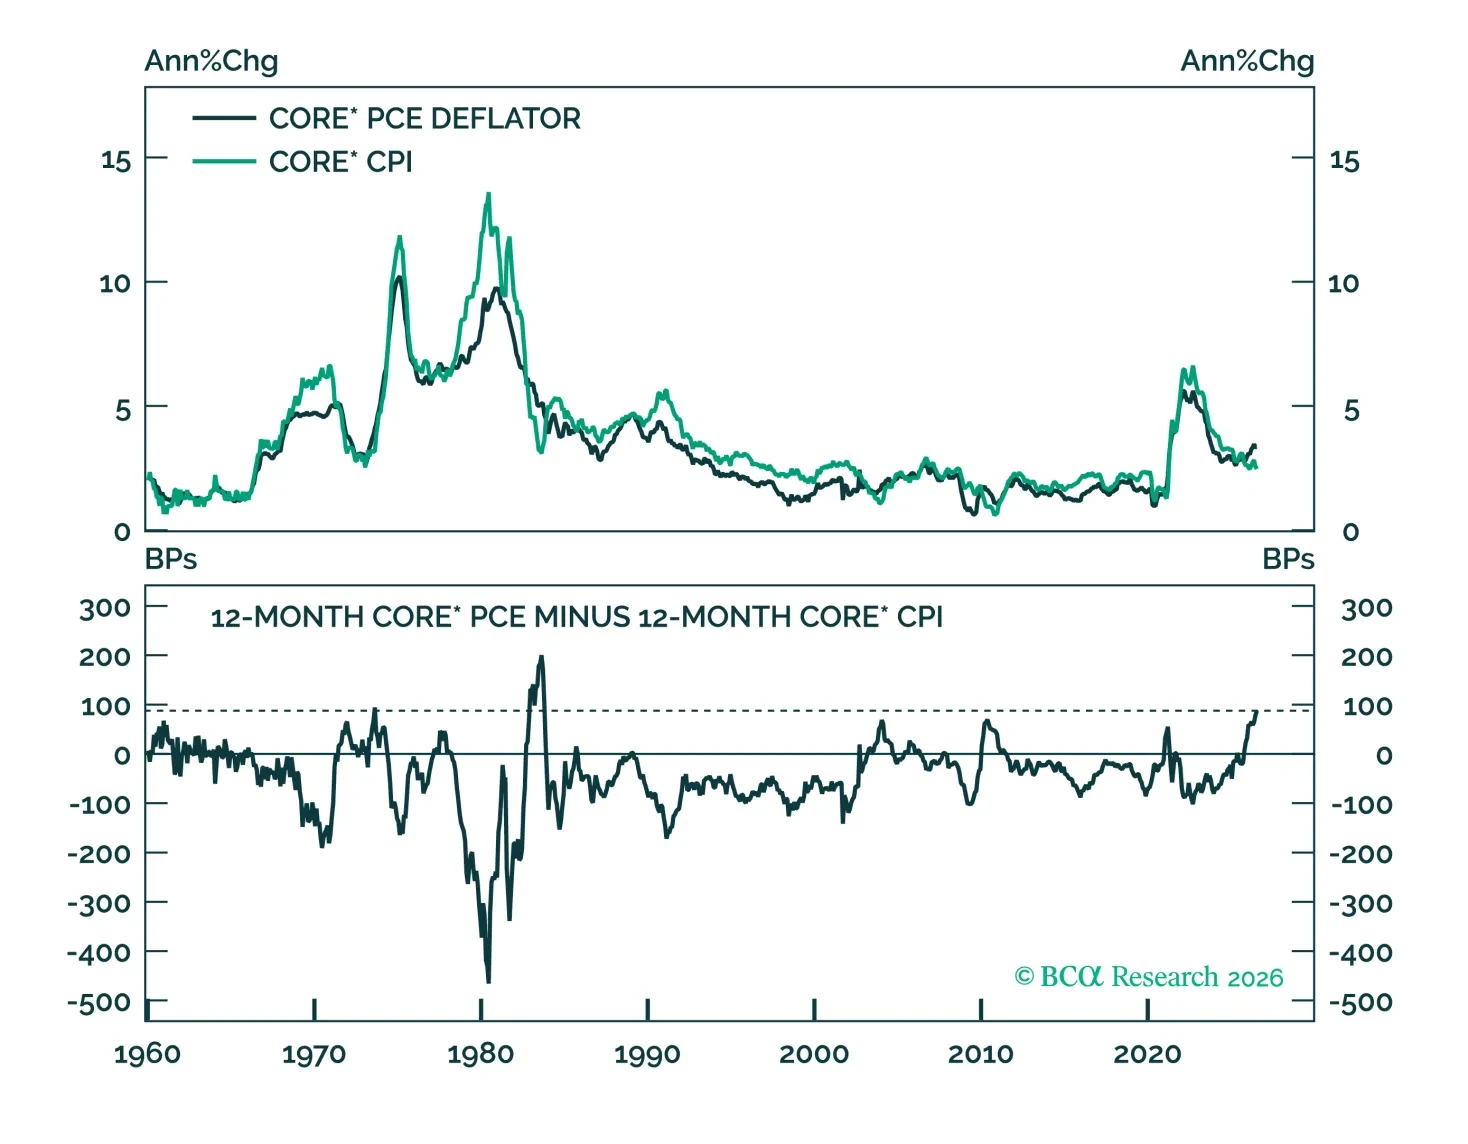
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
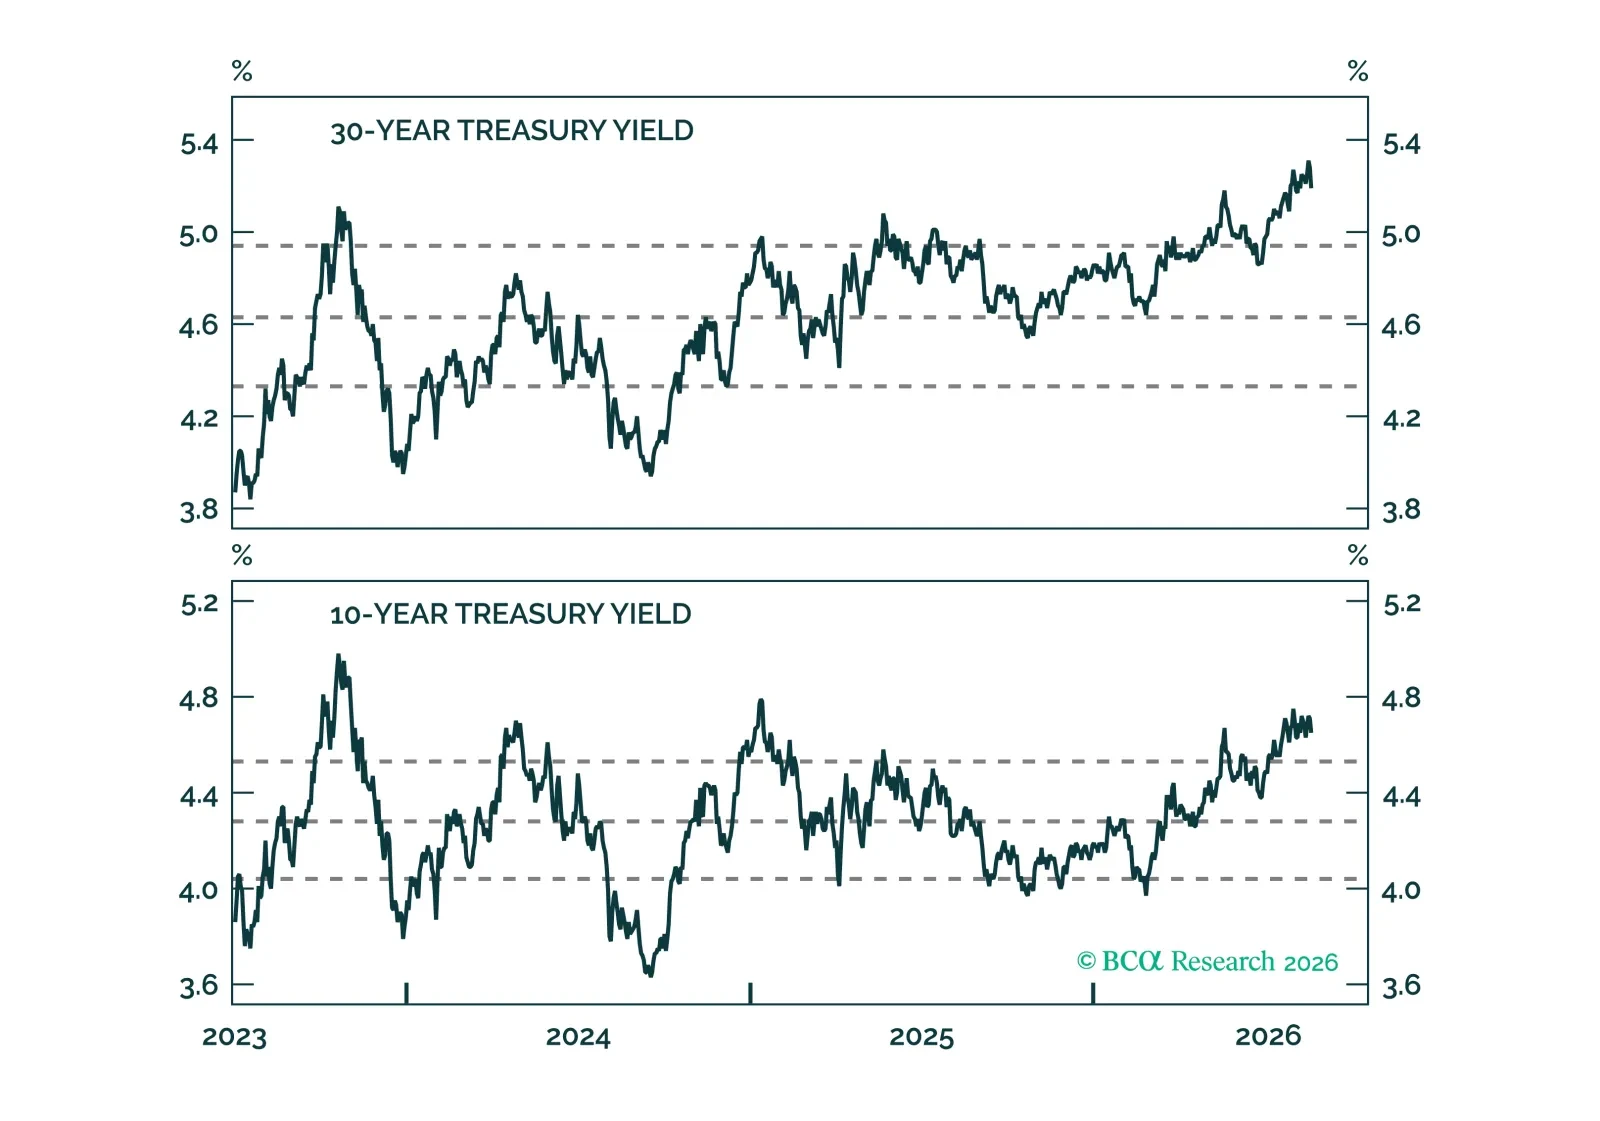
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.

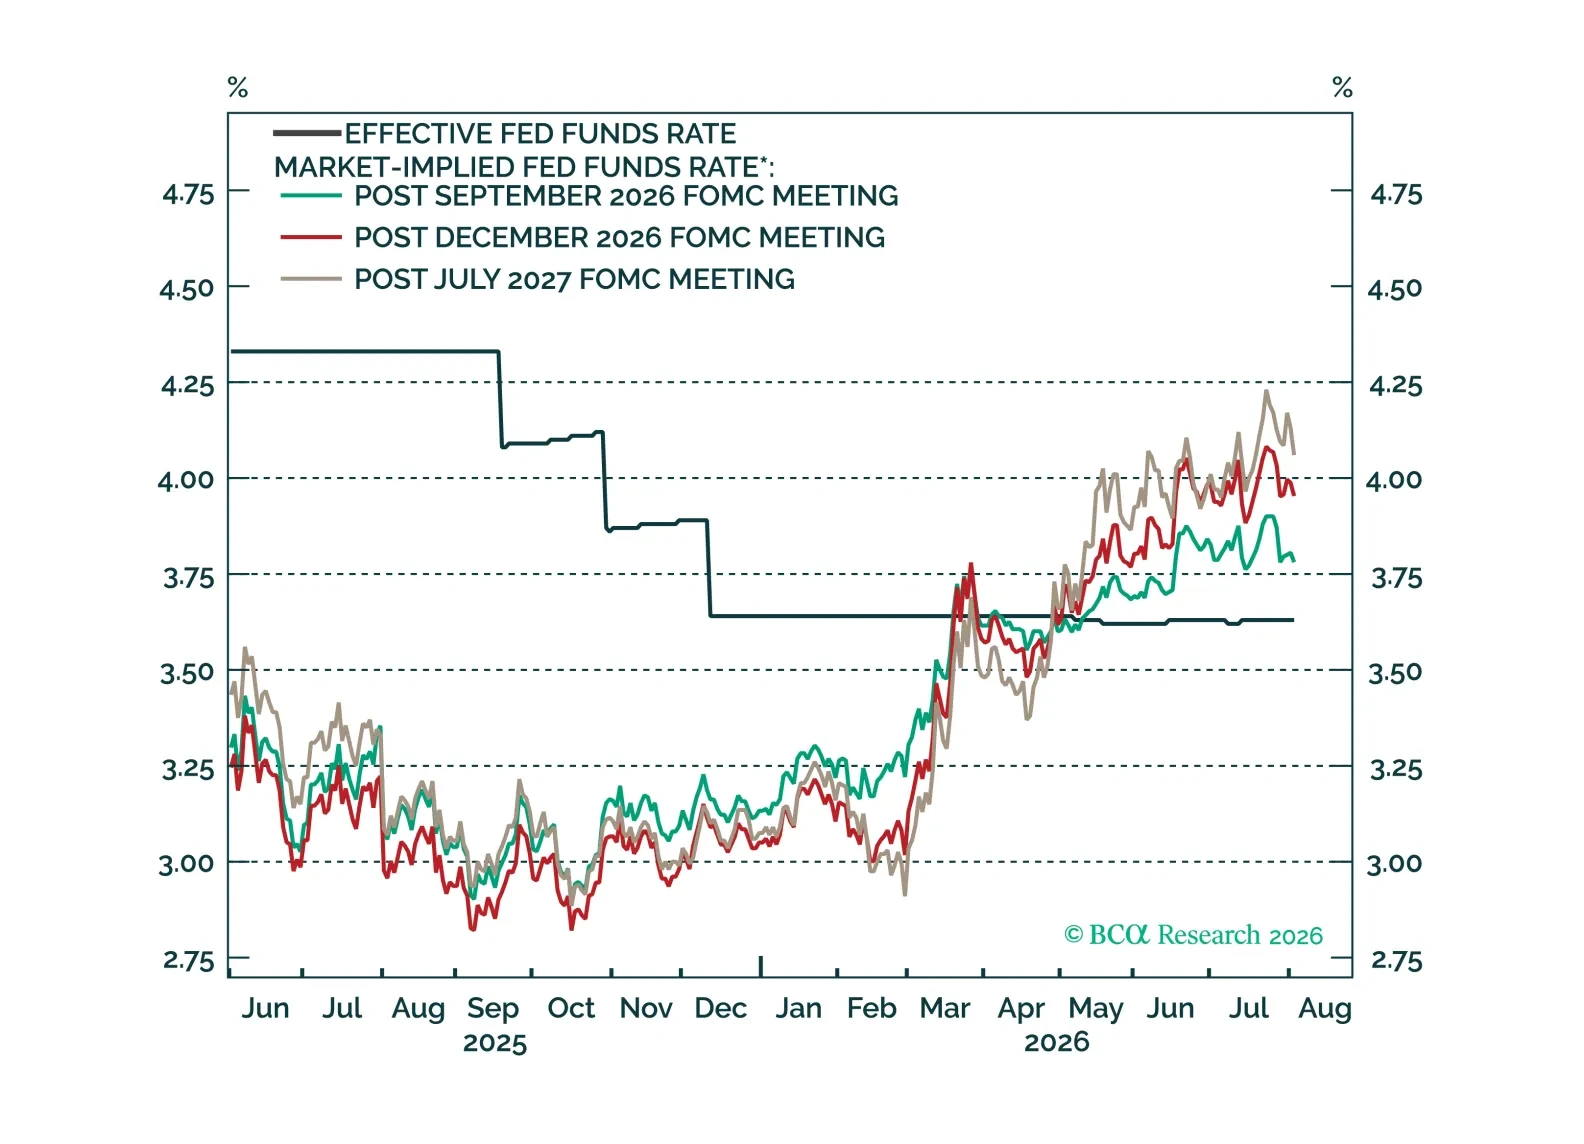
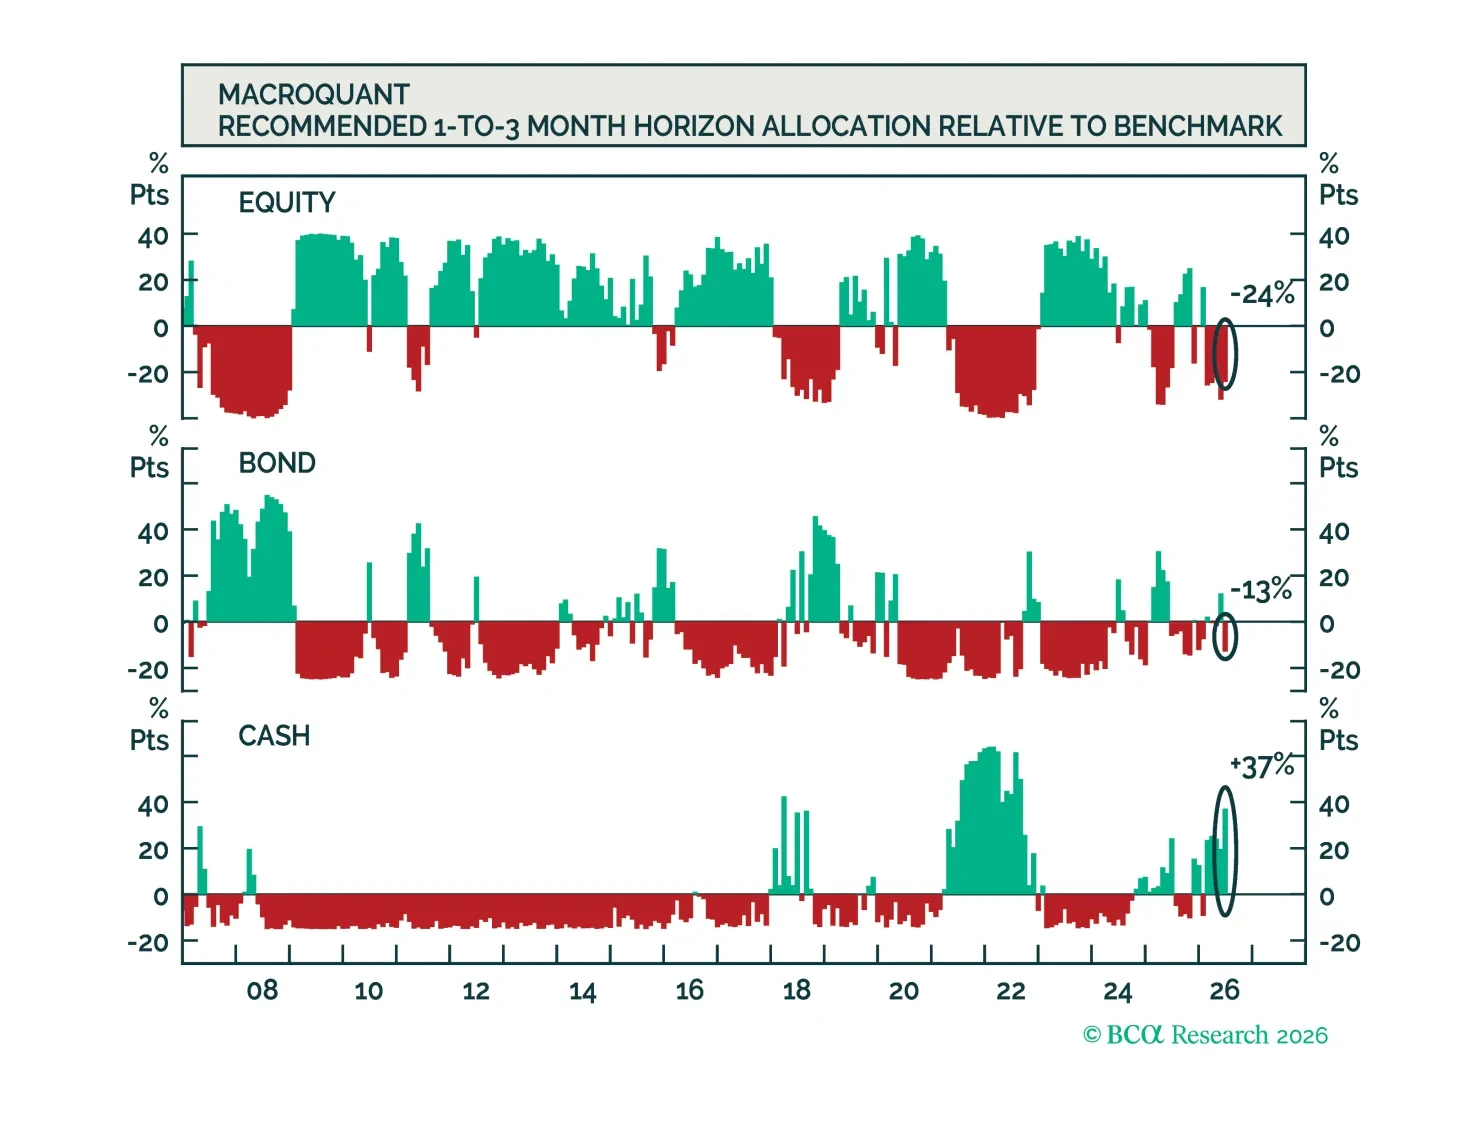
MacroQuant recommends a slight underweight position in equities, and favors a below-benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, neutral on gold, constructive on copper, and very bullish on oil.
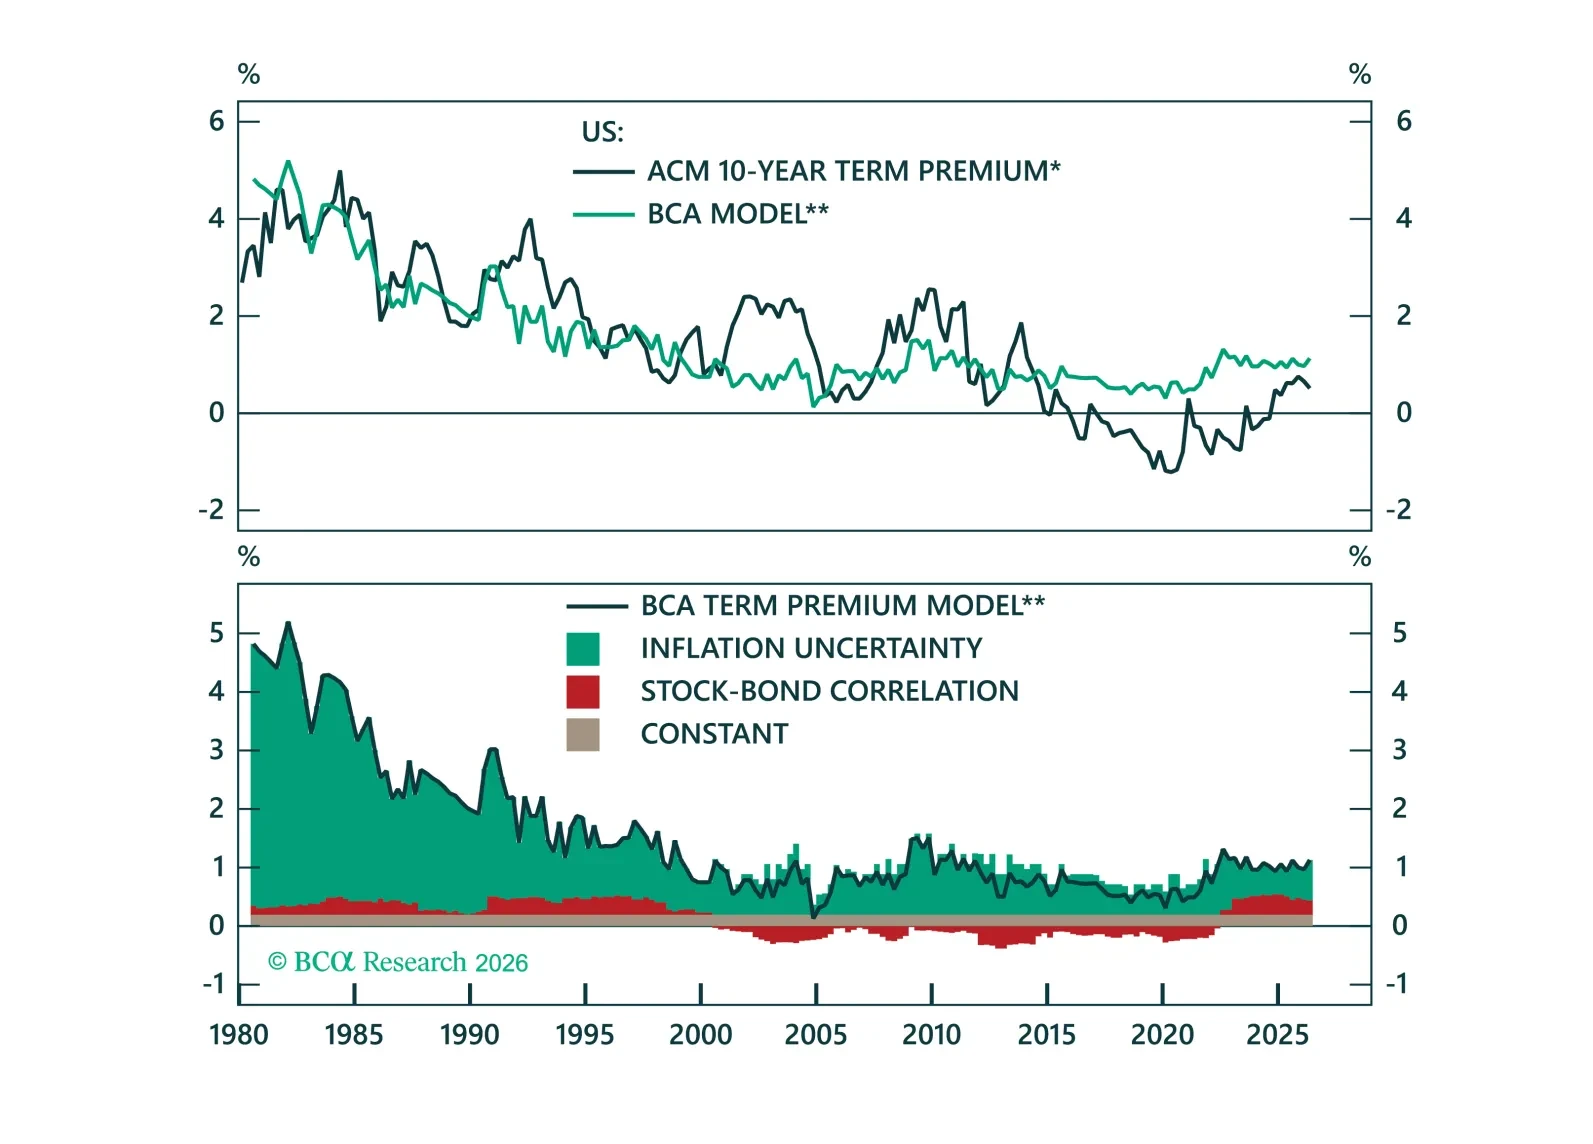
Rising term premium is often read as a fiscal warning sign. We show the real driver is monetary policy uncertainty, and what the implications are for global term premia going forward.
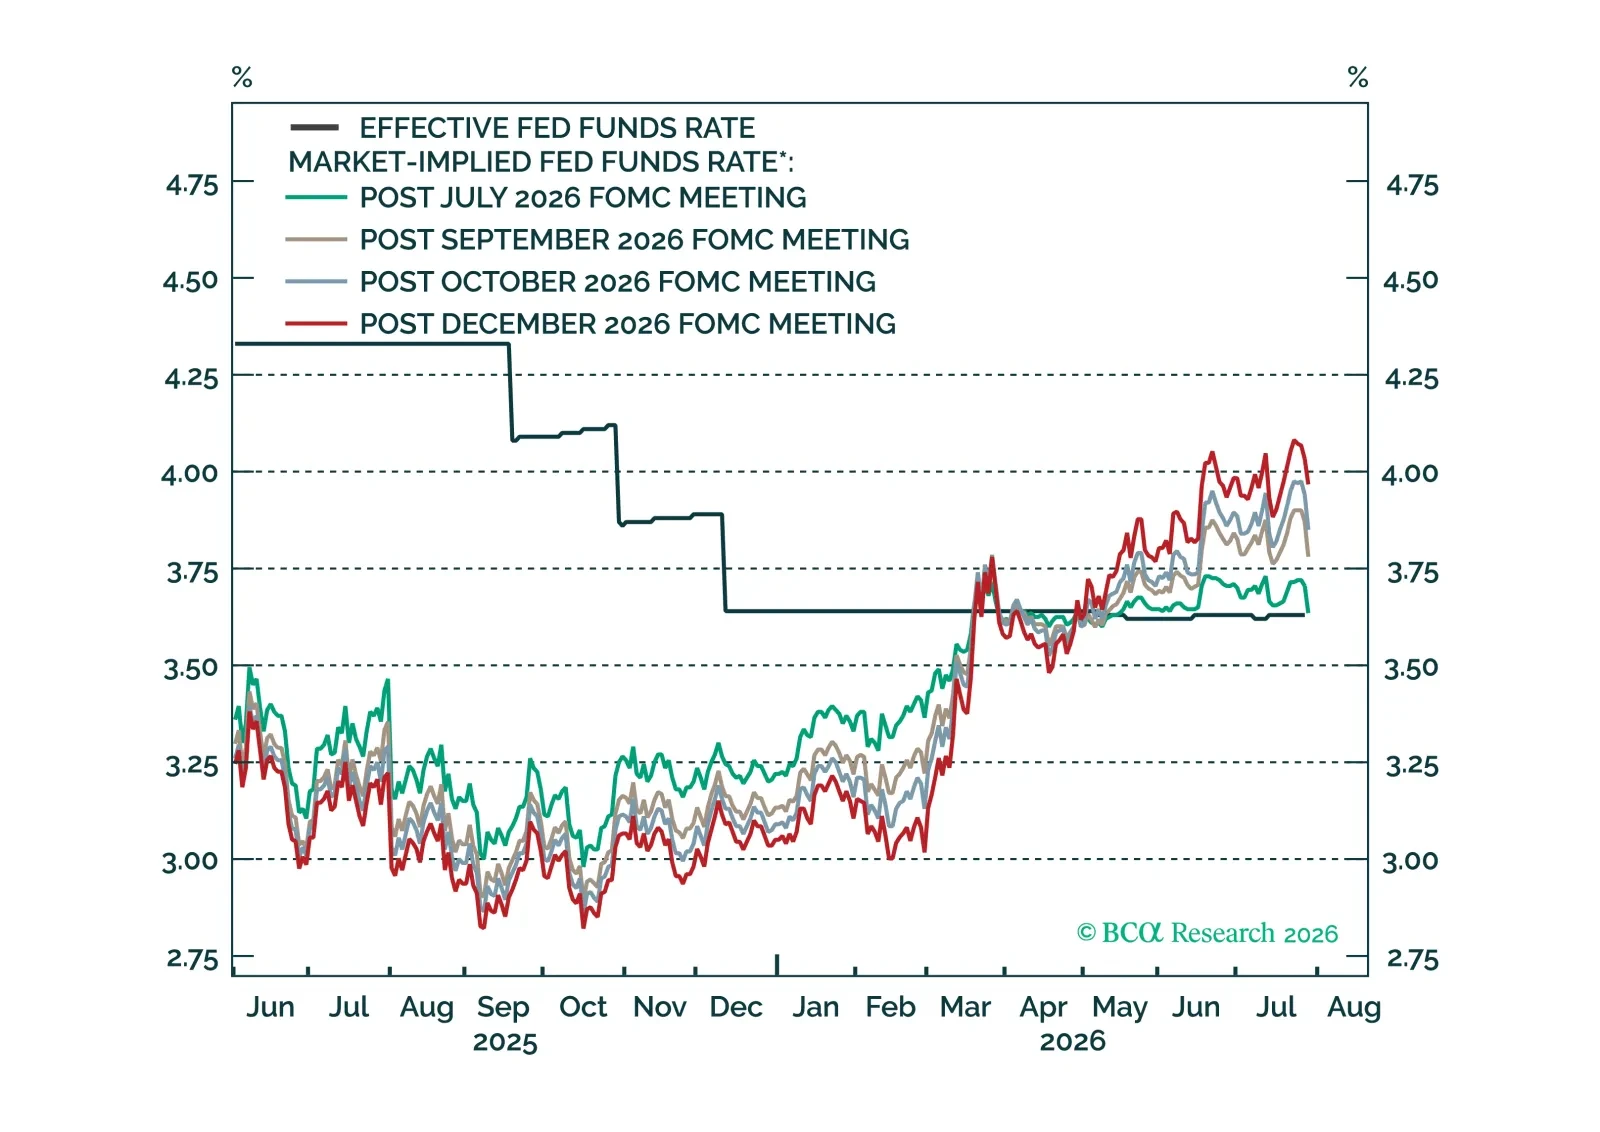
Despite today’s hold, the bar for a rate hike in September remains low and contingent on the next two core CPI reports.