Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Insights

Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
bca.fes_si_2026_06_25_thumbnail.png
Report
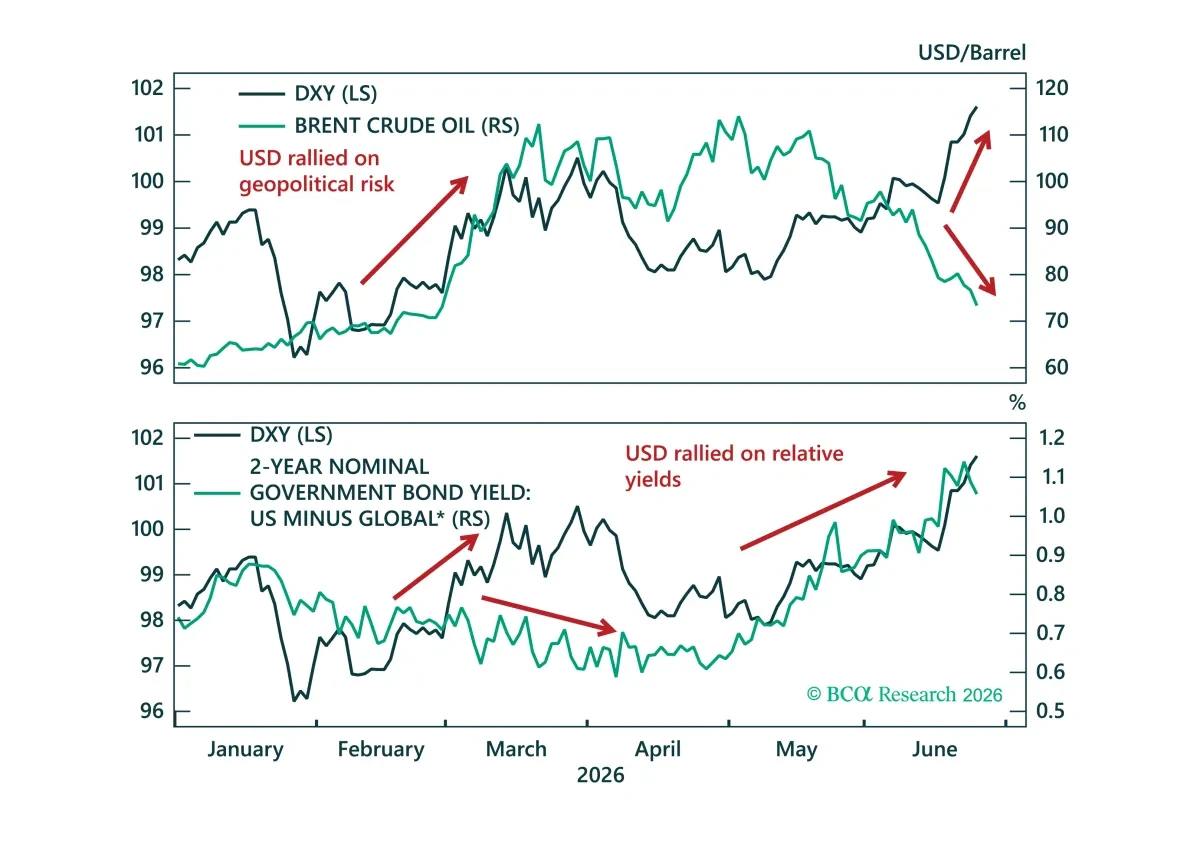
The dollar has had a strong run but its key supports from Fed repricing, positioning, and terms of trade are starting to fade. We close our tactical long USD positions and turn to short USD/JPY, where intervention risk makes yen shorts look increasingly dangerous....
Read more
Noah Weisberger.png
Webcast Replay

Hosted By: Noah Weisberger, Chief US Equity Strategist

Moderated By: Jason Glazer, Senior VP, Sales

The US economy is back in Expansion, with growth positive and improving, and US equities continue to climb on the back of a firming cycle and AI-related drivers. Fundamentals still look firm: earnings expectations are rising, margins are expanding, and corporate commentary points to durable demand. But sticky inflation, higher rates, tighter financial conditions, and a coming wave of monster IPOs raise the bar for valuations.

Key topics discussed:

  • Expansion extends: what the cyclical indicators are signaling now
  • Capex, cash flow, AI: the boom/bubble debate, and why free cash flow matters
  • Beyond tech: where AI demand and infrastructure needs are showing up next
  • Earnings and margins: how much support is still coming from fundamentals
  • Rates and valuations: why this may be the real constraint
  • IPO supply: what 40 years of data suggests about forward returns
  • Tactically, oil price relief is a reason for cyclical exposures and laggards to get a look: Long Materials, Long Consumer Cyclicals
 

bca.ems_mid_2026_06_24_cw.png
Report
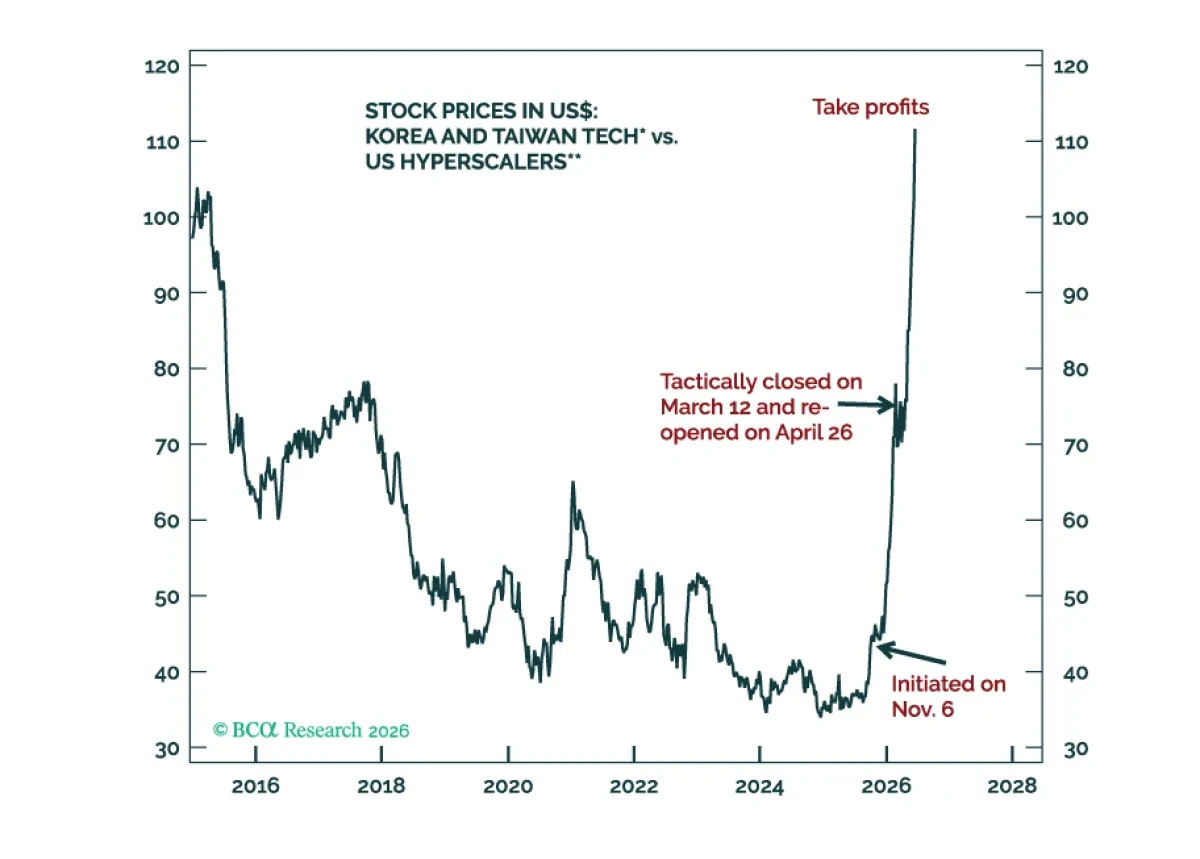
Korea’s recent equity market tantrum is a warning signal for global risk assets. We are booking profits on the long Asian semiconductor stocks / short US hyperscalers trade and downgrading Korea from overweight to neutral in an EM equity portfolio....
Read more
Noah Weisberger.png
Webcast Replay

Hosted By: Noah Weisberger, Chief US Equity Strategist

Moderated By: Jason Glazer, Senior VP, Sales

Key Topics Discussed:

  • A 2H2026 update of our outlook: Fundamentals vs. fears
  • What are our baskets telling us: Rotation not regime break
  • Growth ascendant: Inflation fears contained
  • Tactically long consumer (on the back of oil price relief)
bca.pma_sr_2026_06_24_cover.png
Report
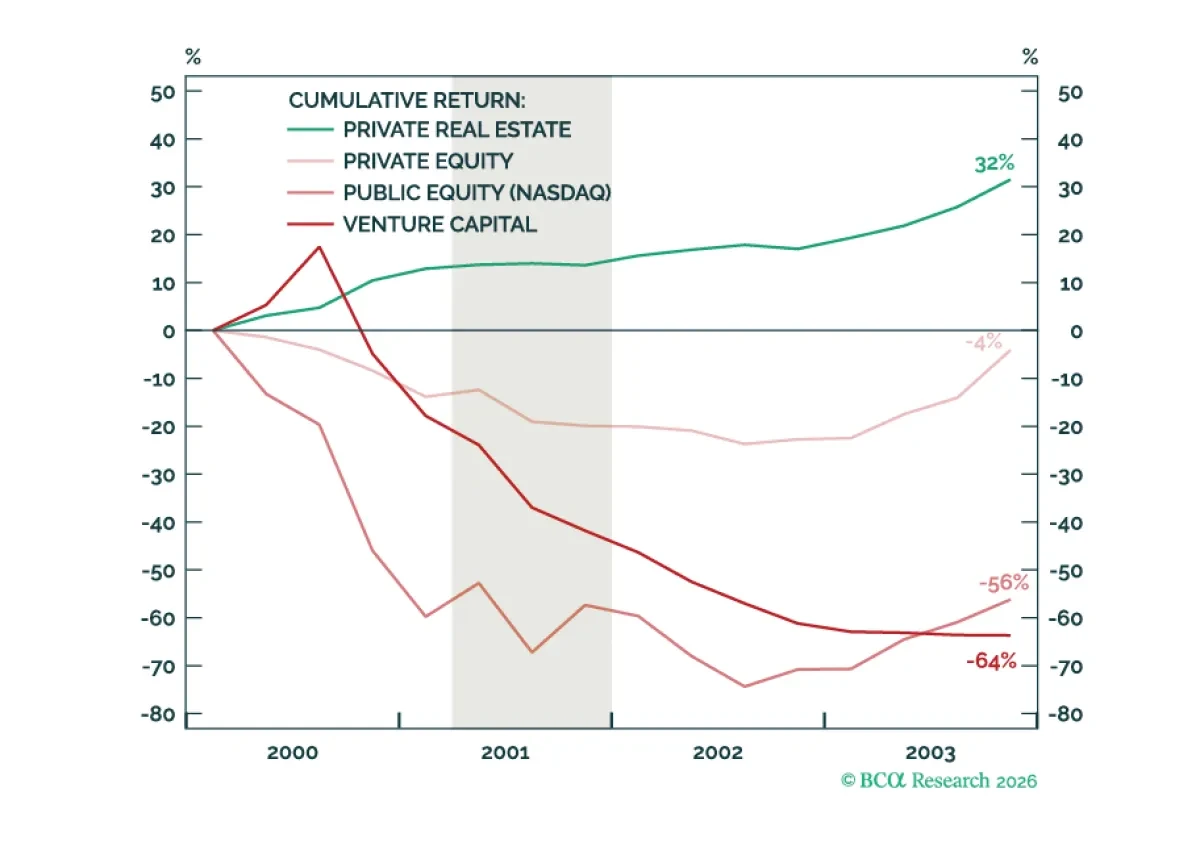
AI dominates markets, but concentration is risk. Real Estate is the diversifier. It outperformed during the Dot-Com bust and will do so again if the AI trade unwinds. Even Office, the sector arguably most exposed to AI disruption, will prove more resilient than bears expect....
Read more
bca.gps_si_2026_06_23_cx.png
Report
Stay overweight gilts despite renewed political turmoil in the UK....
Read more
bca.ets_si_2026_06_23_cms.png
Report
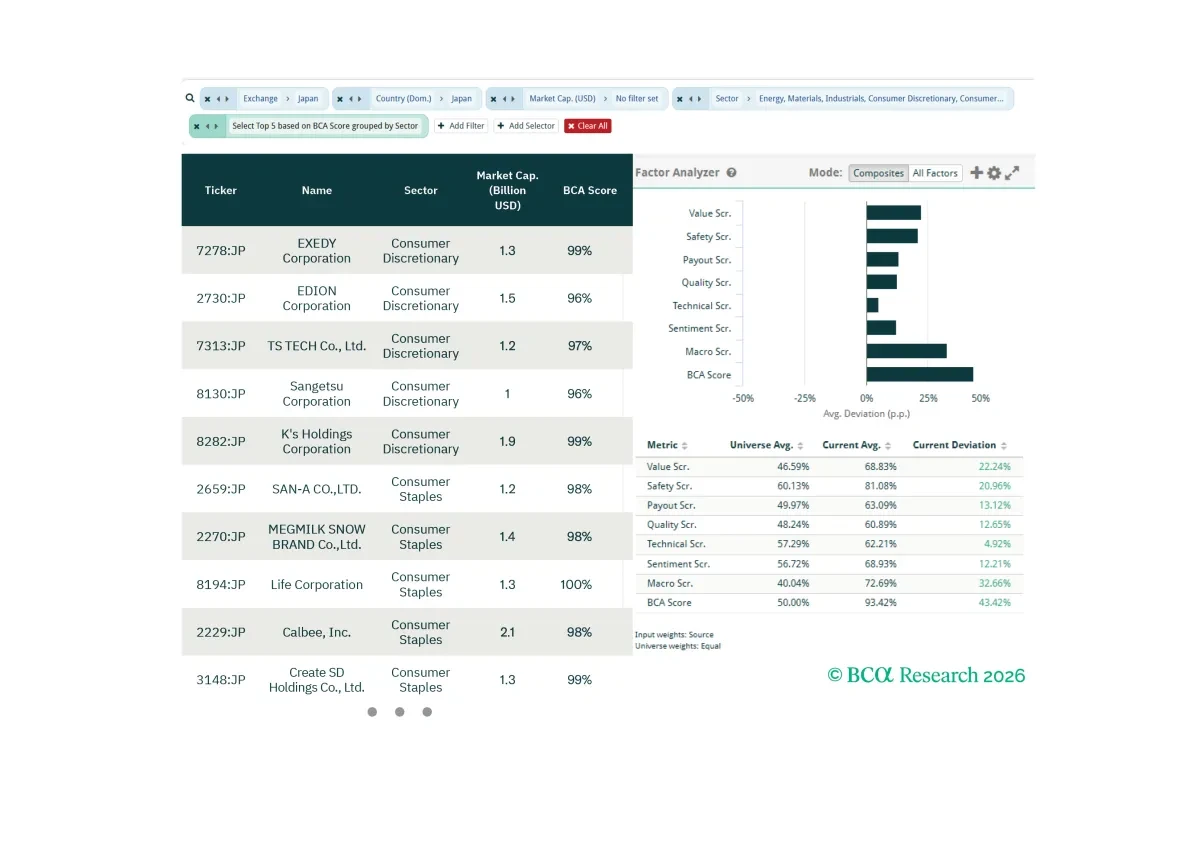
In this screener report, we explore opportunities in Japanese Non-TMT equities, El Niño hedges, and US consumer-facing equities....
Read more
bca.uses_wr_2026_06_23_cms.png
Report
The economy has shifted into Expansion, earnings growth is broader and stronger than we expected, and we are raising our 2026 S&P 500 target to 8100 on $330 of EPS. However, we are also cutting our year-end multiple to 24.5. From here, returns will need to come from earnings growth, not multiple...
Read more
Matt_Mathieu.png
Webcast Replay

Please join Chief Strategists Matt Gertken and Mathieu Savary for a Webcast.

Mathieu and Matt discussed:

  • The US-Iran deal and next steps in trying to resume global commodity flows.
  • The impact of energy prices on global demand, inflation, and interest rates so far.
  • Different scenarios for commodity prices and economic impacts going forward.
  • How the market is likely to respond to these scenarios – and what could go wrong.
  • What other geopolitical and macro risks and opportunities are looming in H2 2026?
bca.gfis_sr_2026_06_23_thumbnail.png
Report
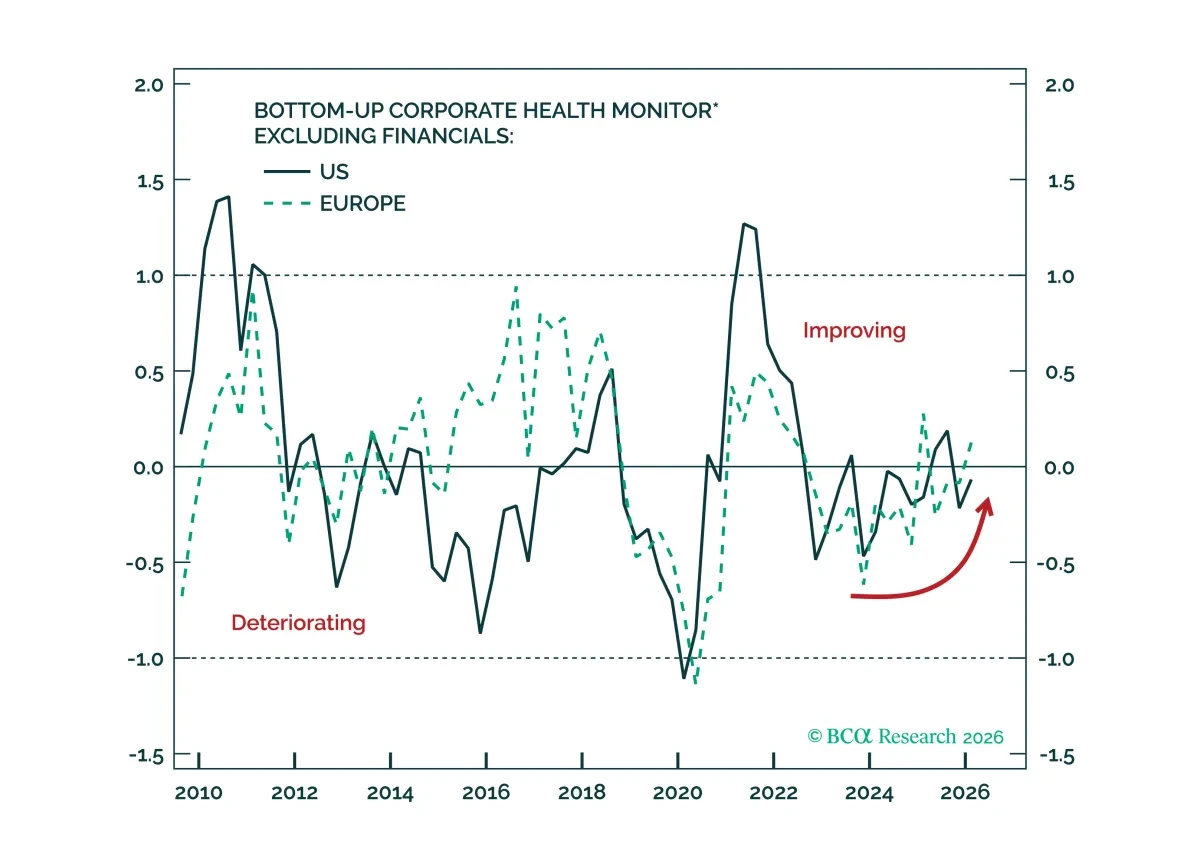
Corporate health remains supportive of tight credit spreads in both the US and Europe, but a growing divide is emerging beneath the surface. Investment-grade issuers continue to strengthen, while lower-rated borrowers face mounting pressures. Credit markets are pricing resilience, leaving investors ...
Read more