Insights
Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
Report
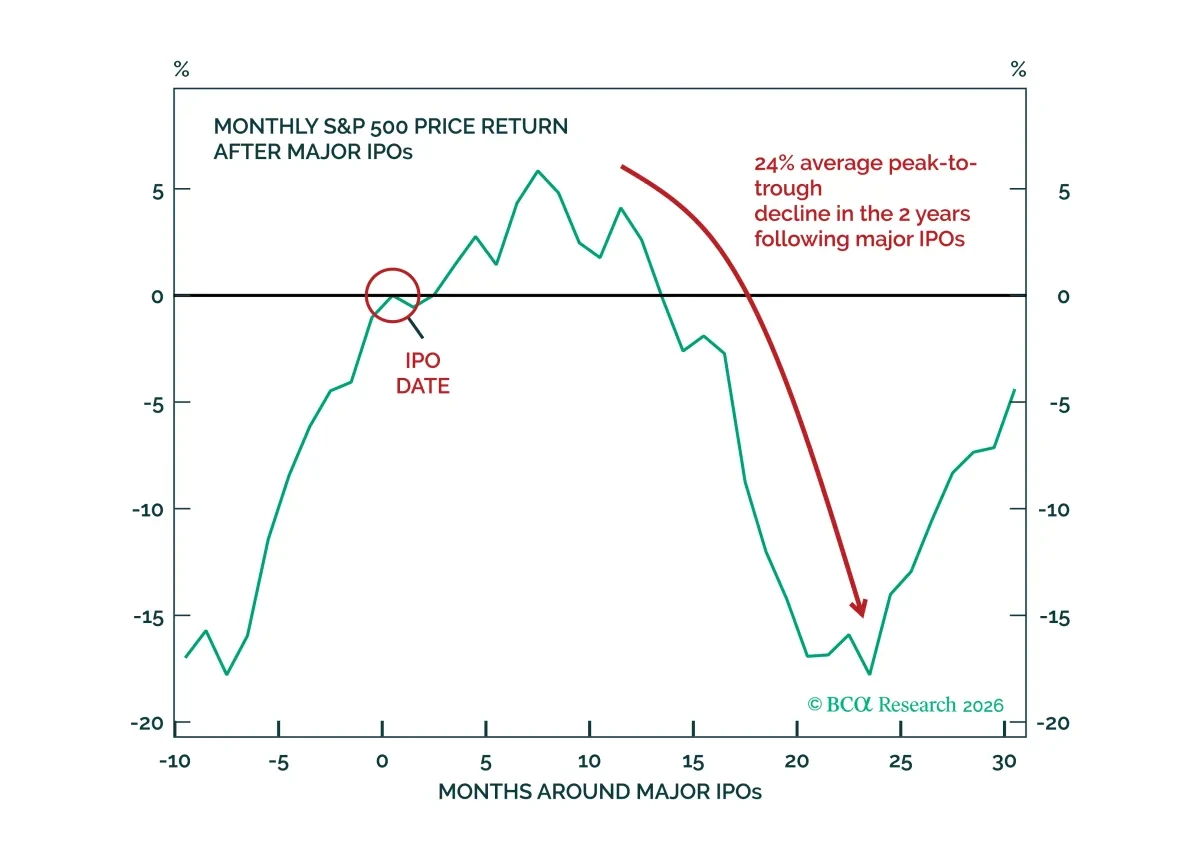
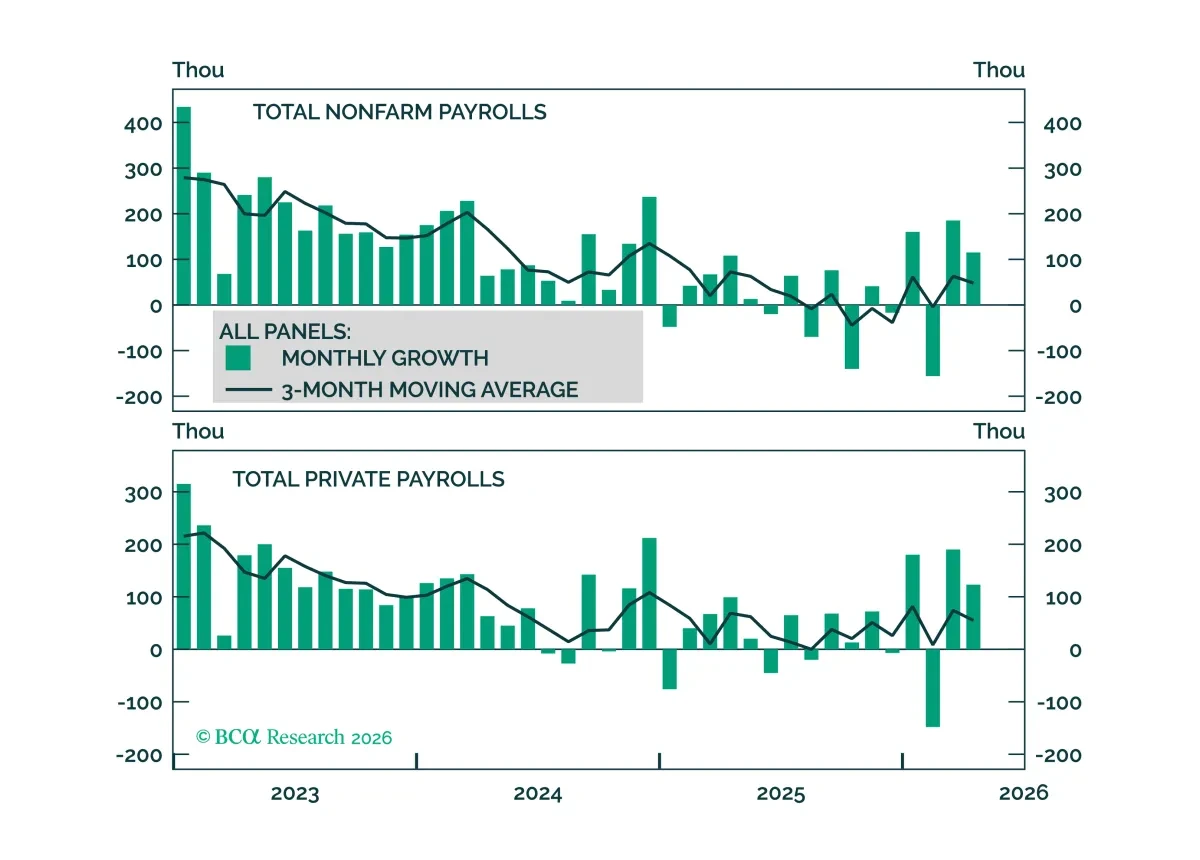
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities.&nbs...
Read more
Report
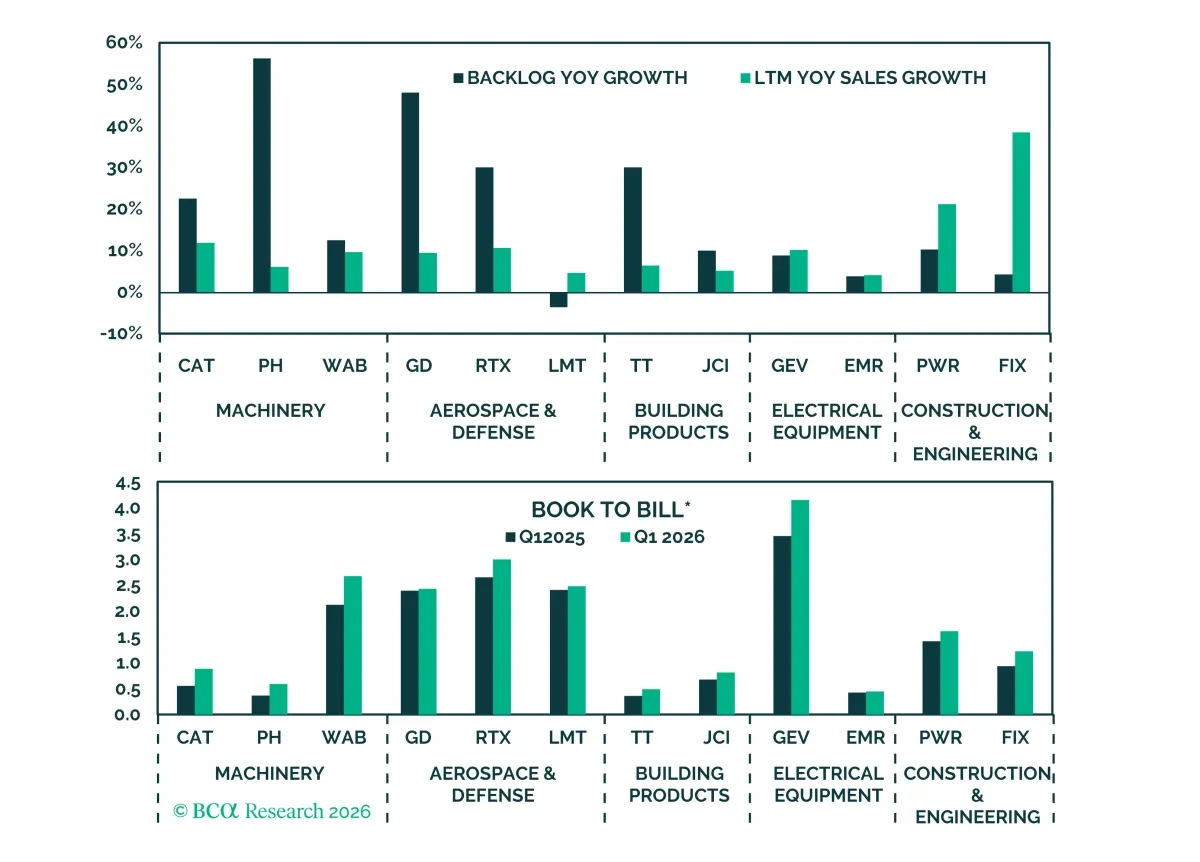
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, whil...
Read more
Report
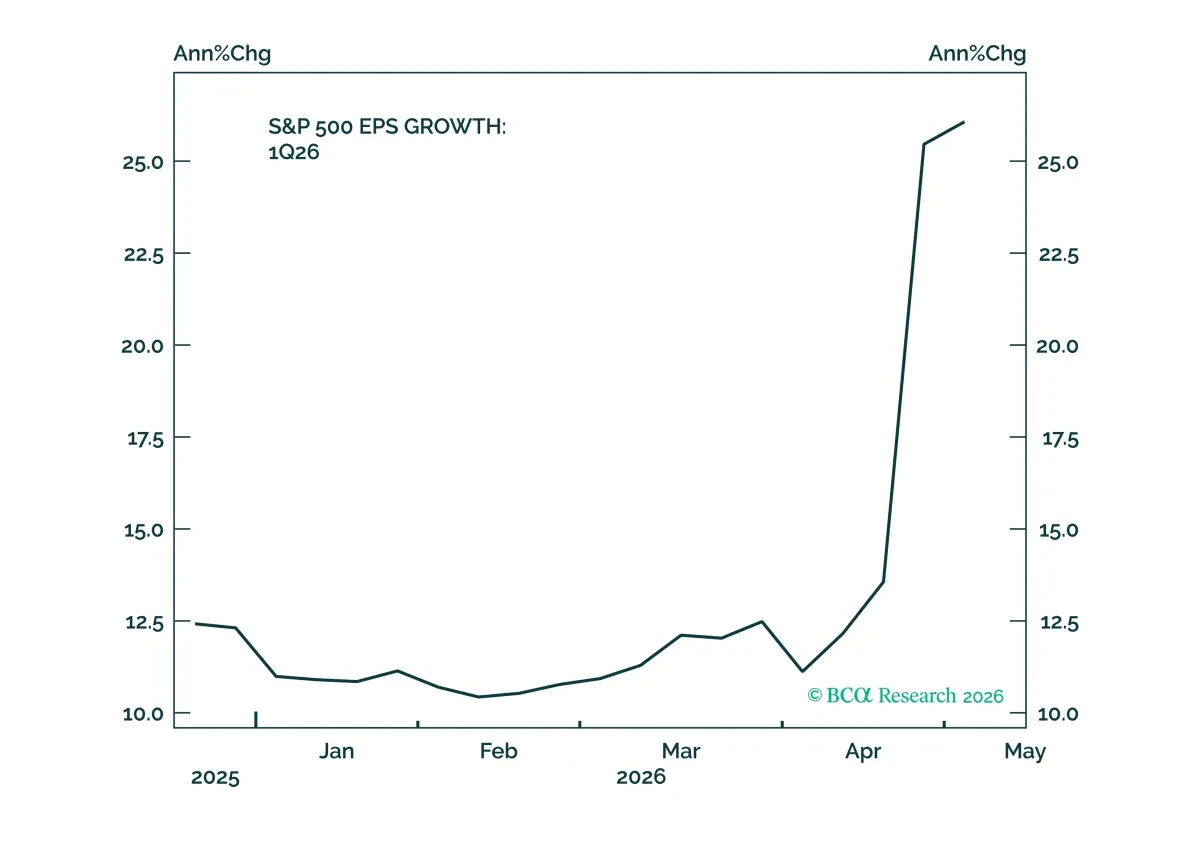
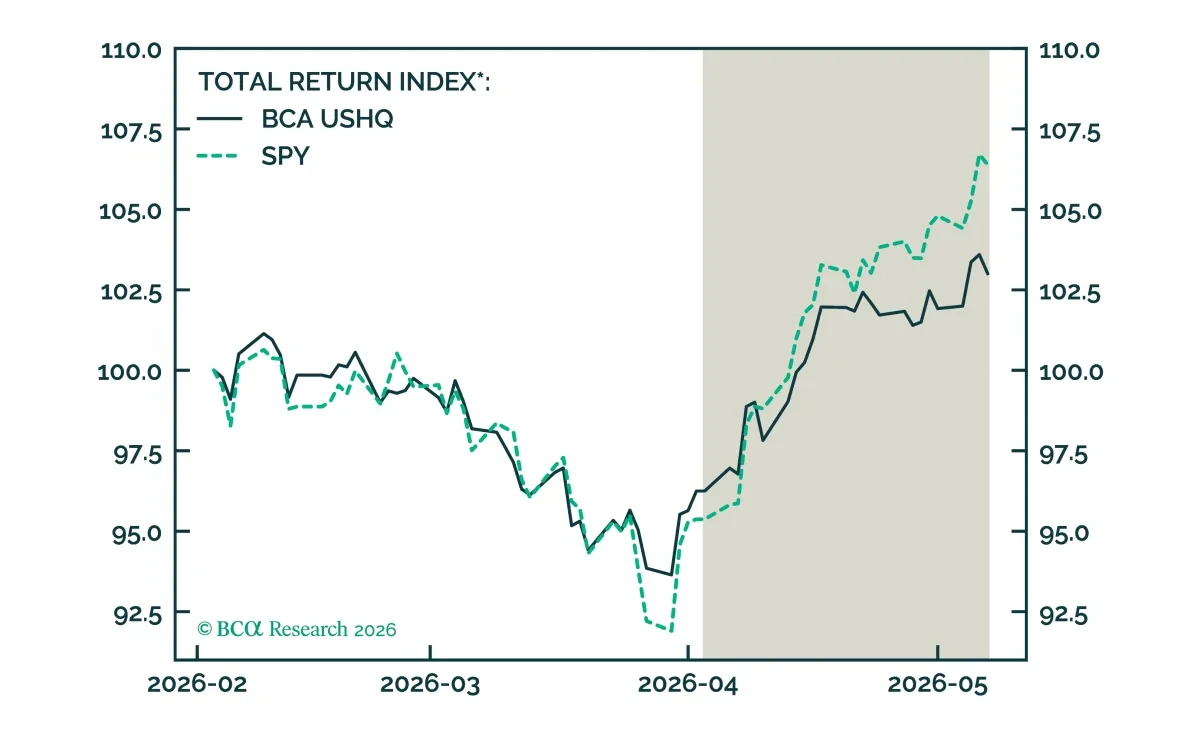
The US High Quality (USHQ) portfolio underperformed its benchmark through April, returning 7.02%, while its SPY benchmark returned 11.55%. On a trailing three-month basis, the USHQ portfolio’s performance was weaker than the benchmark as well, with USHQ underperforming by approx. 338bps. ...
Read more

Webcast Replay
BCA Chief Strategists, Mathieu Savary, Roukaya Ibrahim, and Noah Weisberger looked at the latest developments in the Strait of Hormuz and the implications for global financial markets.
Topics discussed:
- The Strait of Hormuz remains closed, and energy markets are tightening again. Is the shock being underpriced?
- What would a sustained disruption mean for the global growth–inflation trade-off? Is stagflation risk creeping back?
- Within commodities, where is the real asymmetry now? What’s crowded, and what still offers upside?
- Can strategic reserve releases truly cap the rally, or do they just delay the adjustment?
- Equities have remained resilient. Are markets looking through the shock, or misreading it?
- Where is the tipping point: how much further can oil rise before equities reprice meaningfully?
- If crude continues higher, which sectors and factors offer the most convex exposure, not just beta?
- If flows normalize and oil rolls over, where does leadership rotate, and how quickly?