Corporate Bonds
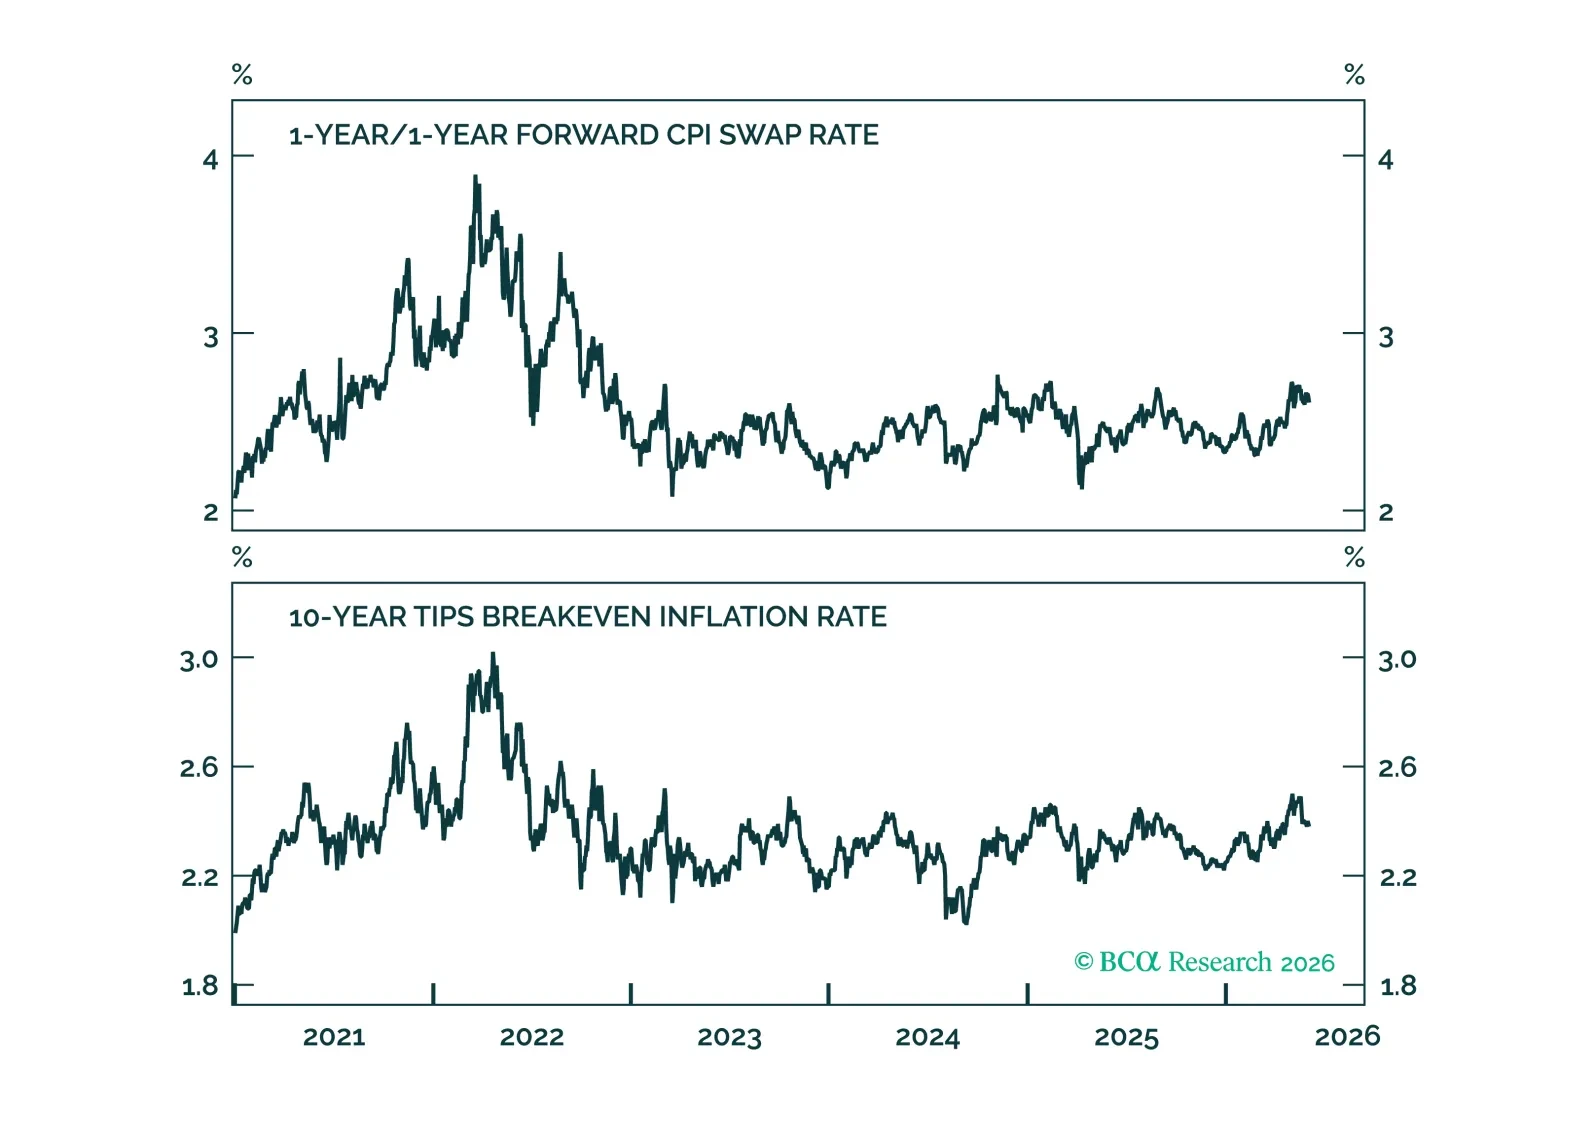
After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
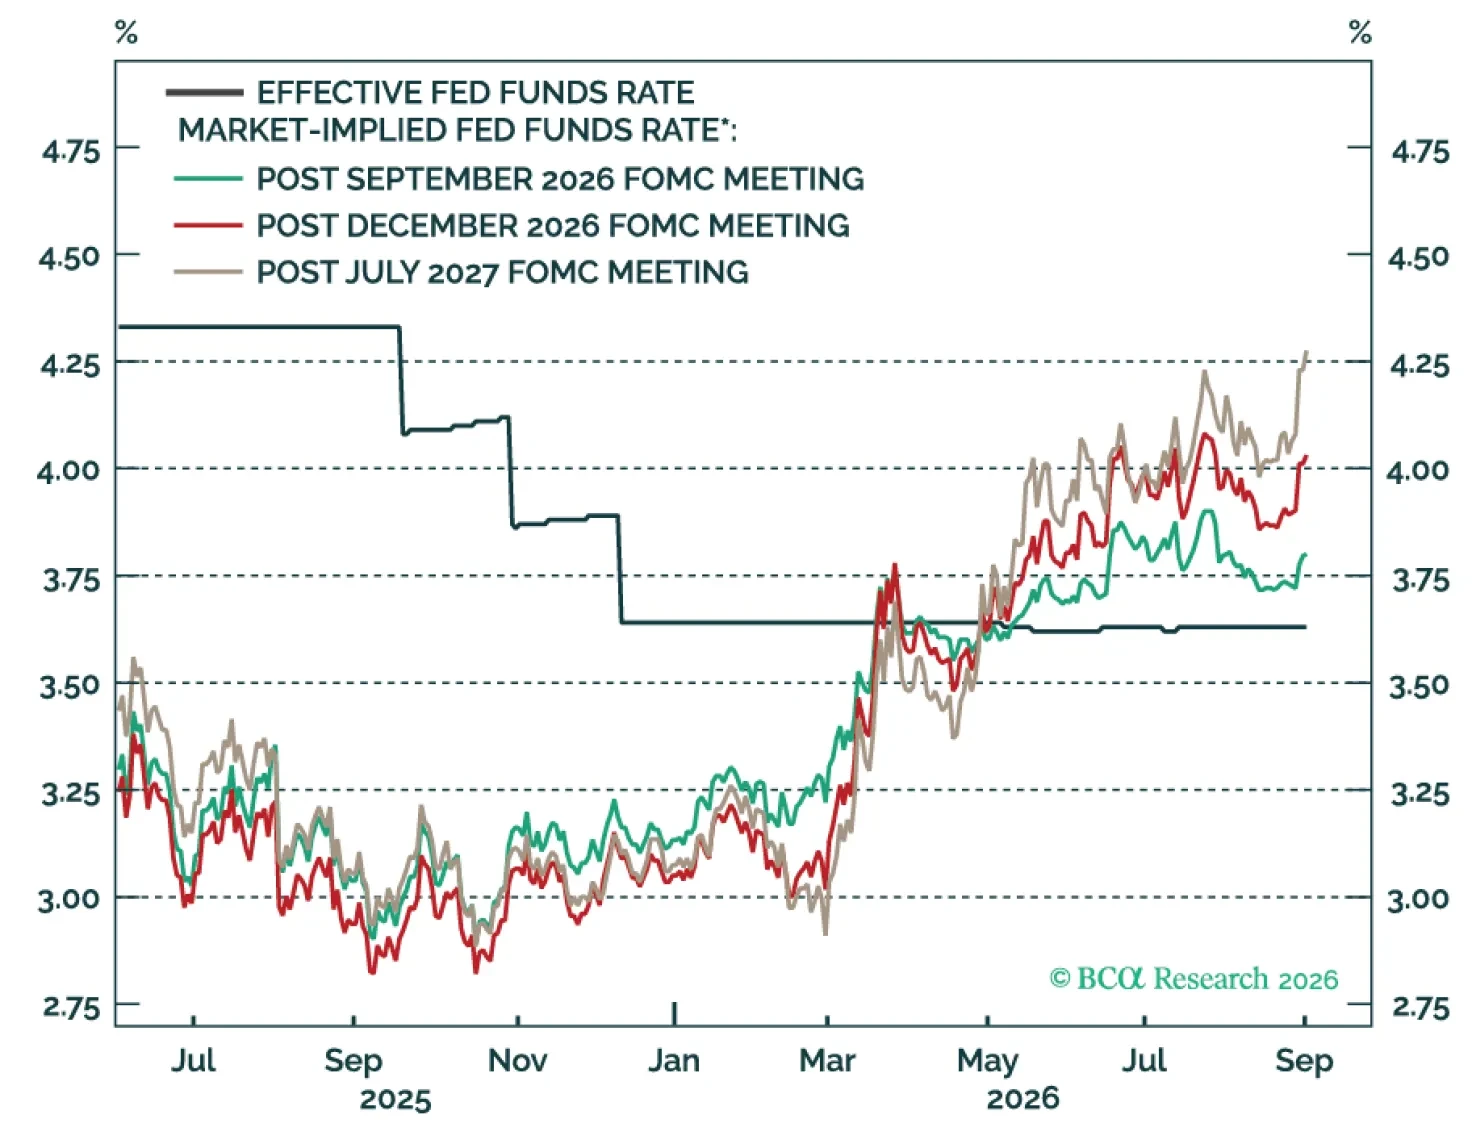
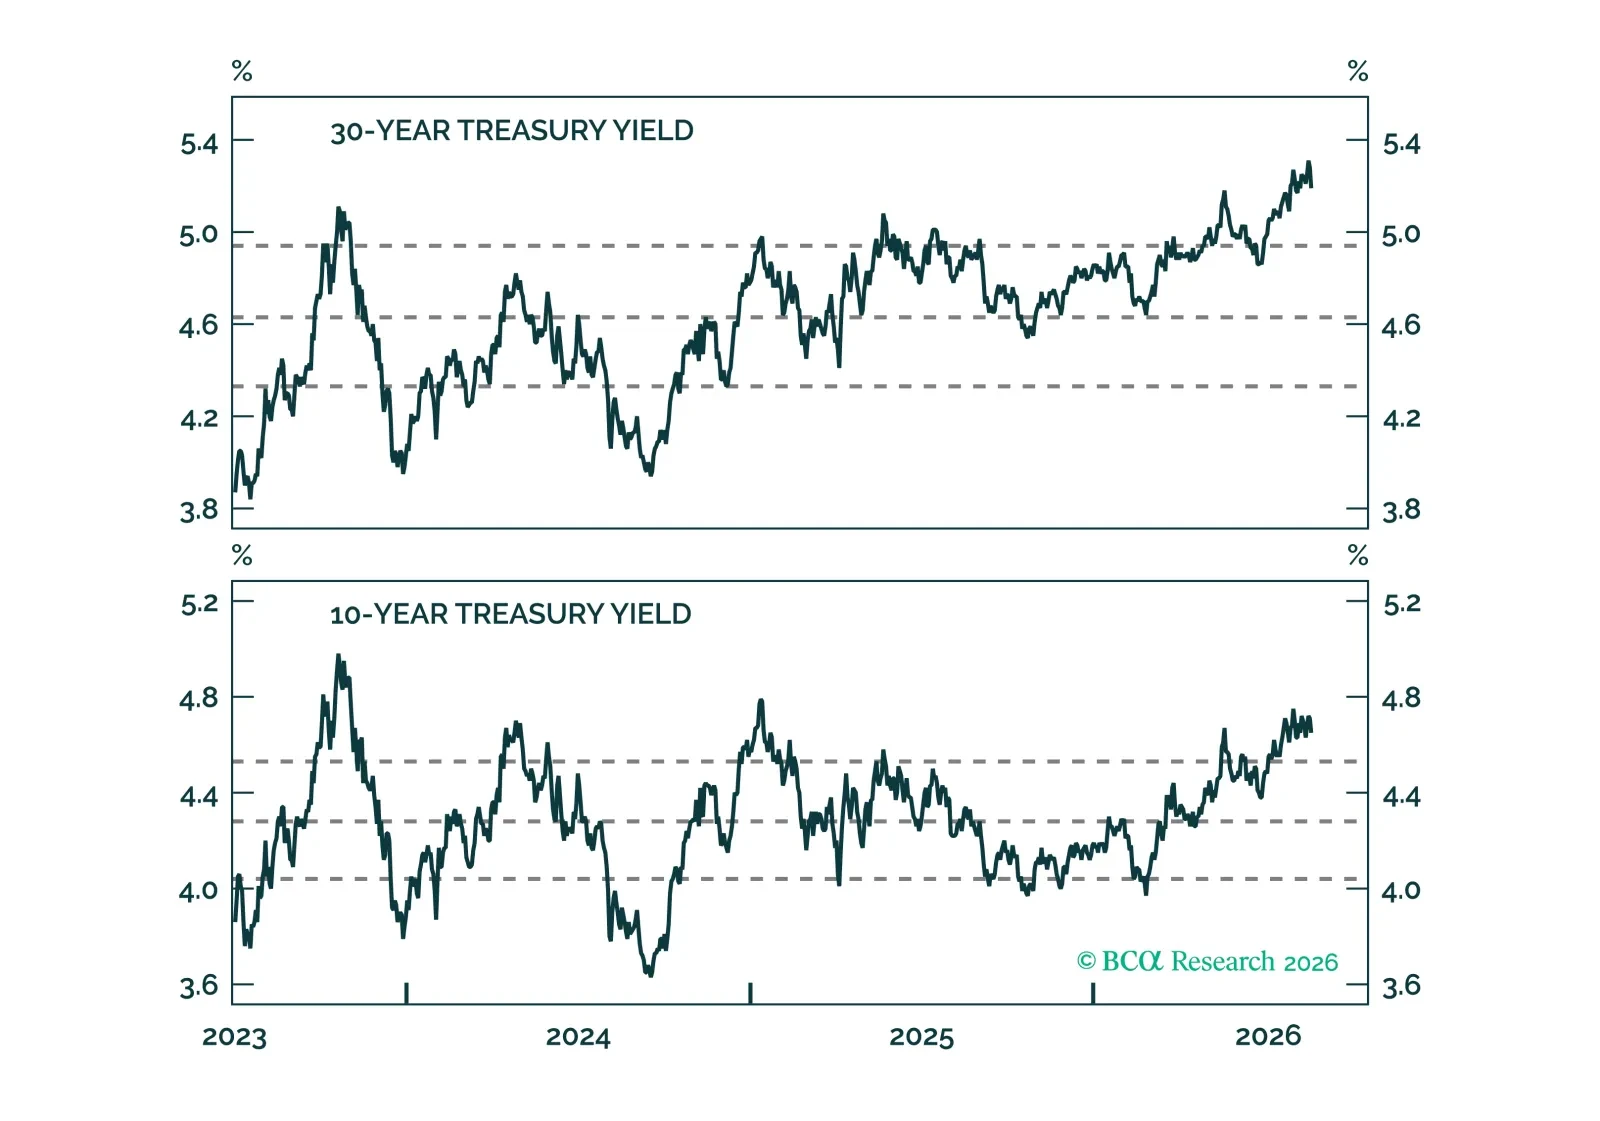
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
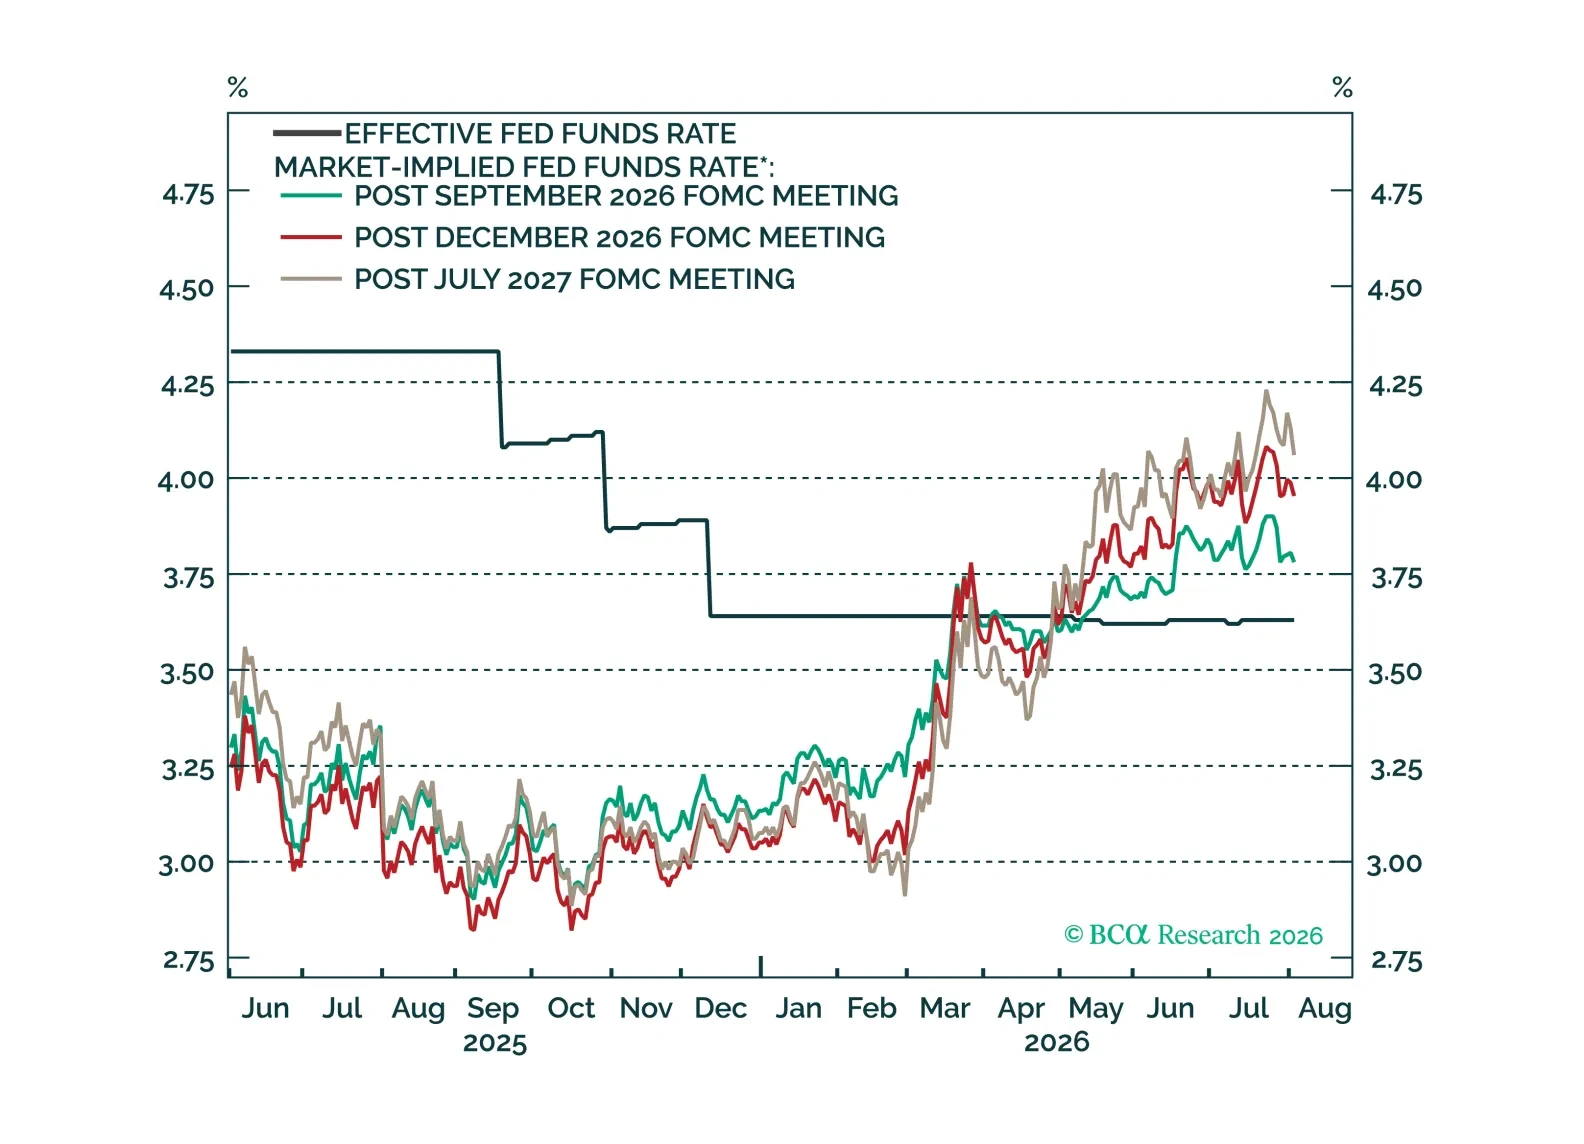
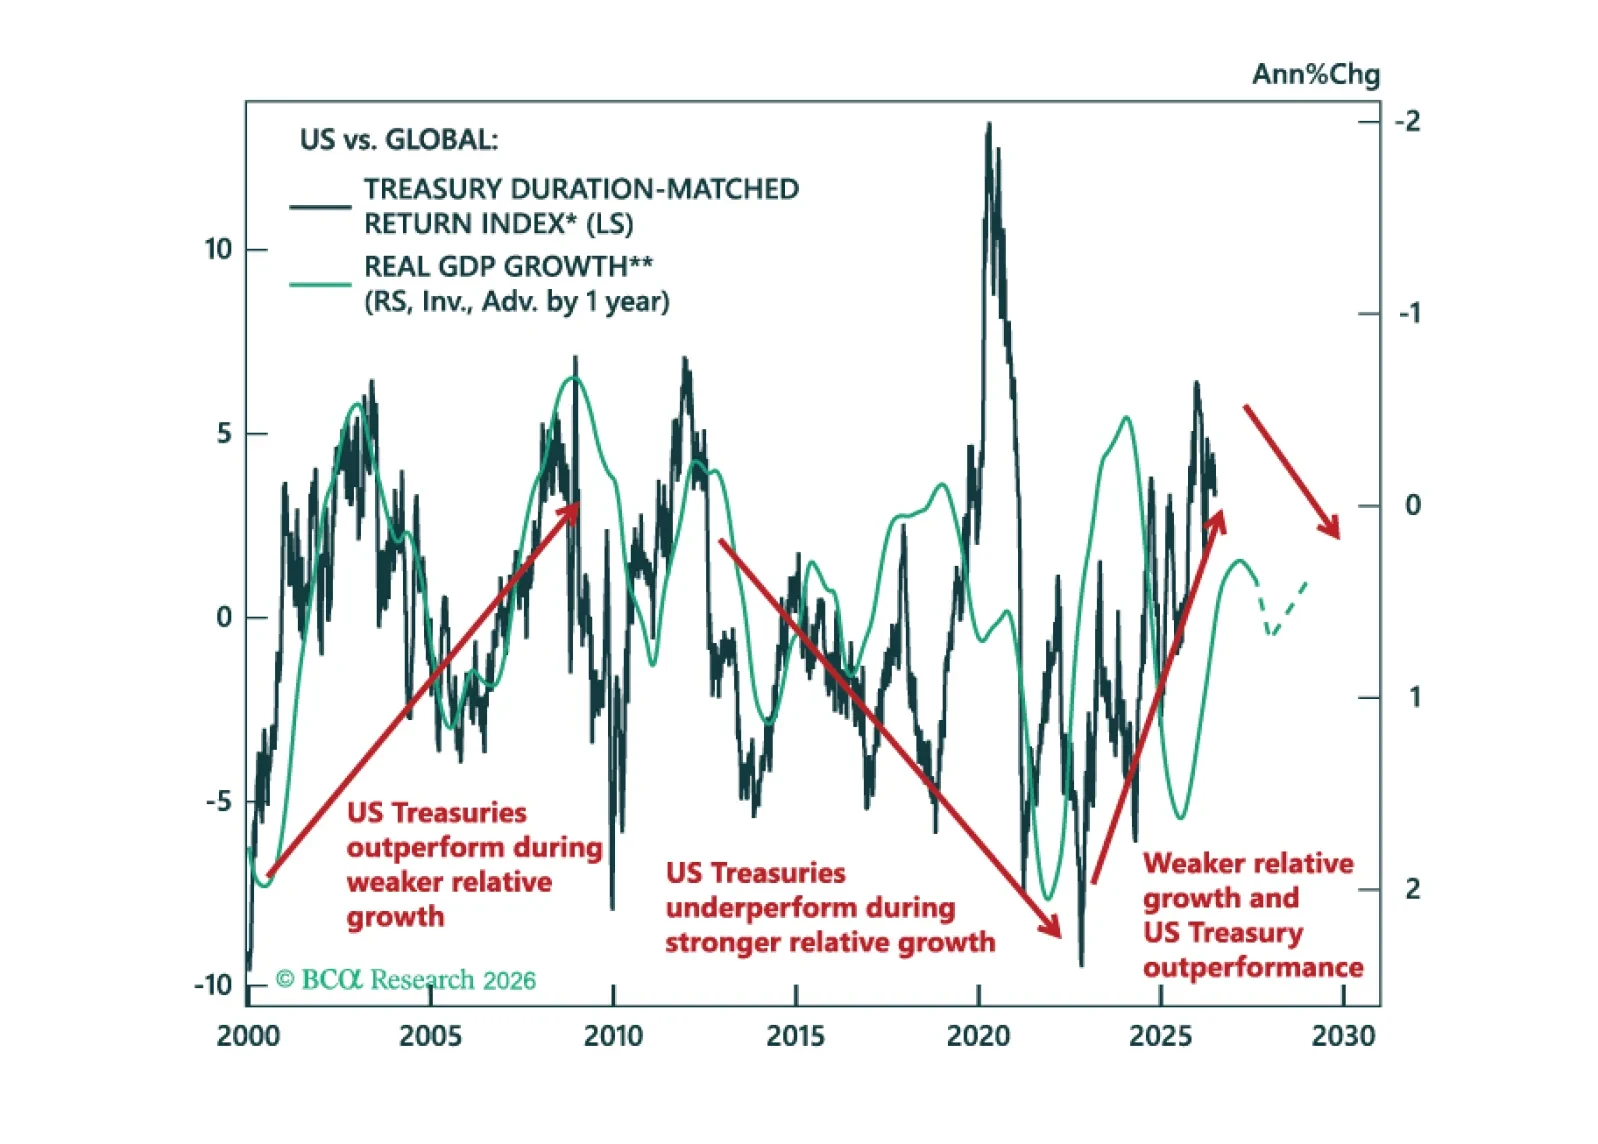
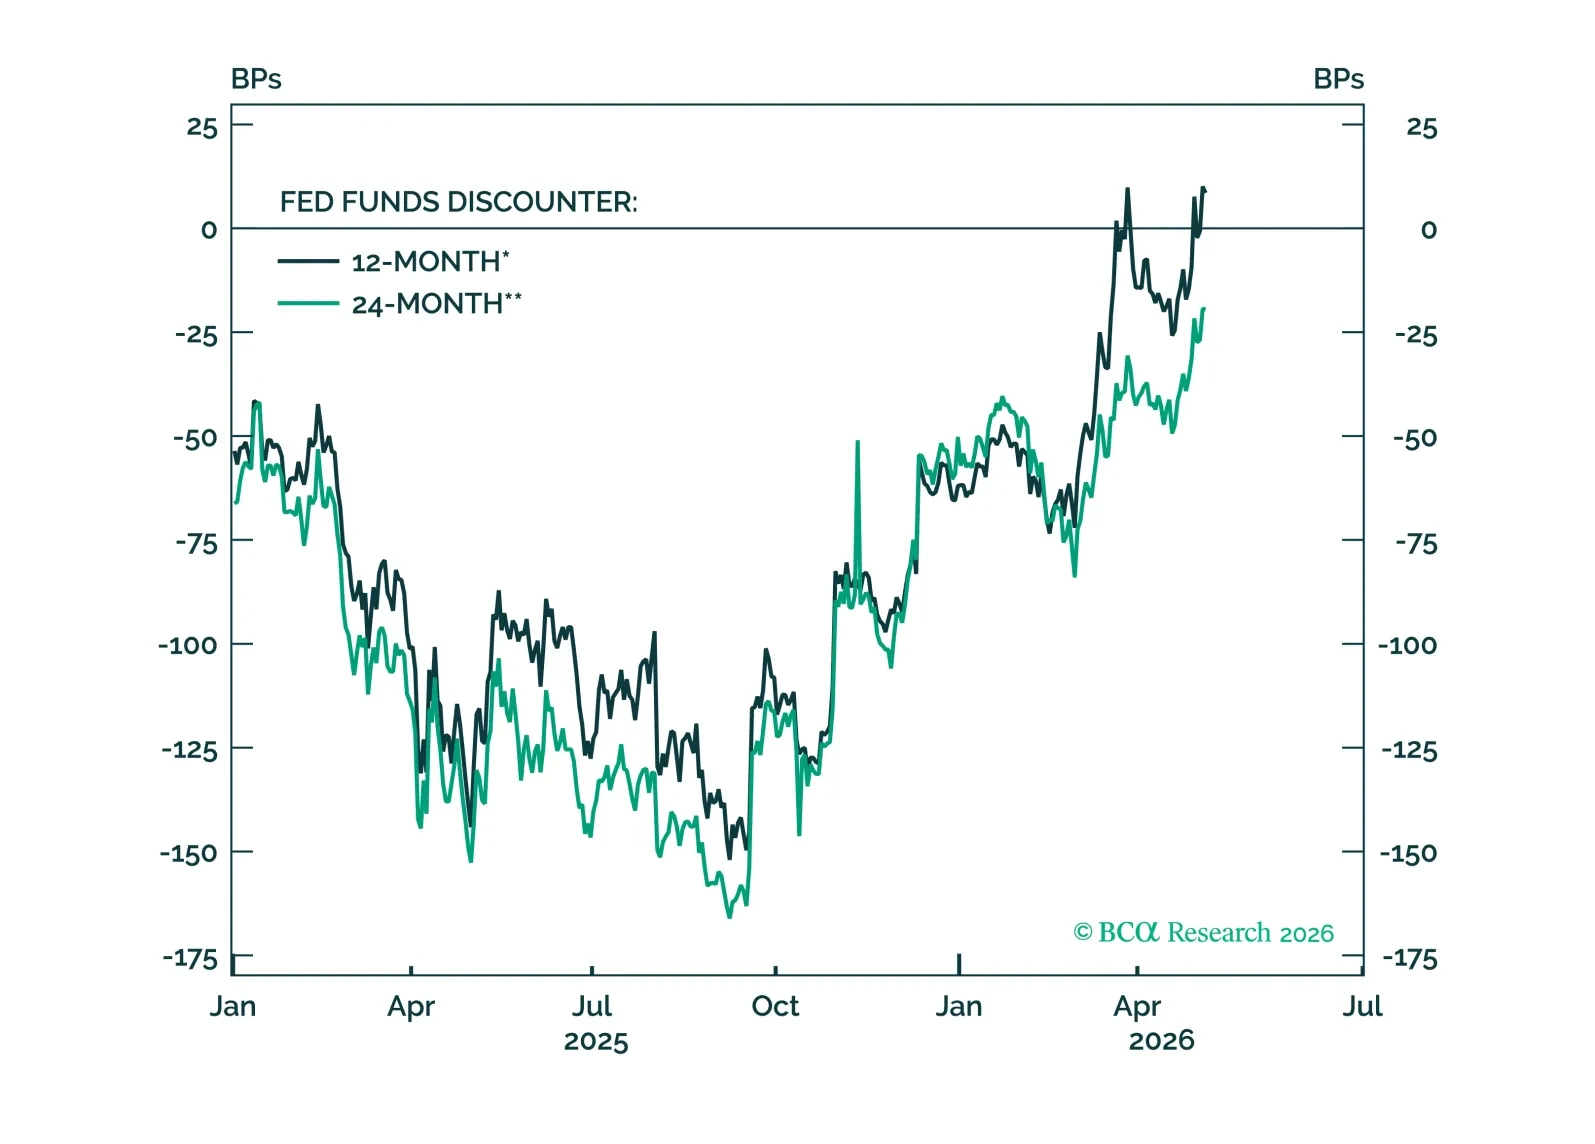
We review our Model Bond Portfolio performance for Q2 and look ahead as fixed income markets move beyond the US-Iran conflict, which is finding its kinetic equilibrium. Valuations and growth differentials are moving against continued US Treasury outperformance.
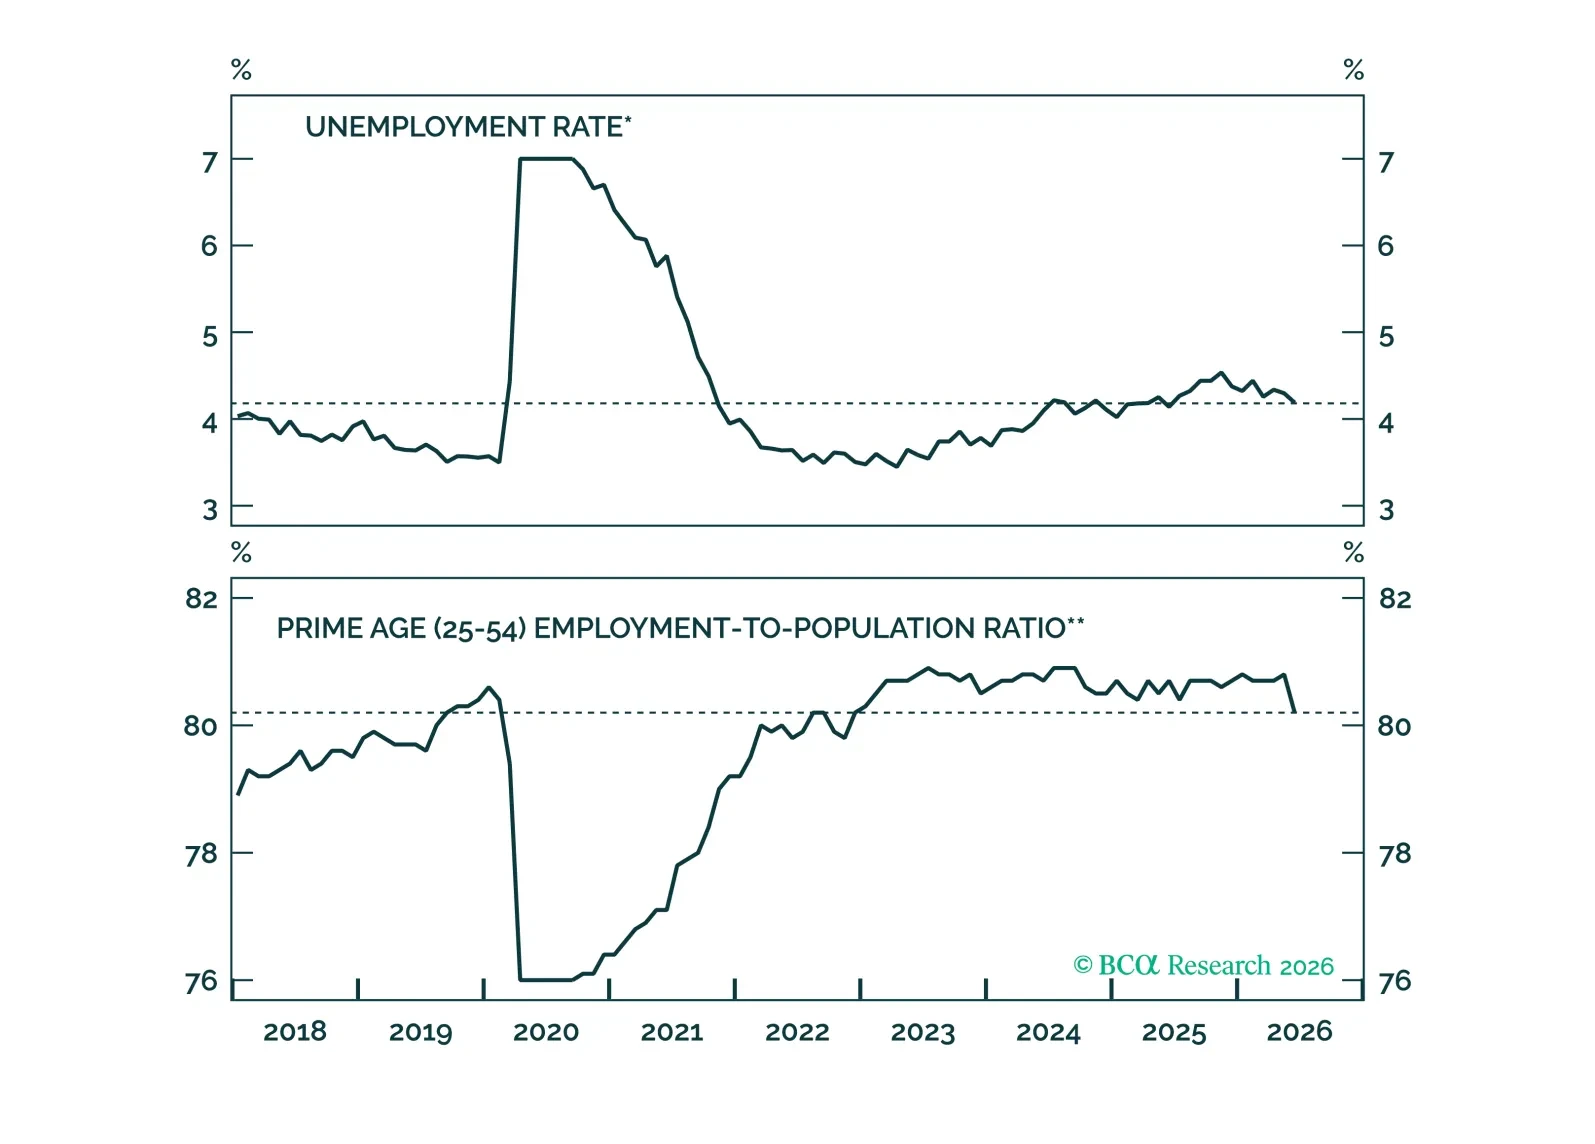

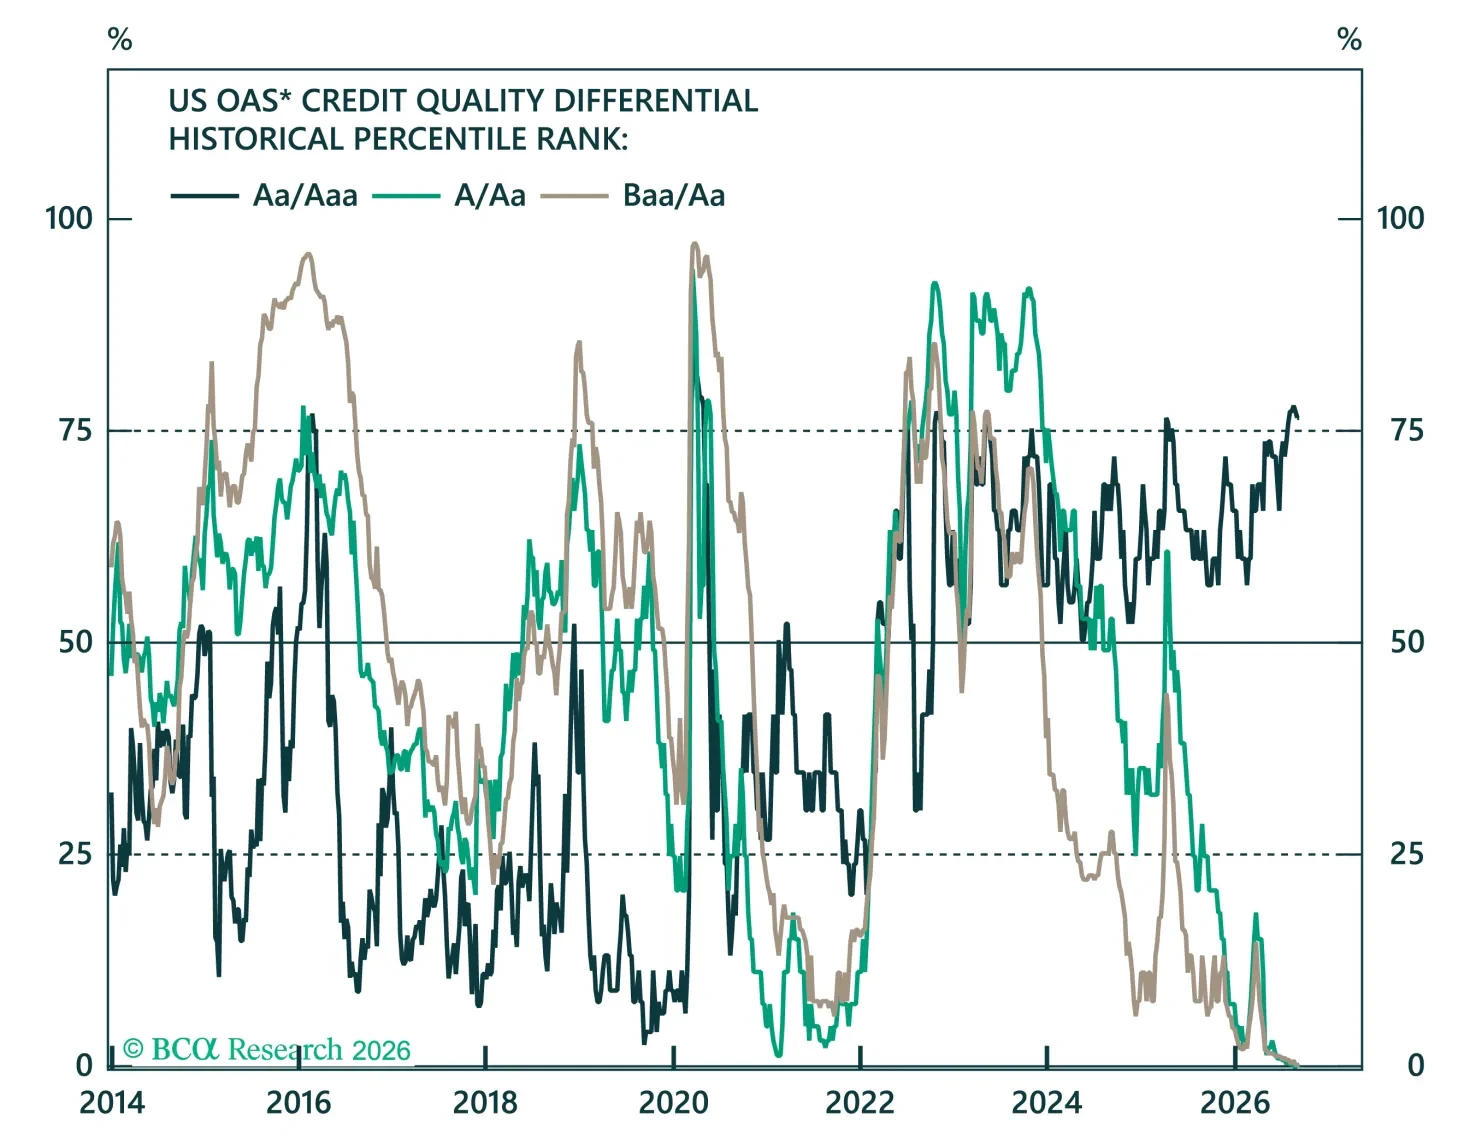
Corporate health remains supportive of tight credit spreads in both the US and Europe, but a growing divide is emerging beneath the surface. Investment-grade issuers continue to strengthen, while lower-rated borrowers face mounting pressures. Credit markets are pricing resilience, leaving investors vulnerable should corporate fundamentals begin to deteriorate.
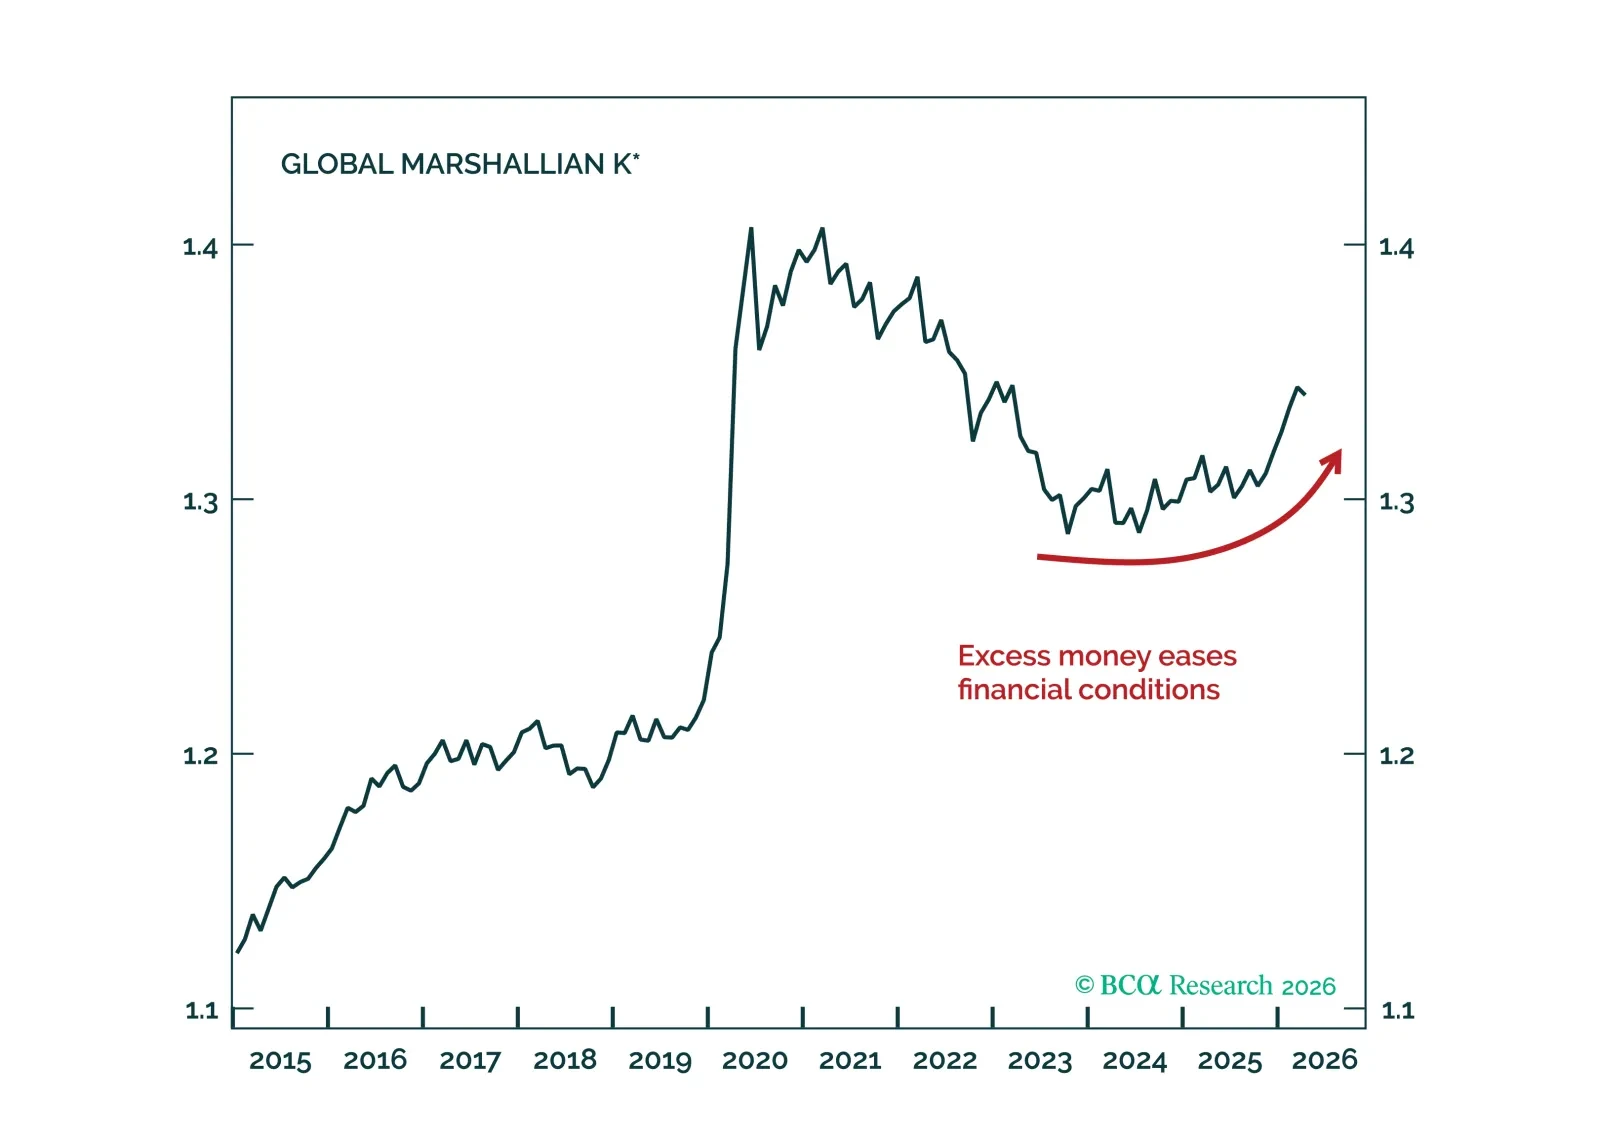
Markets keep buying the dip because liquidity remains plentiful. That buffer lasts through 2026; the bigger question is what happens when it thins in 2027.