Iran
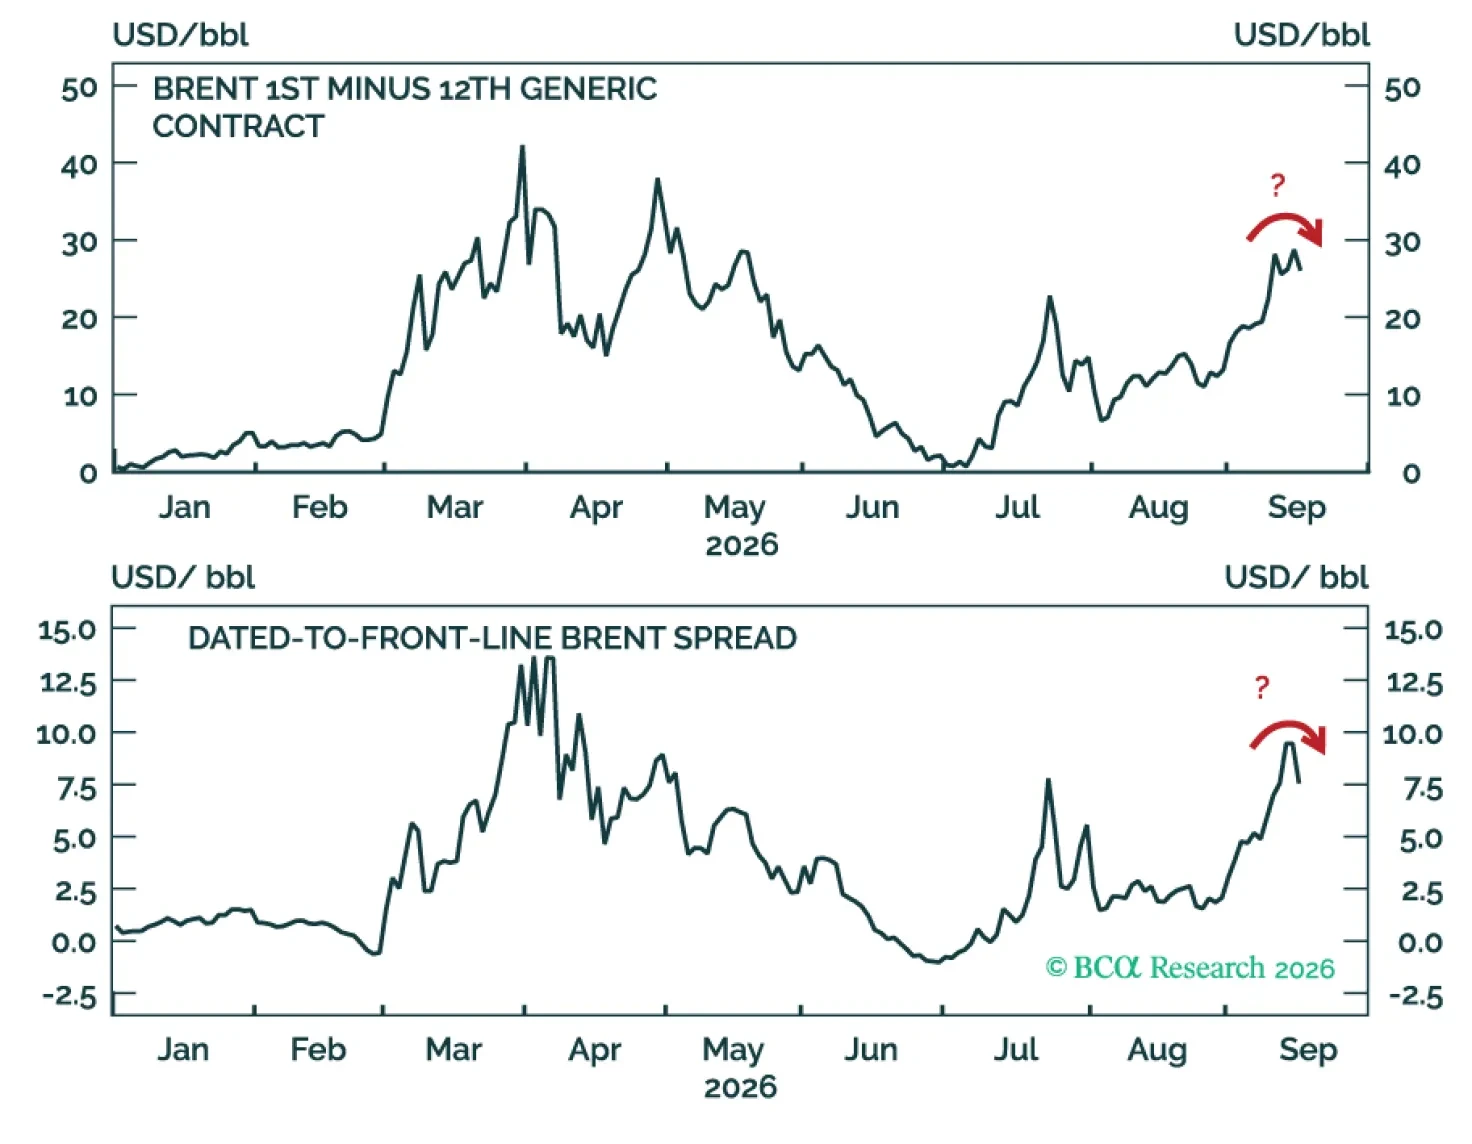
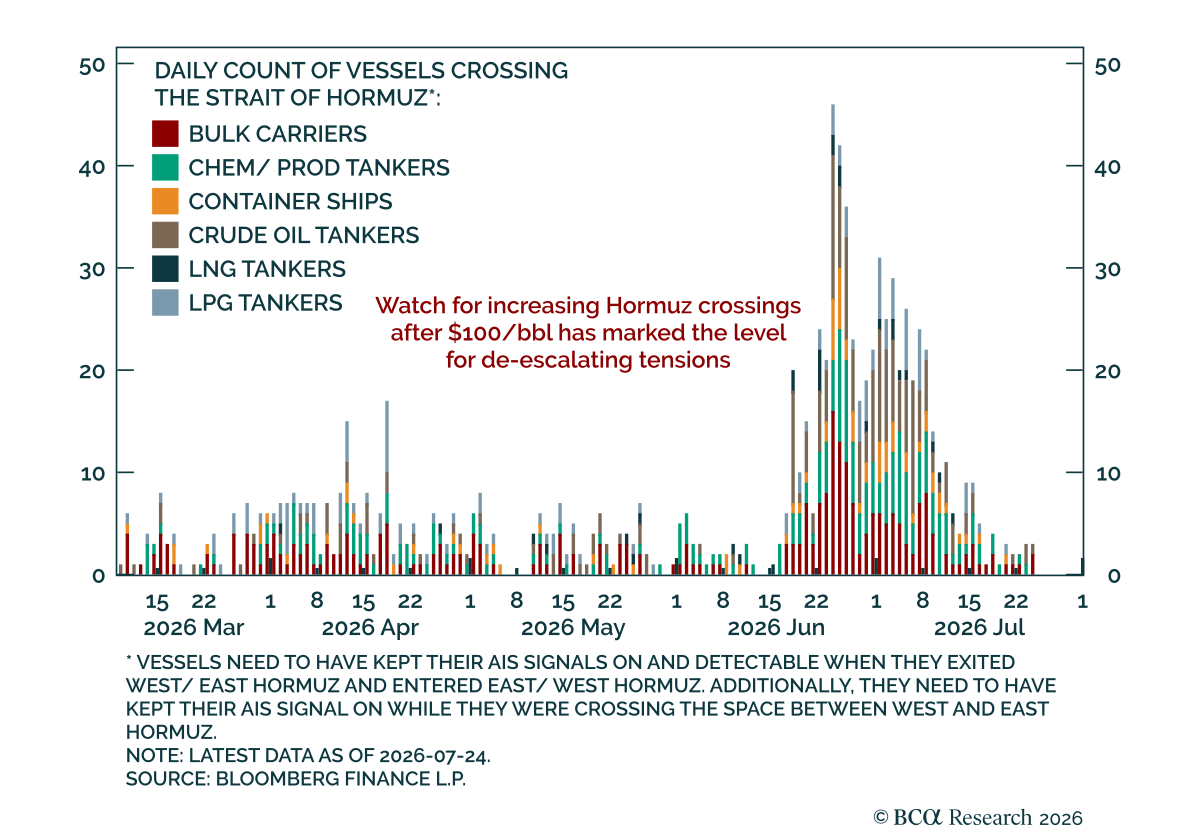
Recent oil market developments expose the limits of the adjustment mechanisms that have cushioned the global market since the Hormuz closure began. Fortunately, Hormuz dark transits have become the dominant shock absorber in recent months, and rising flows should help mitigate the latest supply disruption going forward.
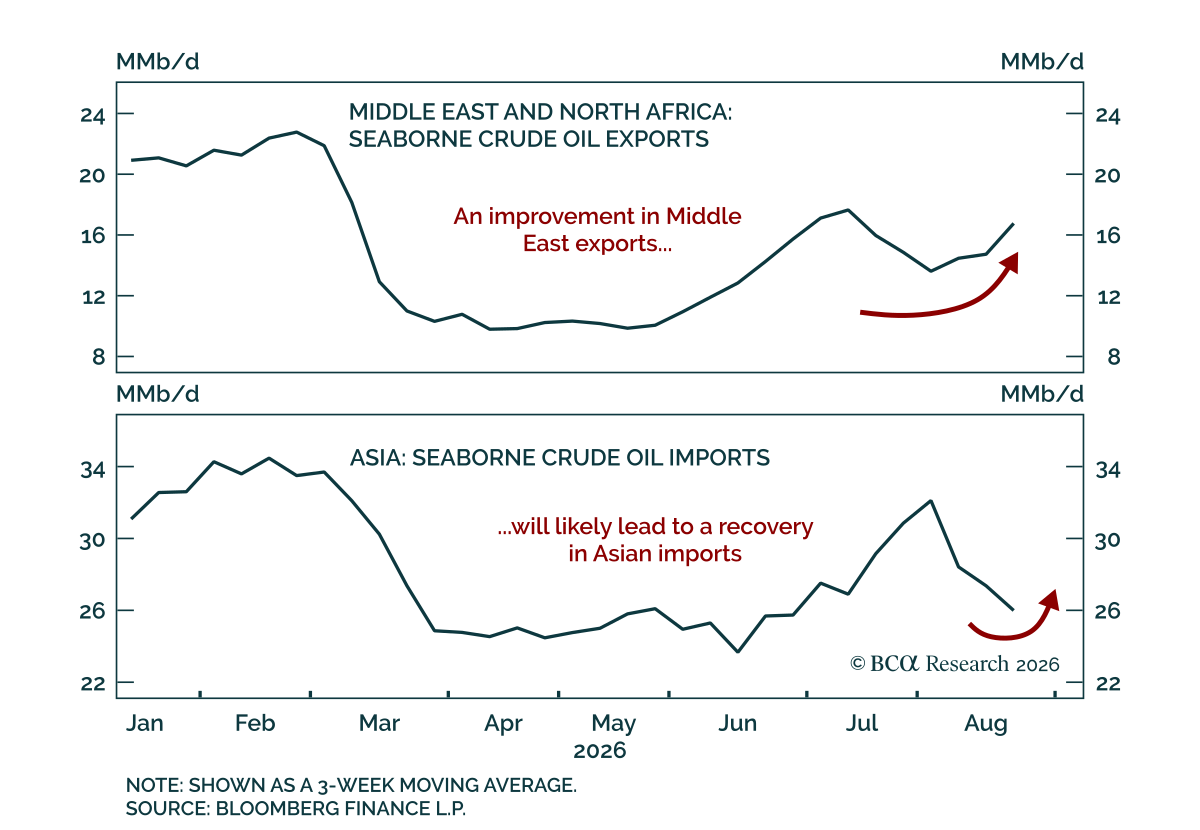
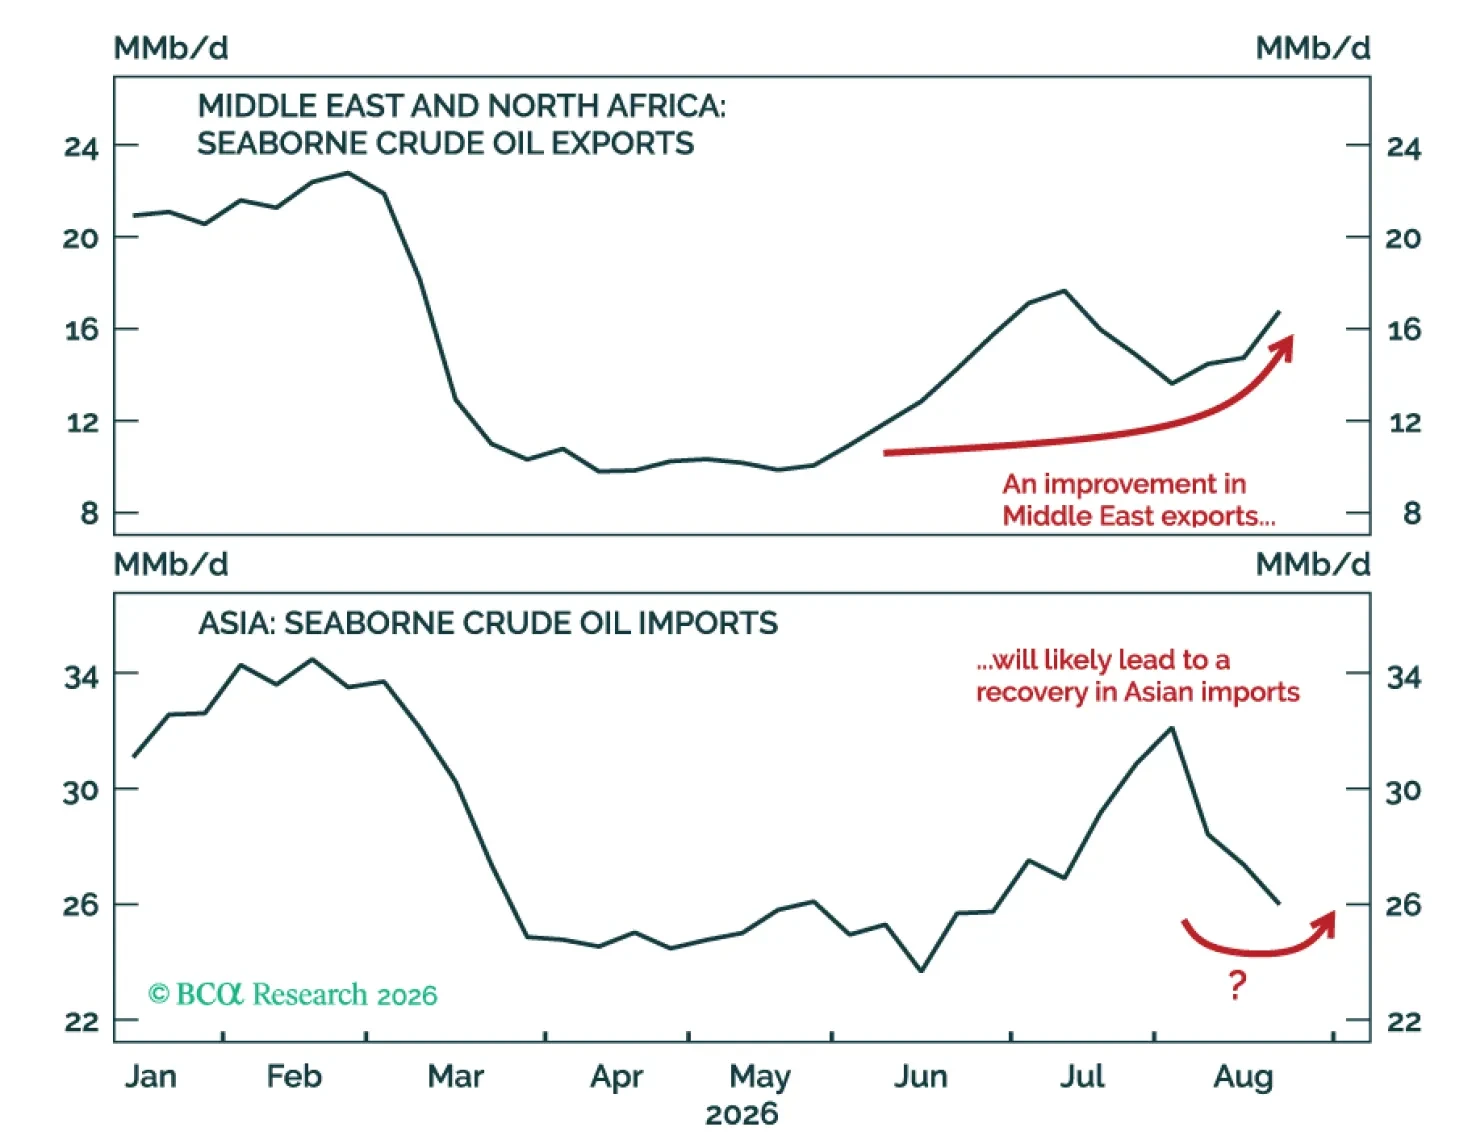
The wide crack spread reflects a bifurcated oil market. The severity of the crude oil disruption has recently softened, while the US-Iran and Ukraine-Russia conflicts have created a perfect storm for refined product markets. Going forward, even though conditions are not yet in place for the crack spread to return to its pre-conflict level, it is likely to narrow over the coming months.
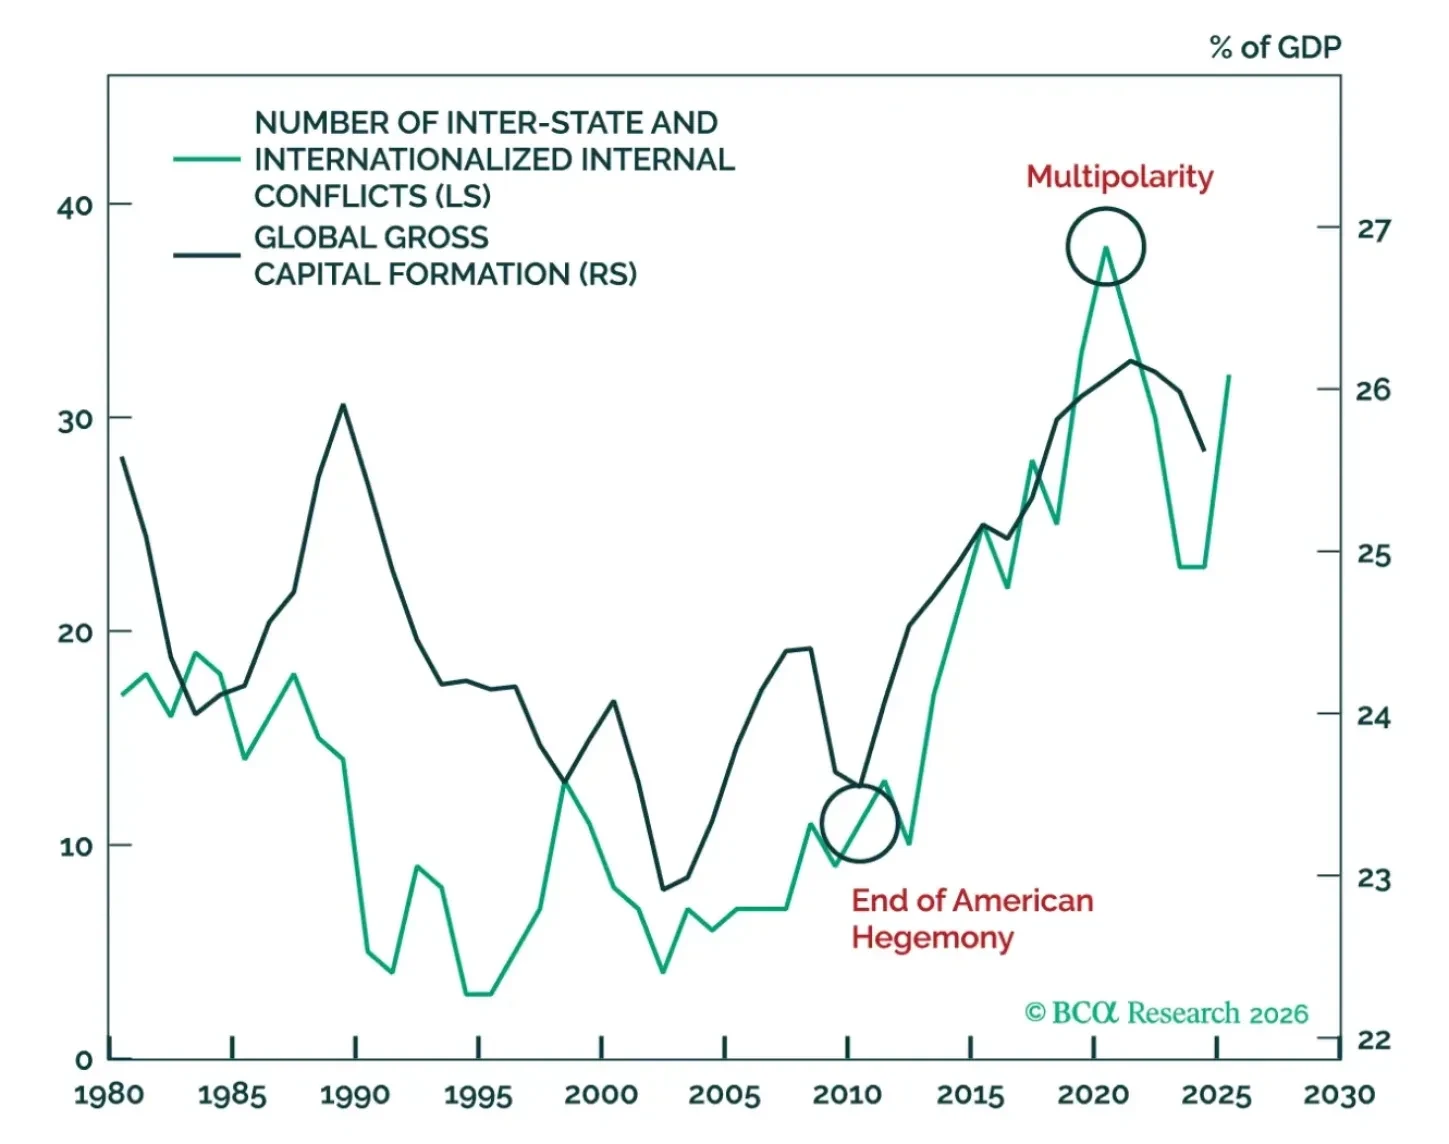
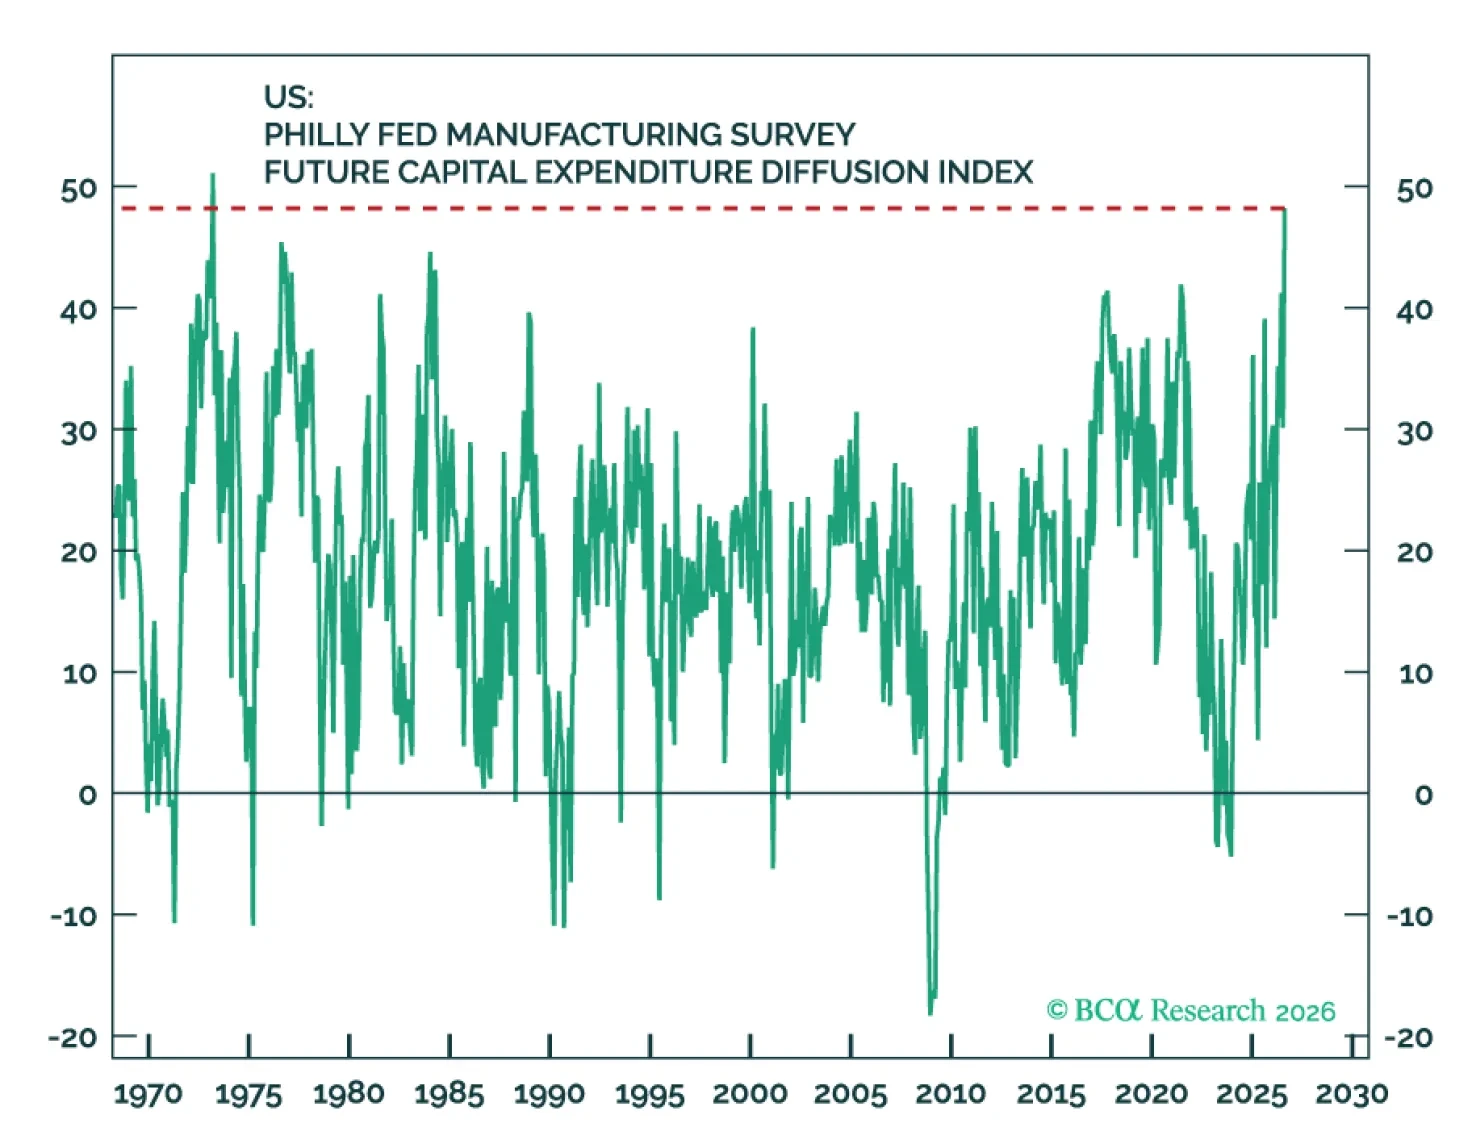
Many clients have asked us for an analysis of the long-term implications of the Hormuz Crisis. In this report, we posit that the conflict has been catalyzed by the multipolar context and that it will merely ossify the trends already afoot. Nothing offers incentives for more global capex like the threat of losing a critical energy supply chain. Therein lies the paradox. While capex is mildly inflationary in the short term, it is wildly disinflationary in the long term. This may be a worthwhile insight given all the consternation about long-dated bonds at the moment.
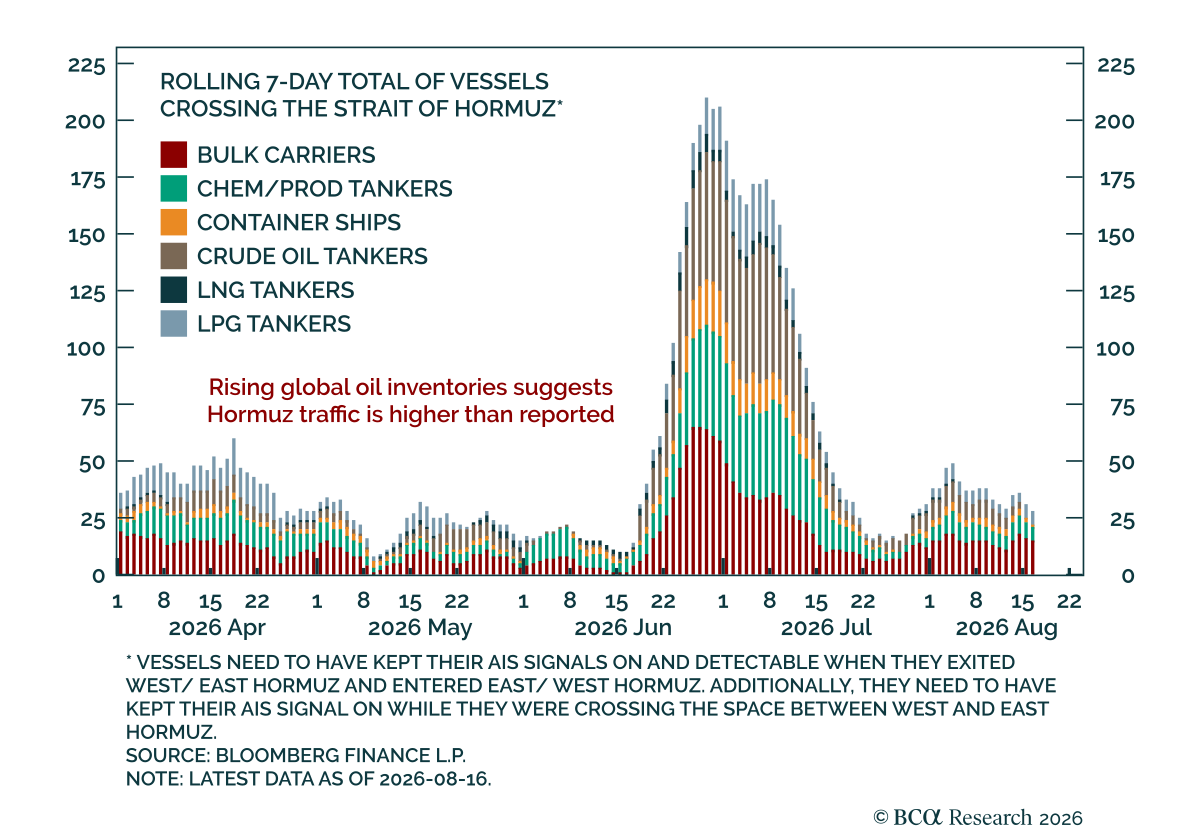
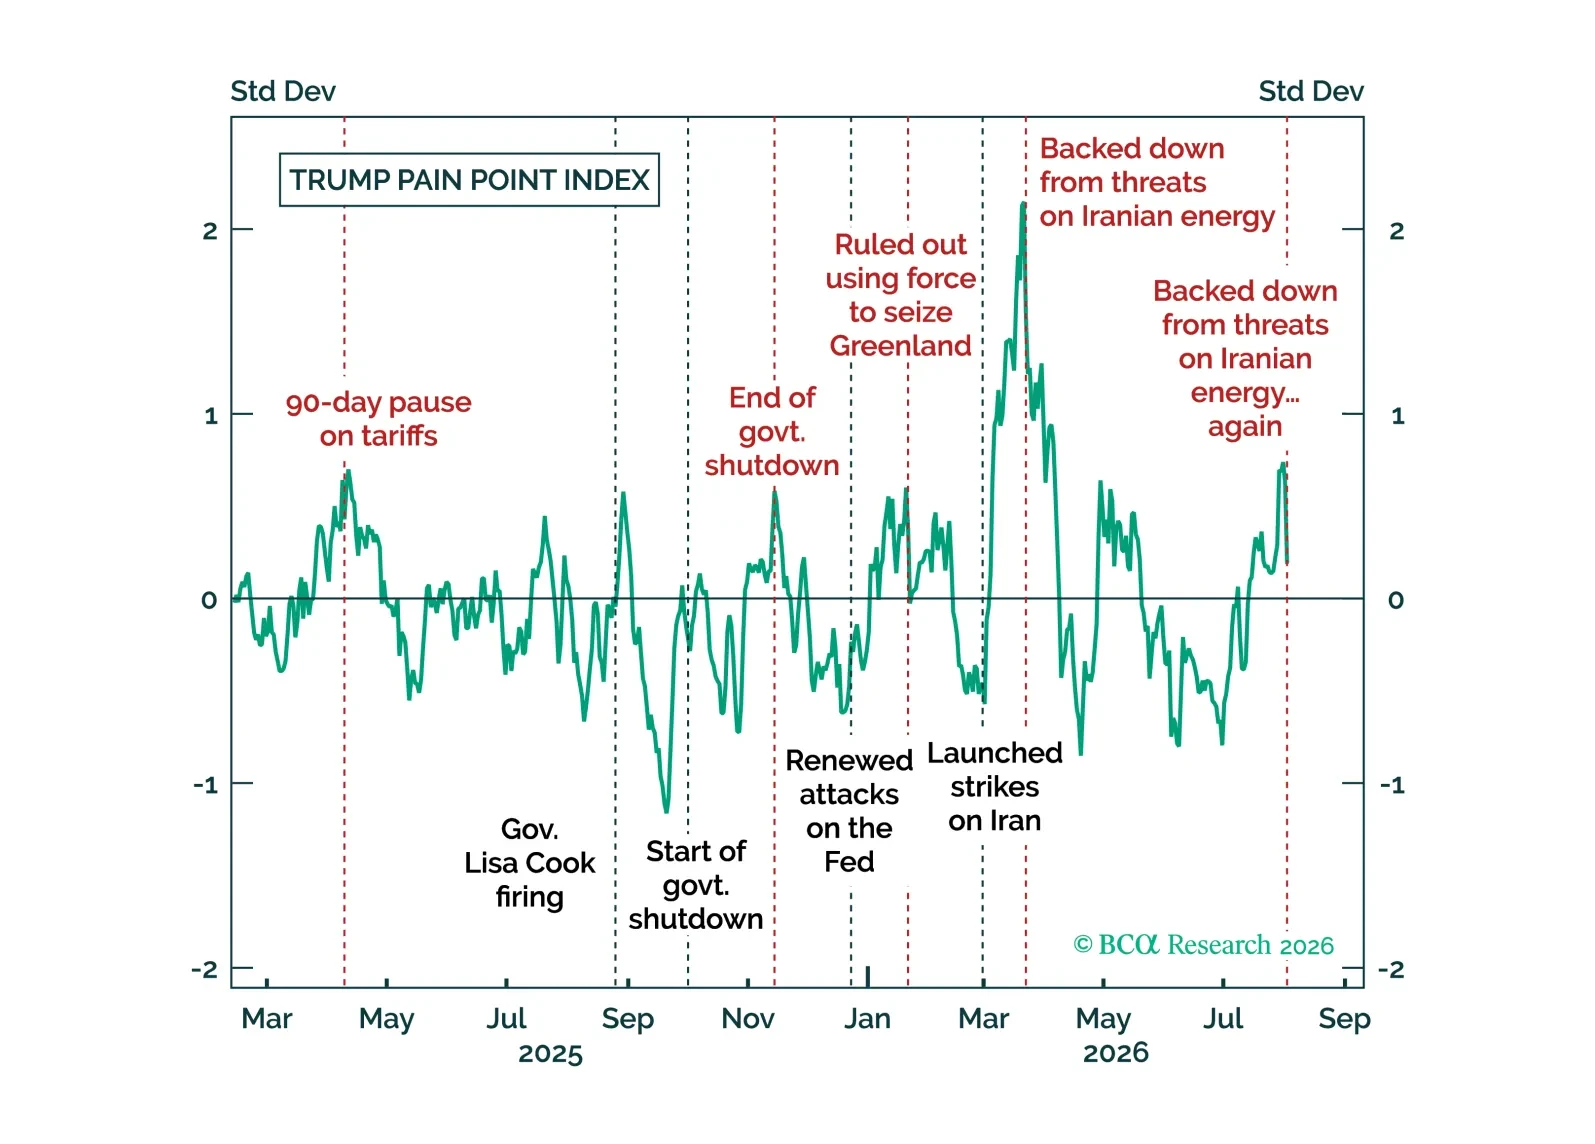
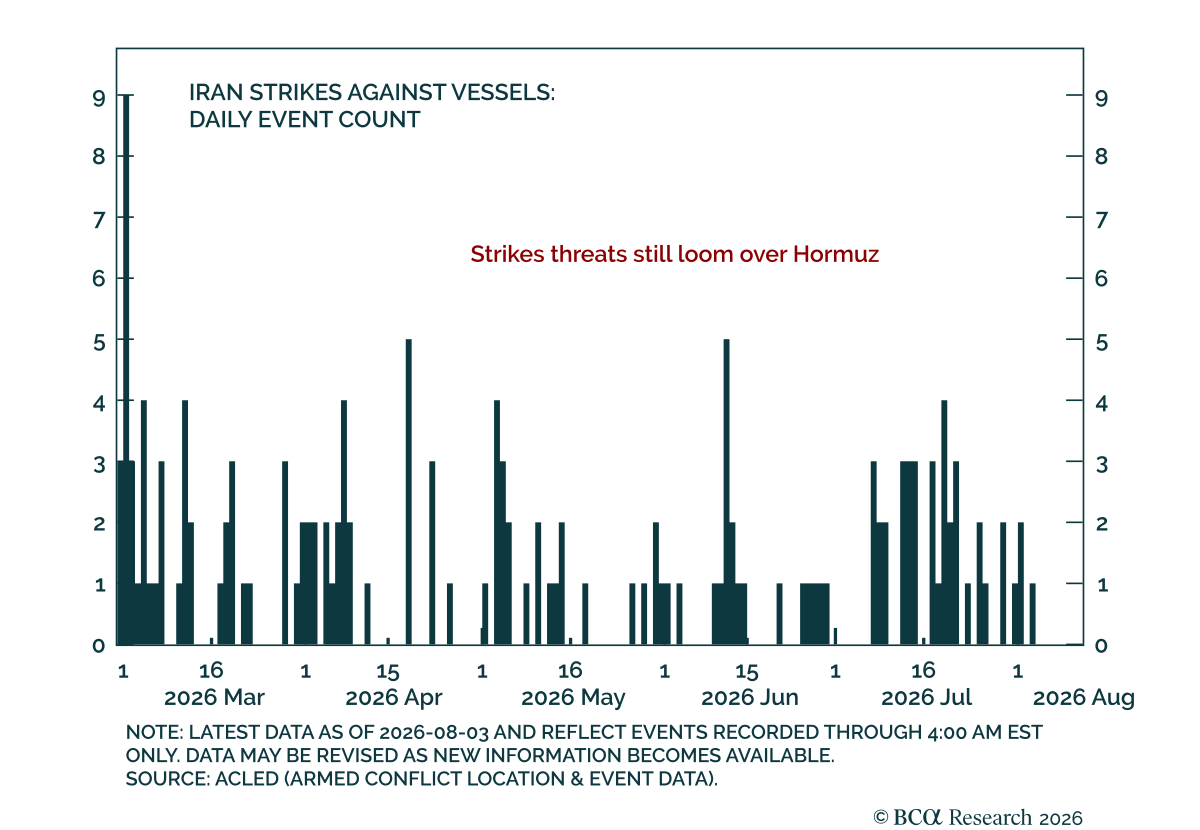
Last month we "stuck our neck out" and reaffirmed our bullishness towards risk asset. This month, we have confirmation that the risky bet is paying off. Iran and the US remain materially constrained from total war. The AI capex thesis is holding up and slowly mutating into a price war that will only boost adoption and necessitate more investment. We open a new AI-related trade (long hard disk makers) and go long gold.
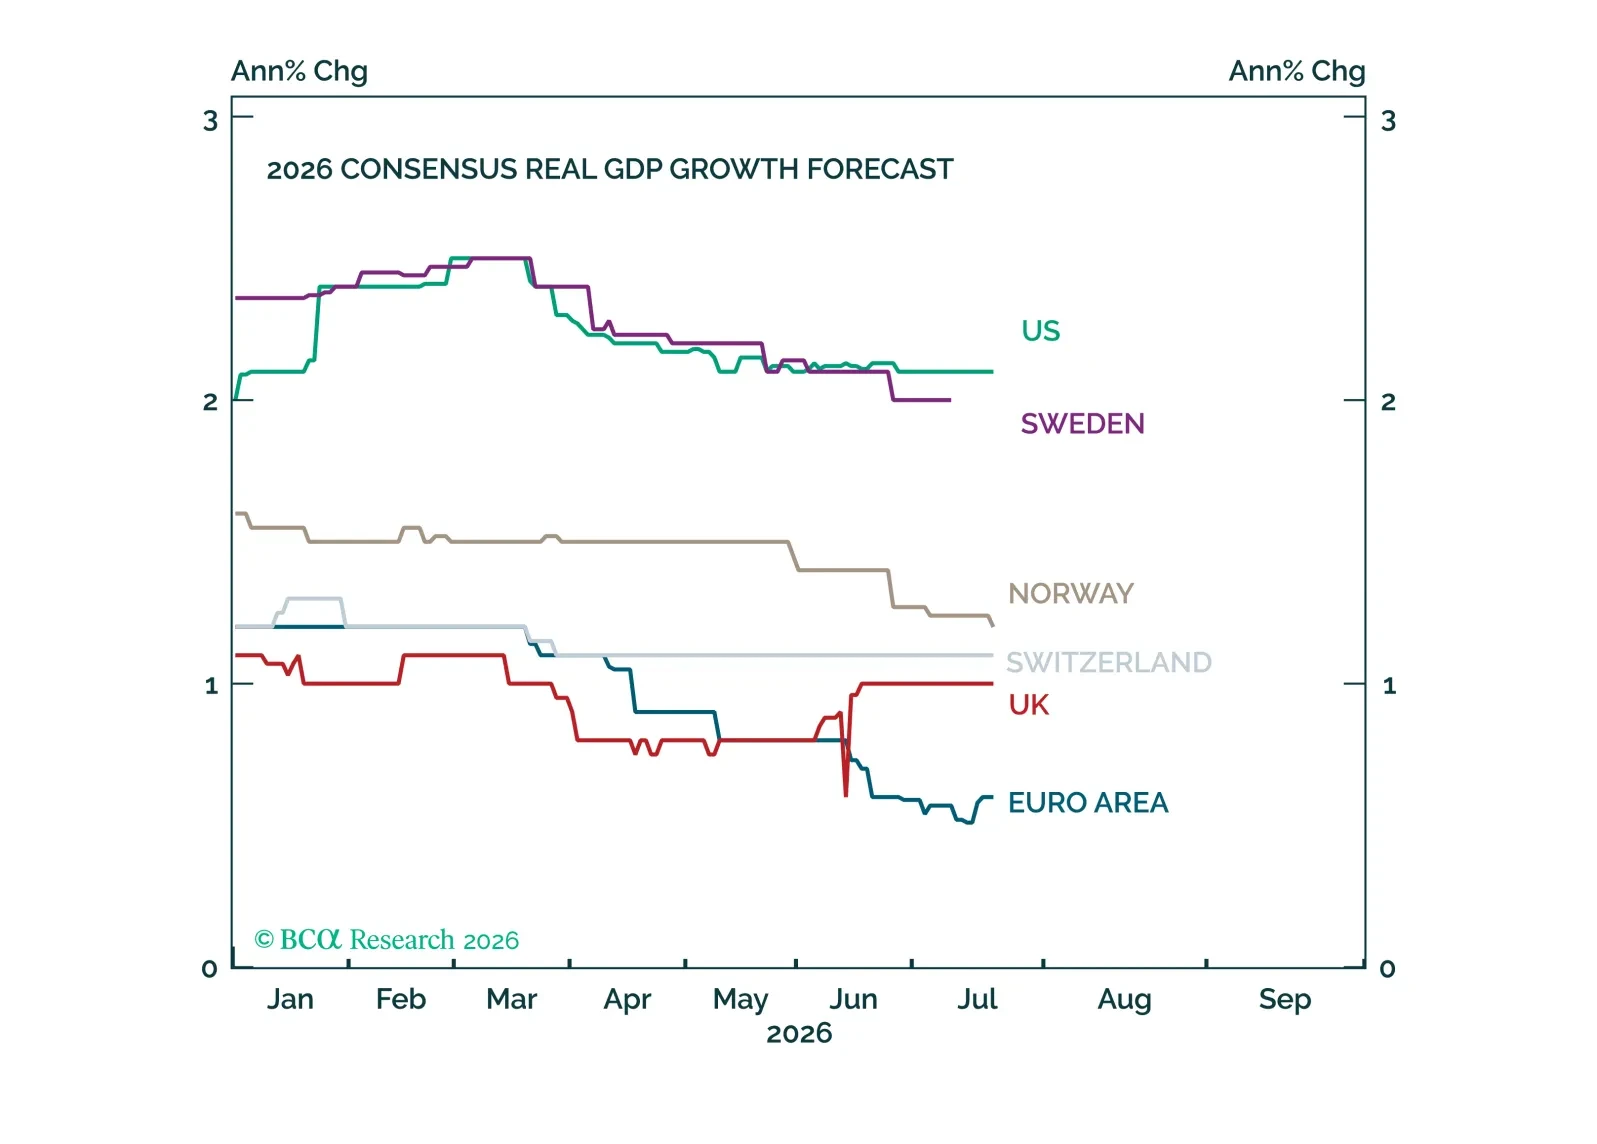
Europe faces a difficult macro backdrop, but whether it slips into recession remains finely balanced. We present two perspectives before translating them into investment implications.