Tariffs
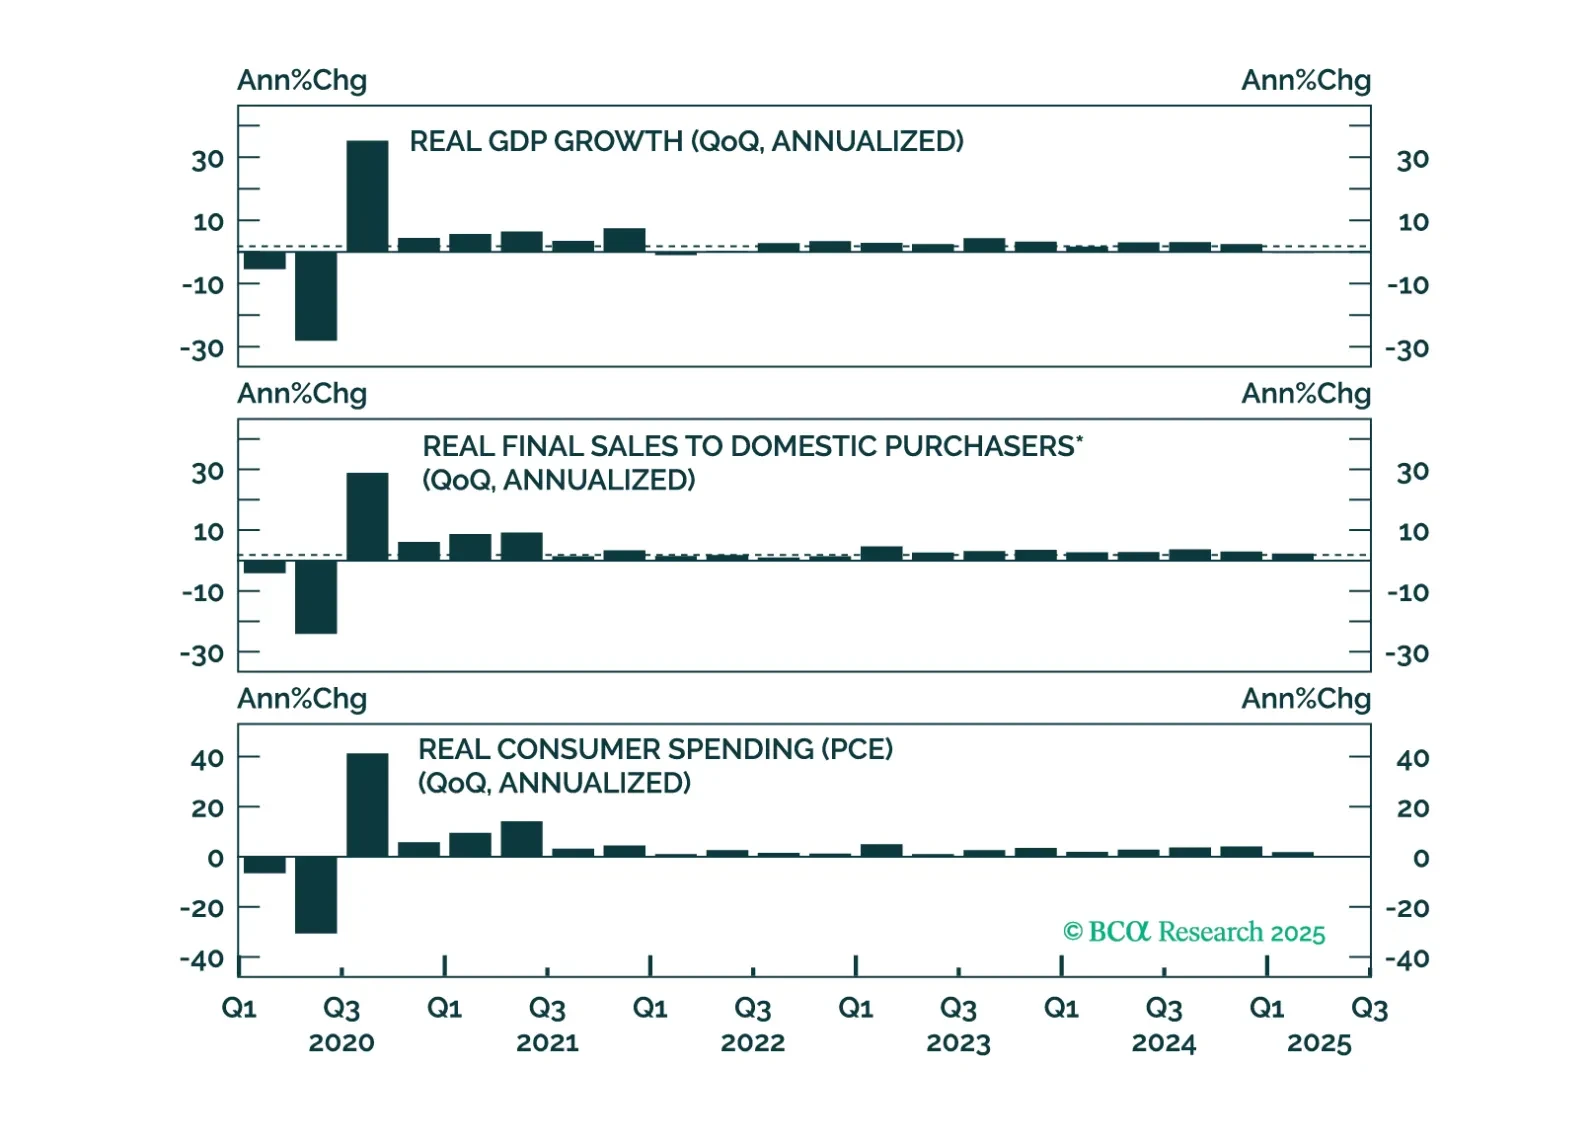
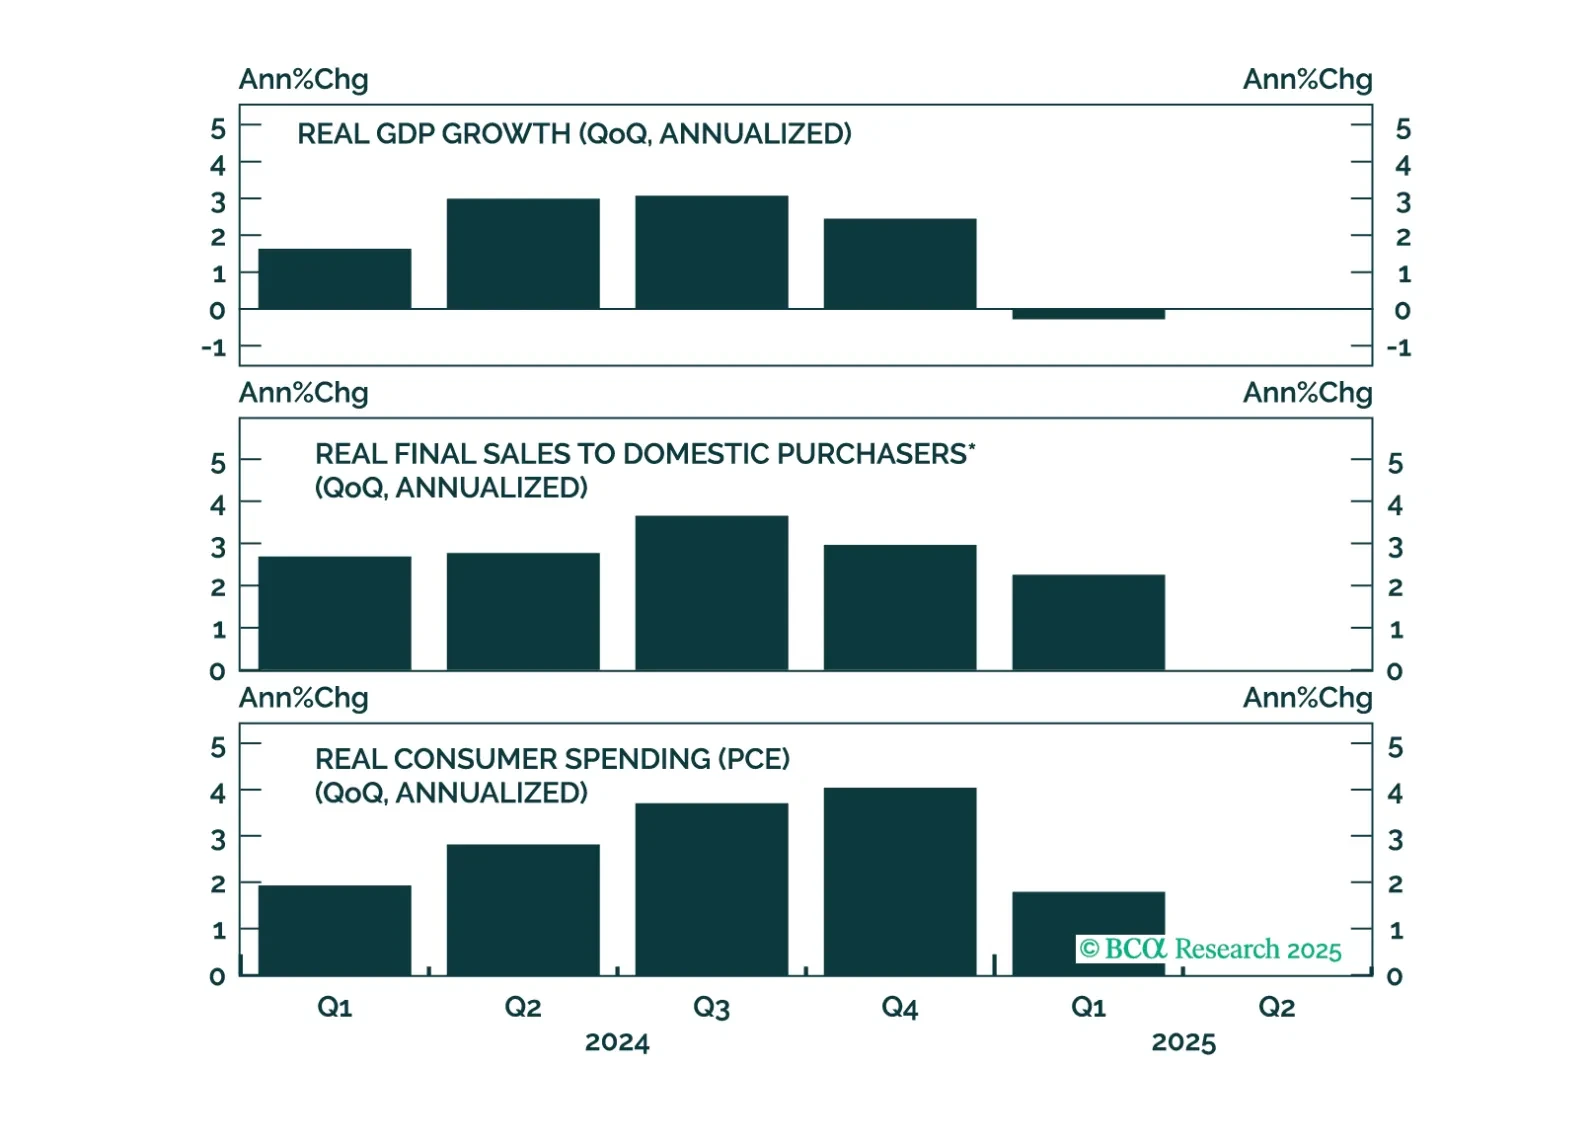
The Fed held rates steady this afternoon, and the timing of its next move will be dictated by whether the tariff shock to inflation is transitory or more long lasting.
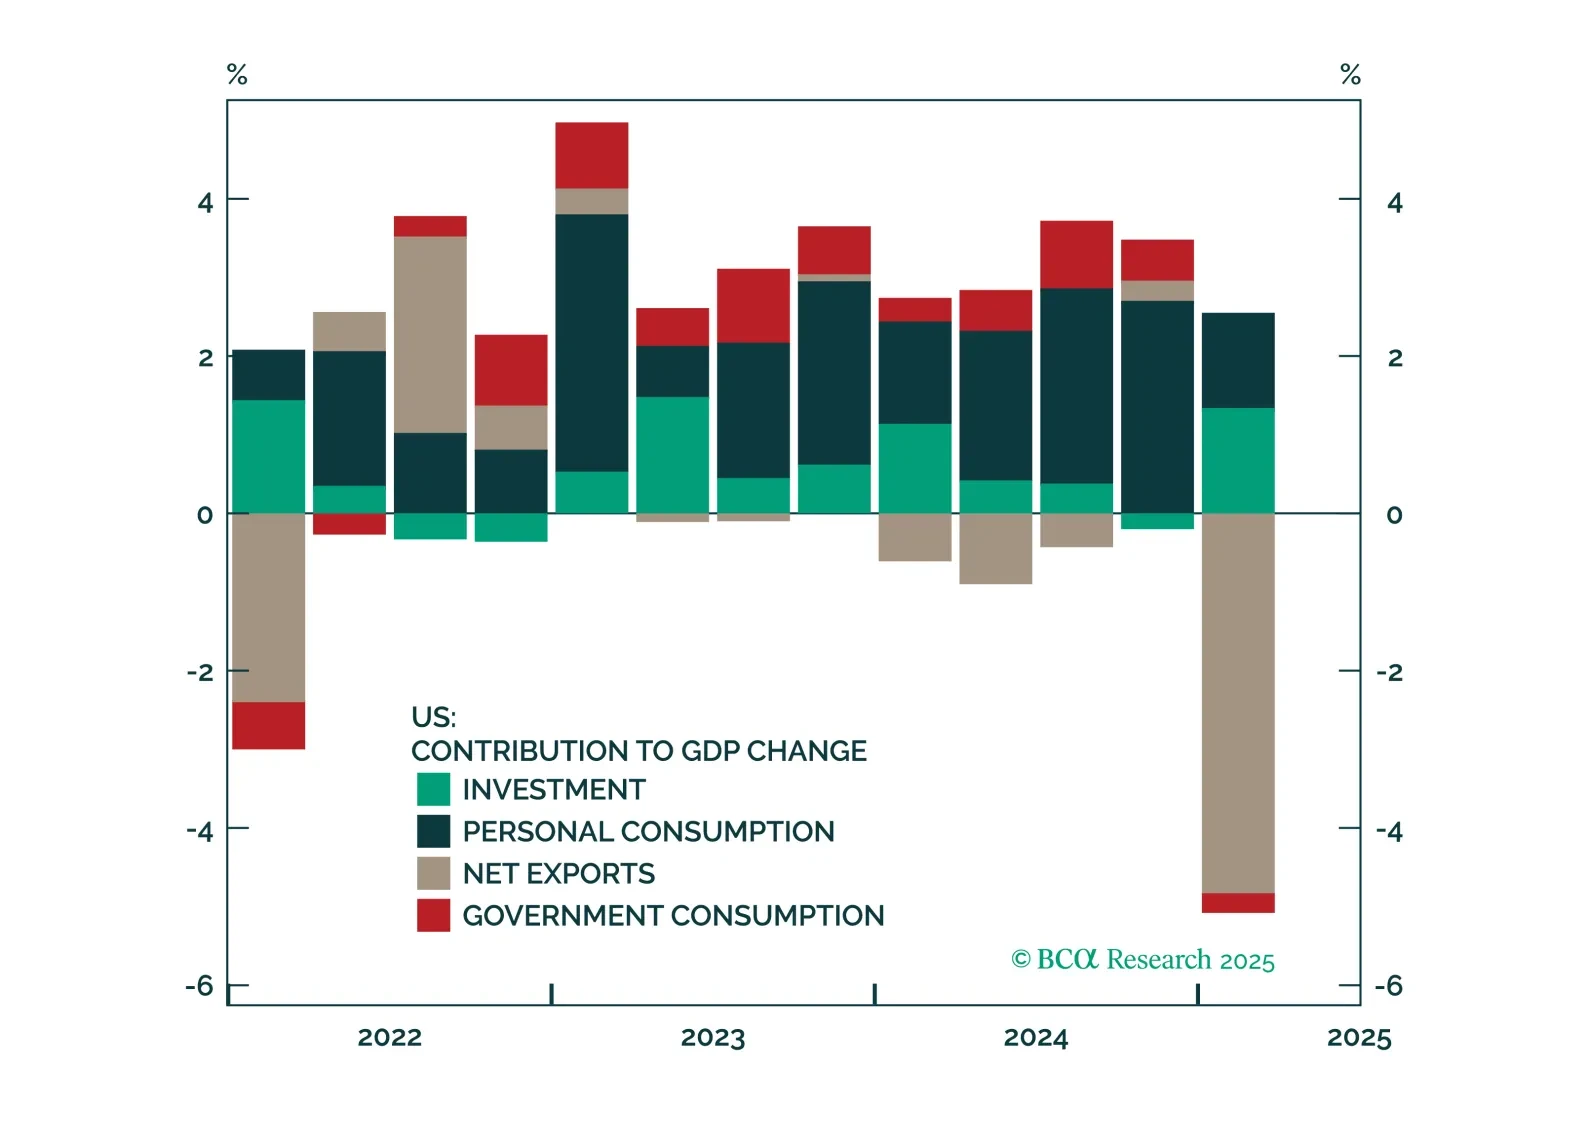
Negotiations on trade, Iran, and Ukraine will prove critical this month. Markets will remain volatile because positive data surprises enable the White House to press its hawkish tariff hikes, while negative surprises force the White House to backpedal.
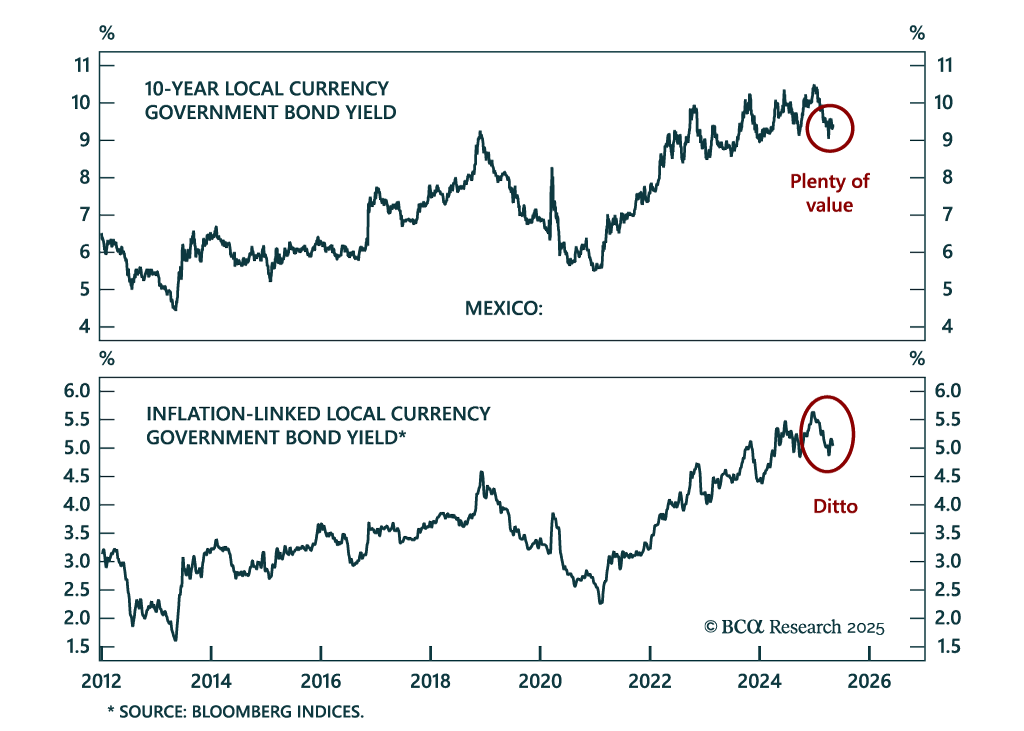
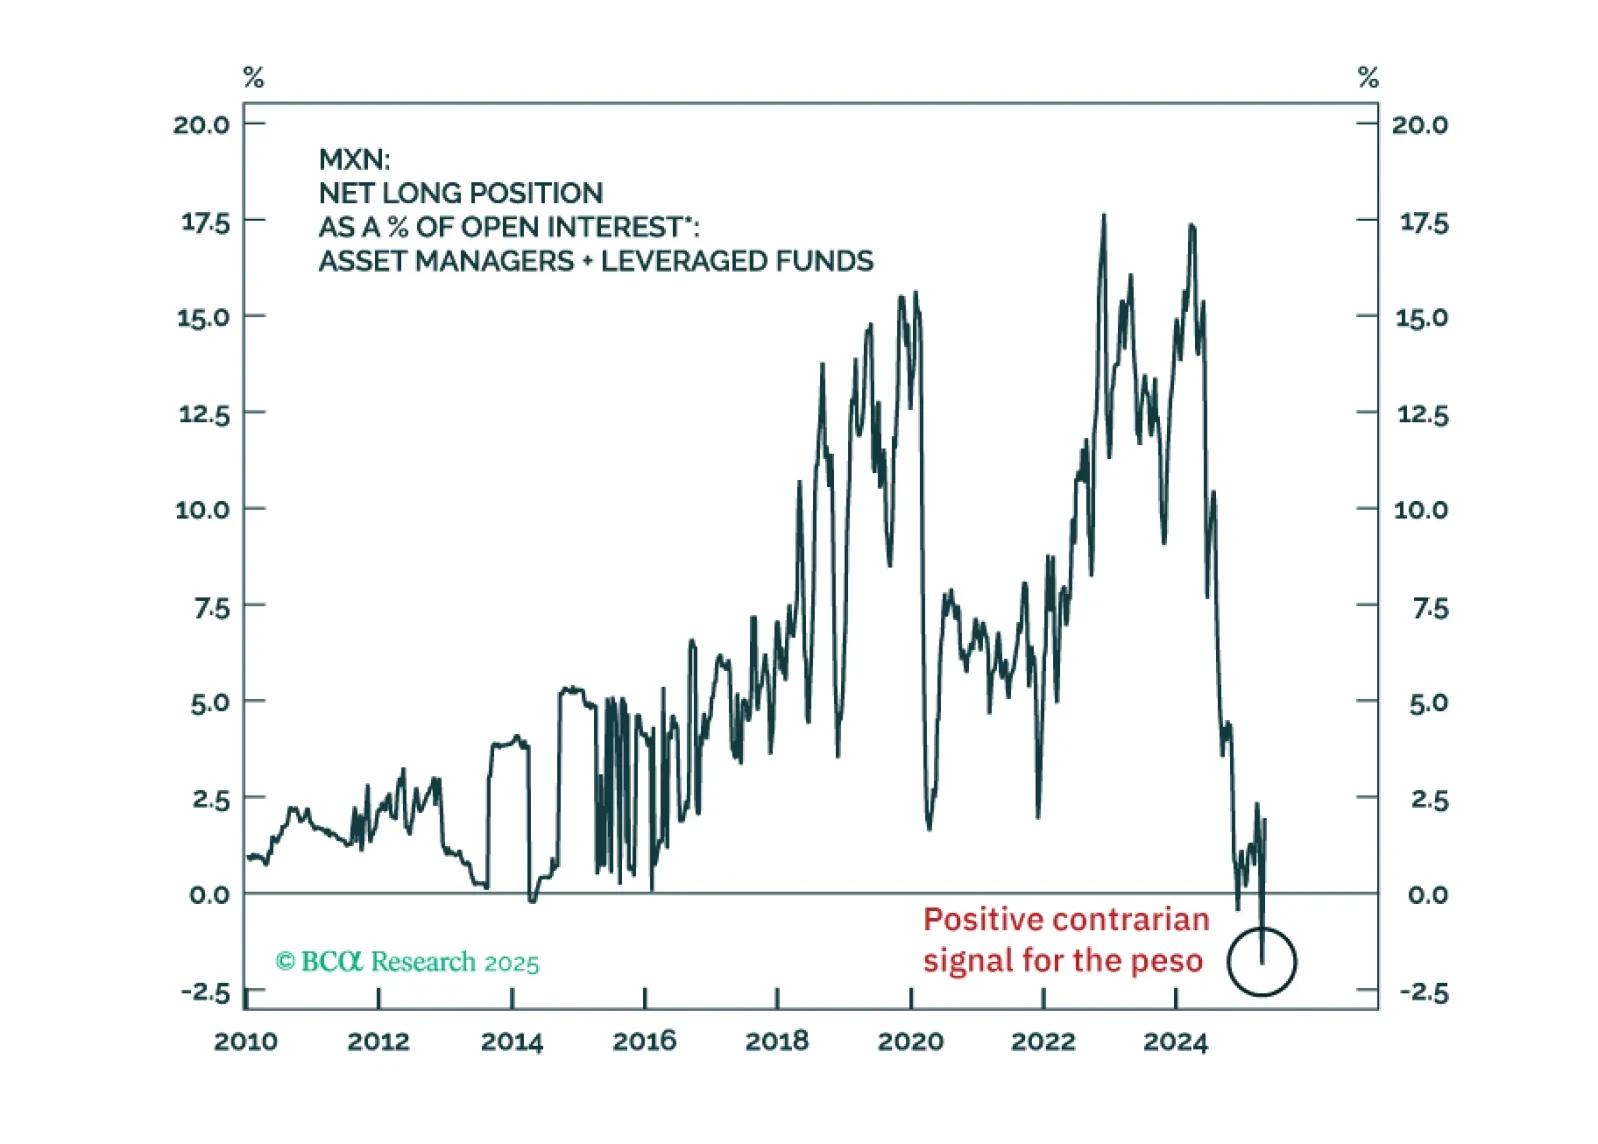
In the long run, Mexico will emerge as one of the biggest winners of US tariffs as the US diversifies supply chains away from China. In the medium term, however, a US growth slowdown and tariffs will push Mexico into recession. In EM portfolios, we remain overweight Mexican equities, domestic bonds, and sovereign credit. We are reiterating a buy on 10-year domestic bonds. Go long MXN versus CNH.
This year’s corporate bond sell off has hit high-yield more than investment grade, and high-yield spreads have turned relatively more attractive as a result.
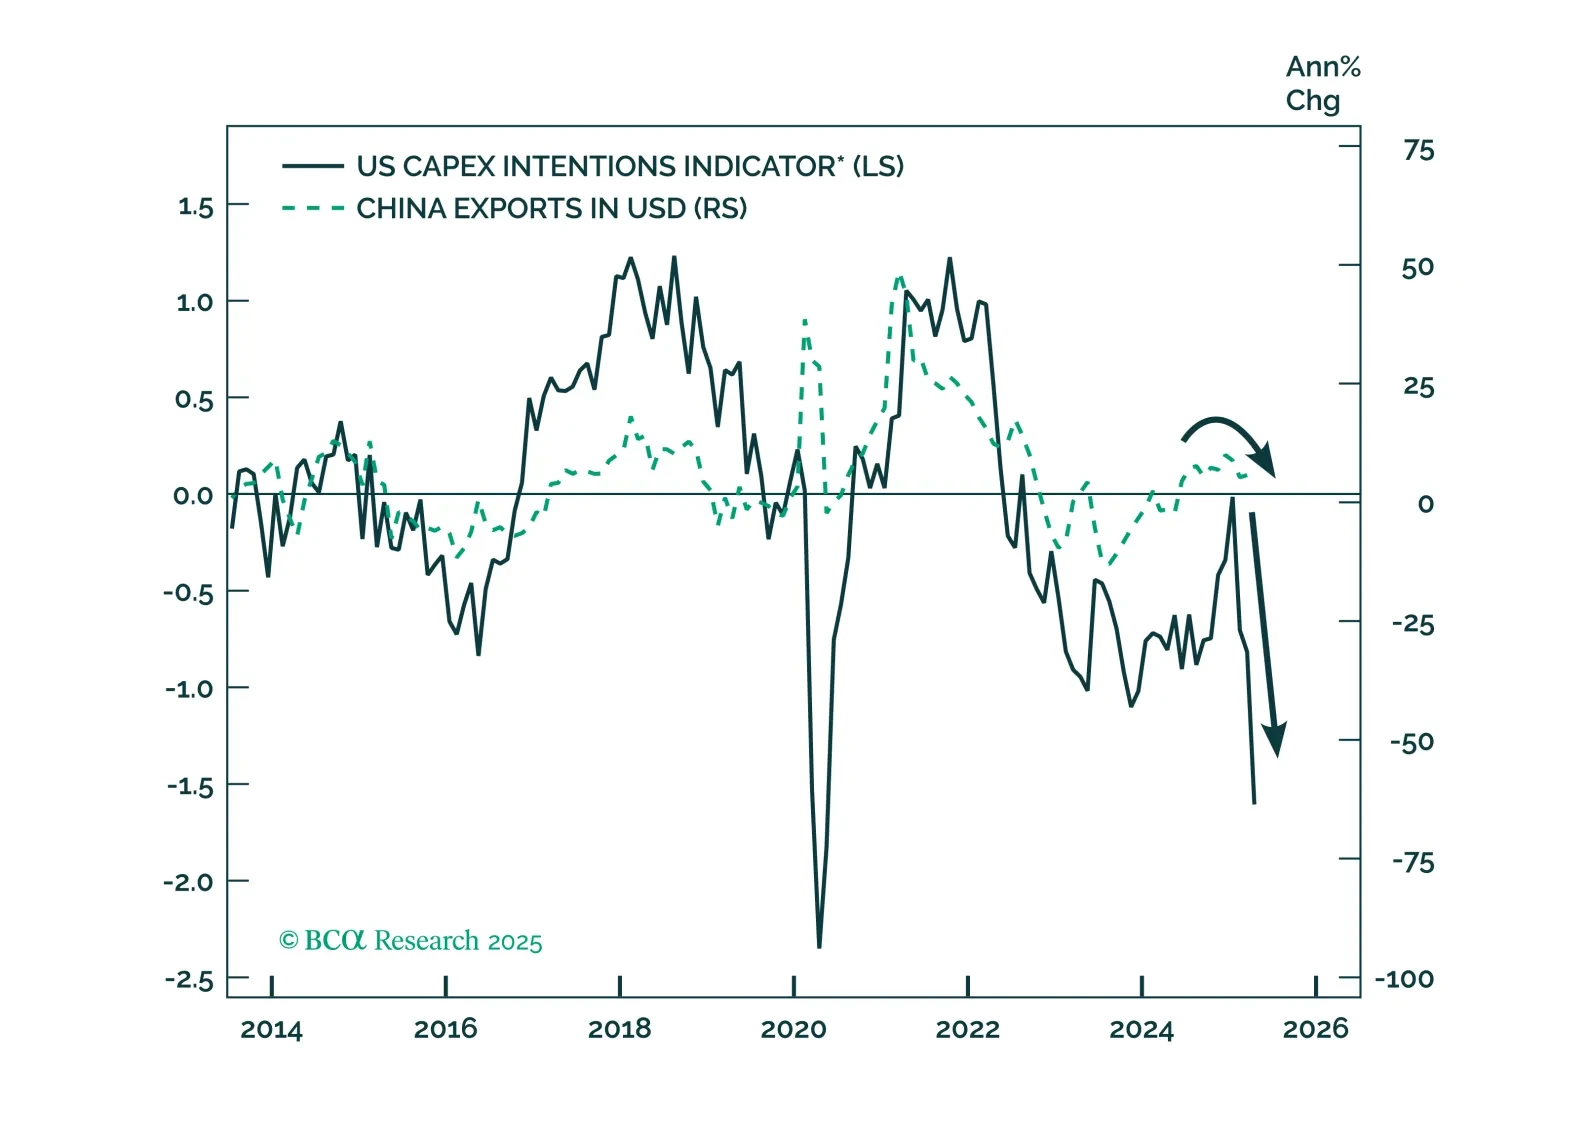
Despite marginal de-escalation in tariffs between the US and China, a sustainable trade agreement remains elusive. In the meantime, economic damage continues to mount, and Chinese equities have yet to fully price in the tariff-induced growth deterioration.
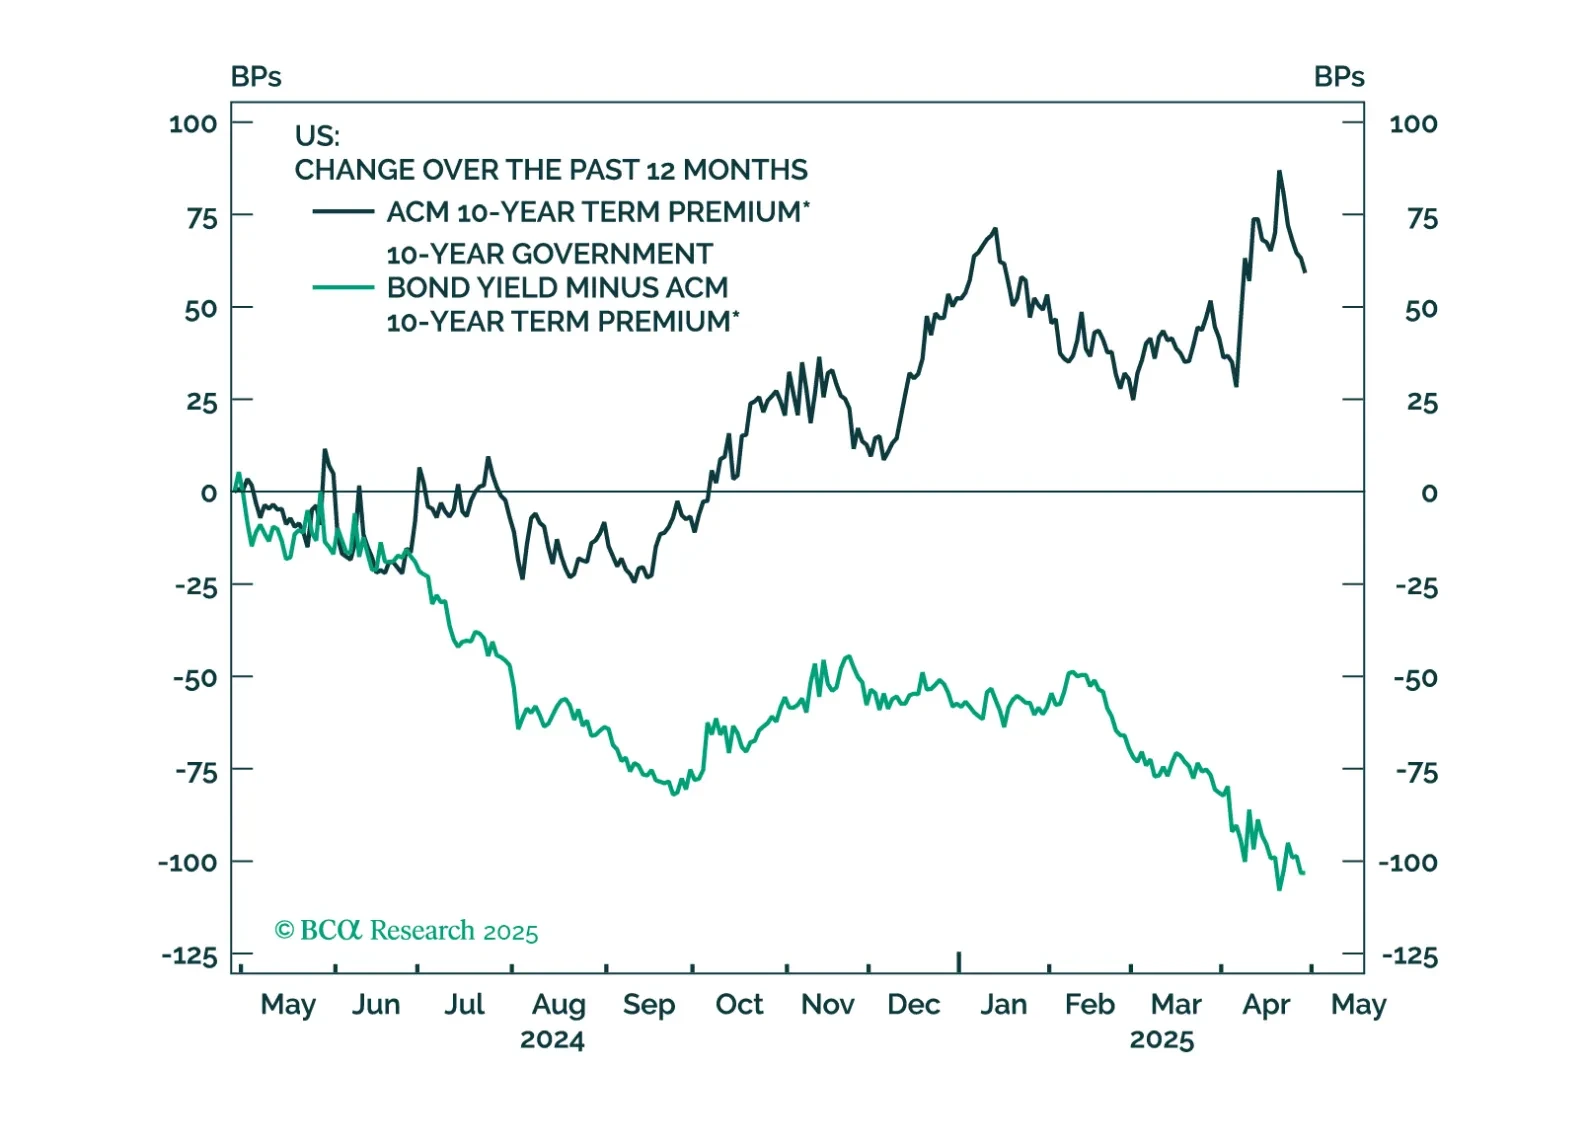
While most investors spent the month of April frantically refreshing their Twitter feeds for the next tariff announcement, we reiterate our stance that details on tariffs should be left to day traders. Long-term investors should be focused on the bigger story: the triple selloff in US stocks, bonds and the dollar. Foreign investors perceive that there has been a deterioration in governance in the US, and are requiring a higher risk premium from America. While Trump has walked back some of his most aggressive rhetoric, business investment will not resume unless we get clarity in policy. We continue to recommend a defensive stance, but downgrade duration from overweight to neutral to protect ourselves against shocks to the term premium. We also introduce Bitcoin to ours asset coverage. We upgrade it from underweight to neutral.
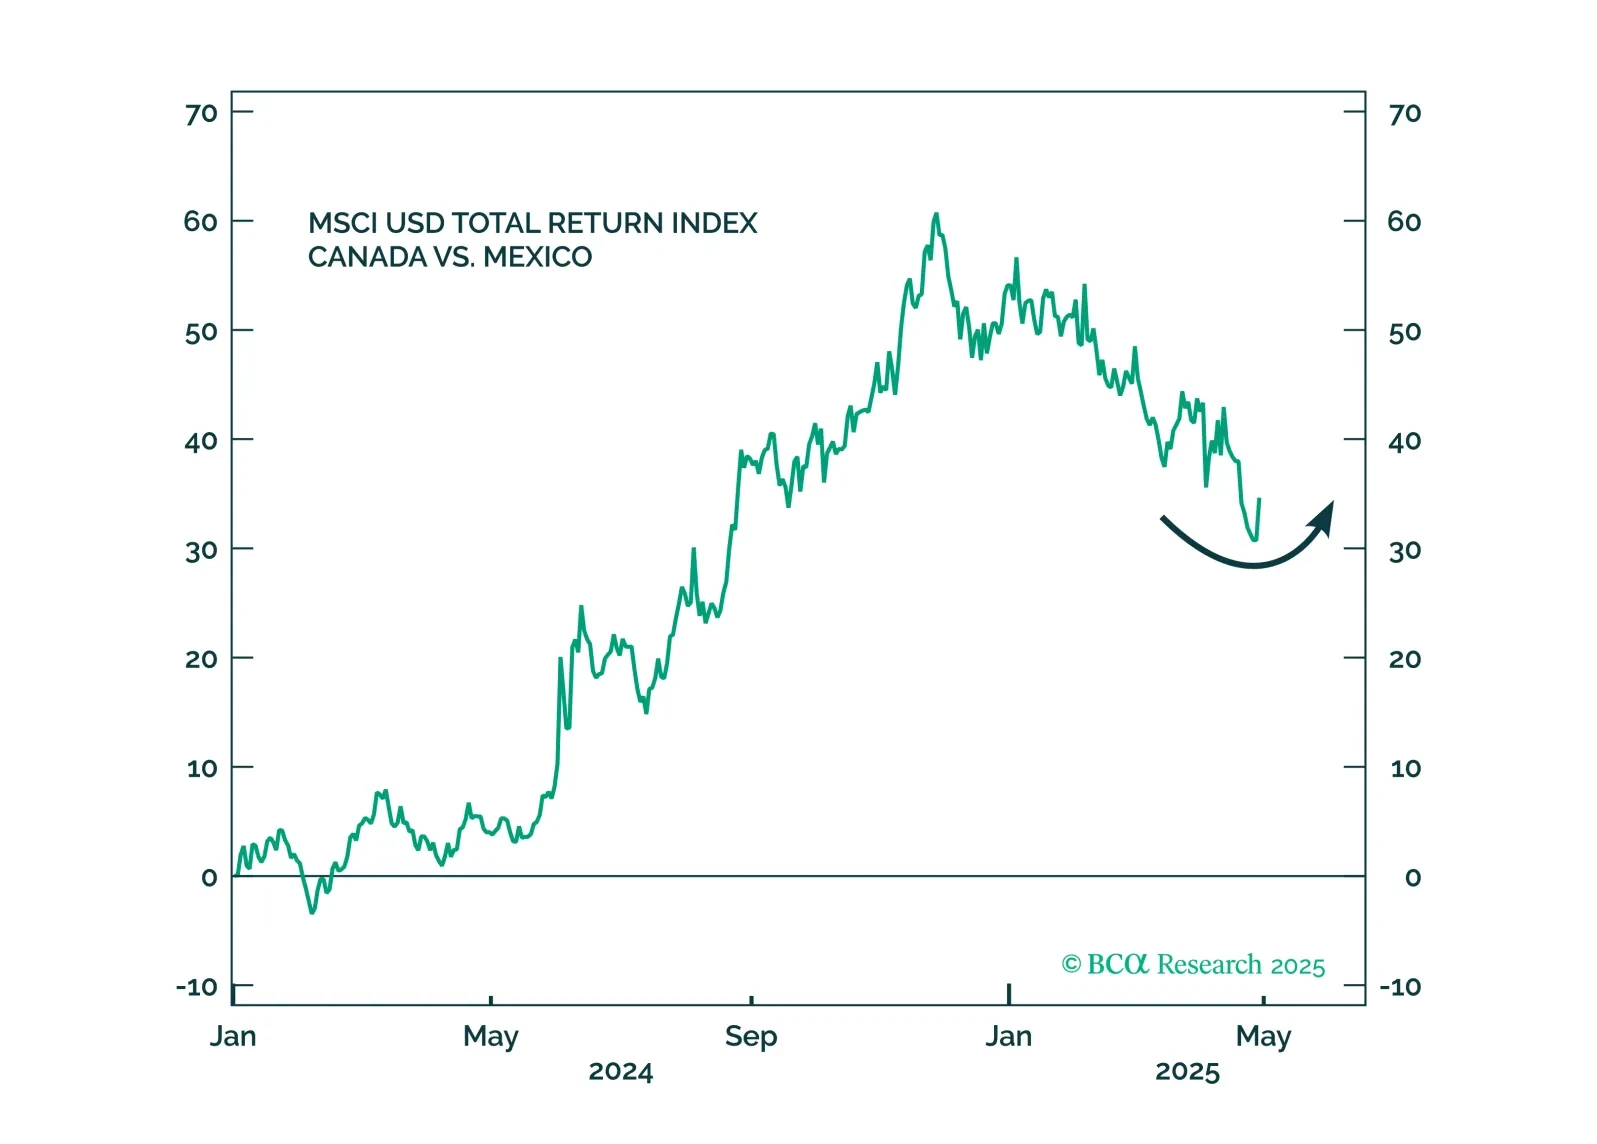
The US and Canada will resolve their trade dispute quickly, leading to a North American deal and better prospects for future relations, as well as for other US trade deals around the world. But even as tariff threats decline, the US economy will slow, weighing on its neighbors. Canada will fare better than Mexico.
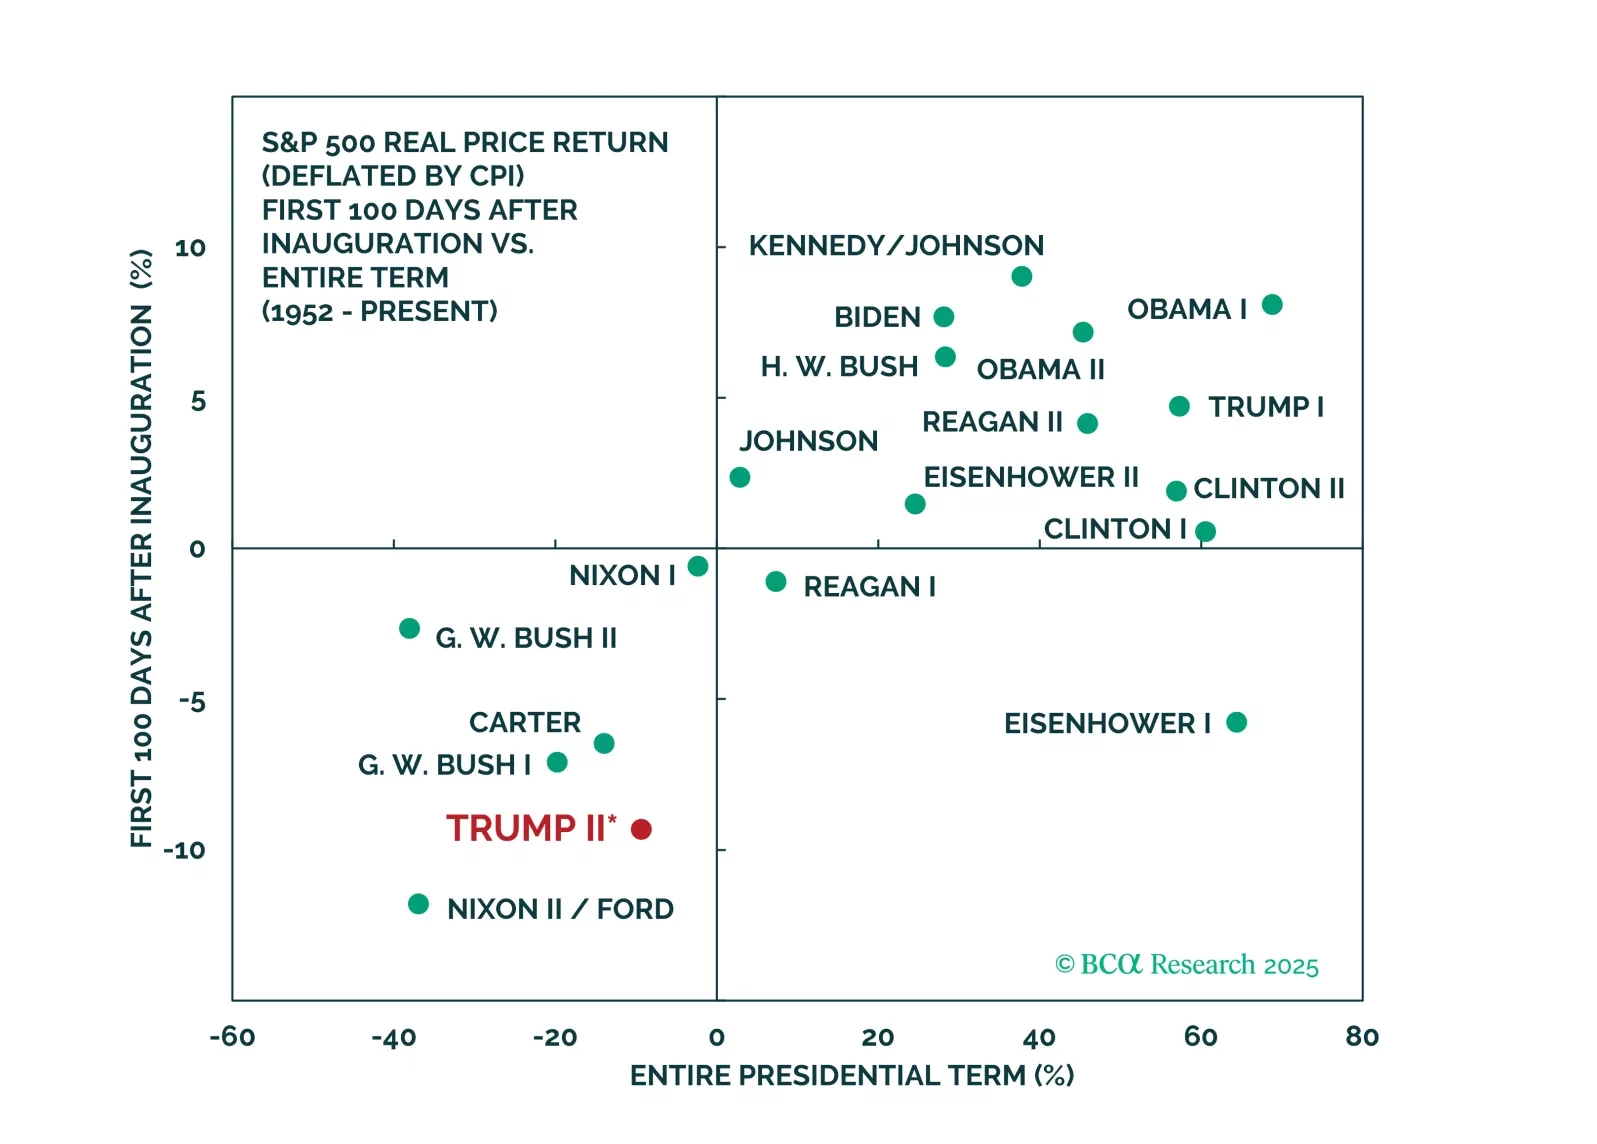
Do not play the bounce in US and global cyclical assets as Trump backpedals from the trade war. China will talk, but the pace will be slow and the outcome disappointing. Fiscal stimulus will surprise marginally in the EU, China, and even the US, but still may not rescue the business cycle.
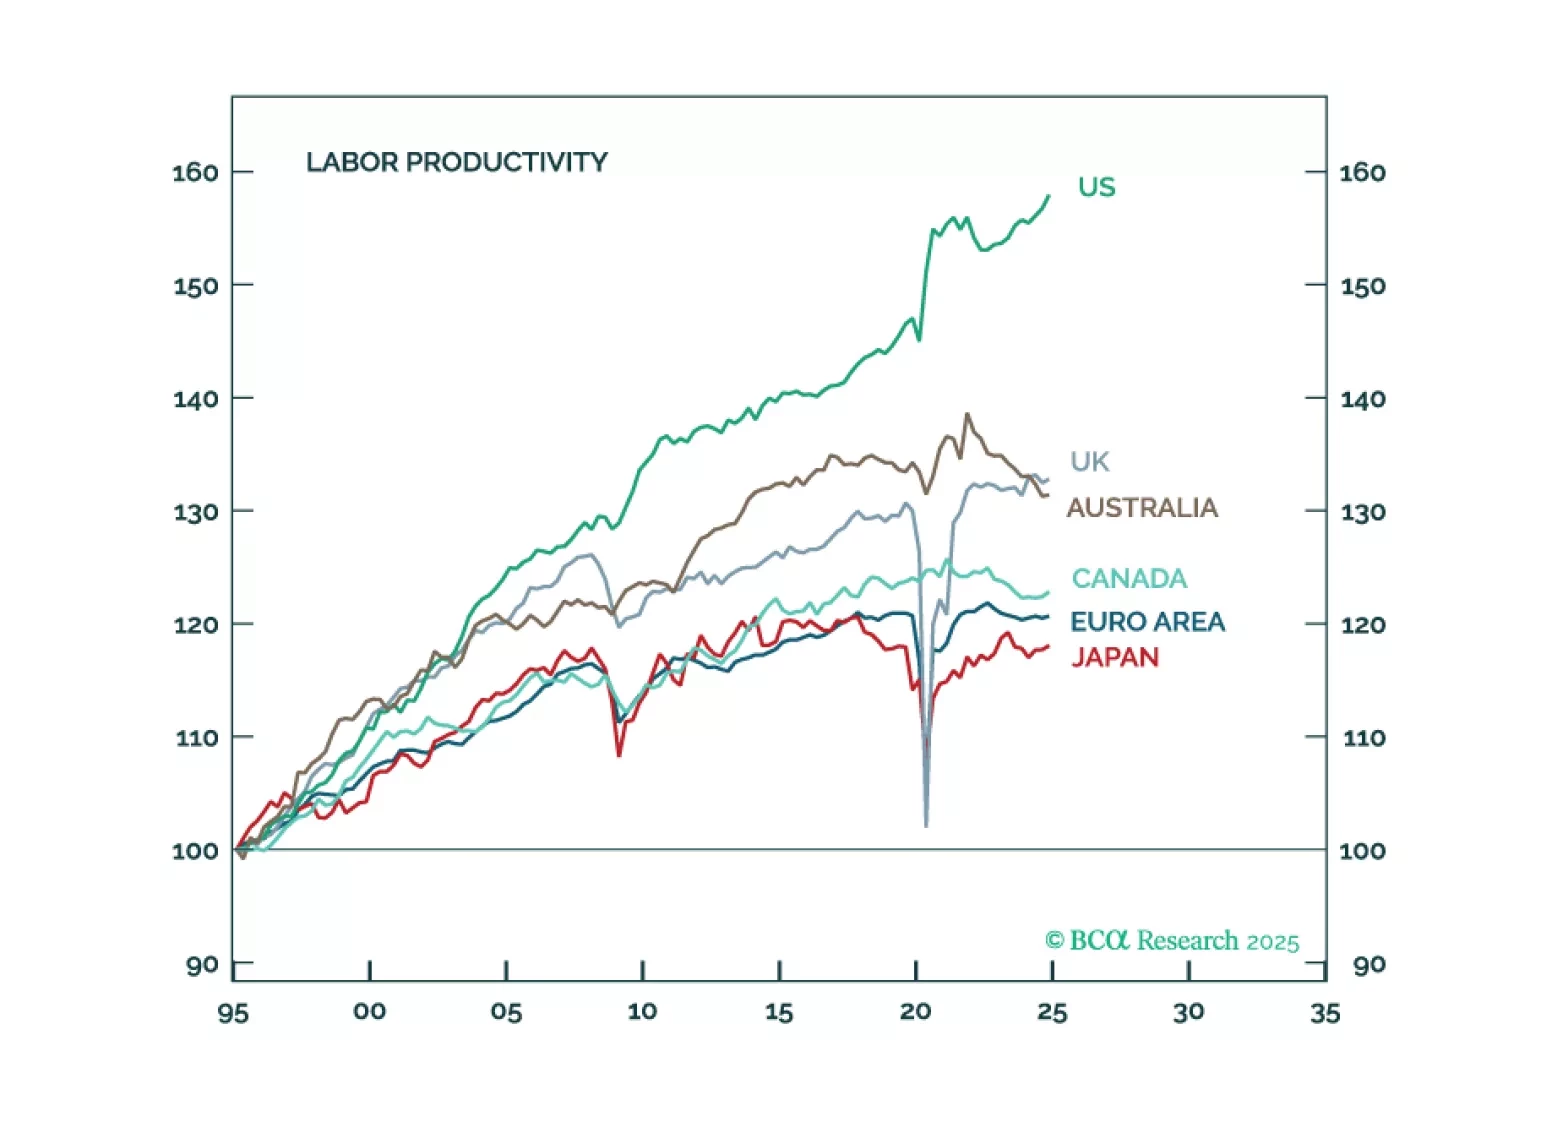
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.