Insights
Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
Report
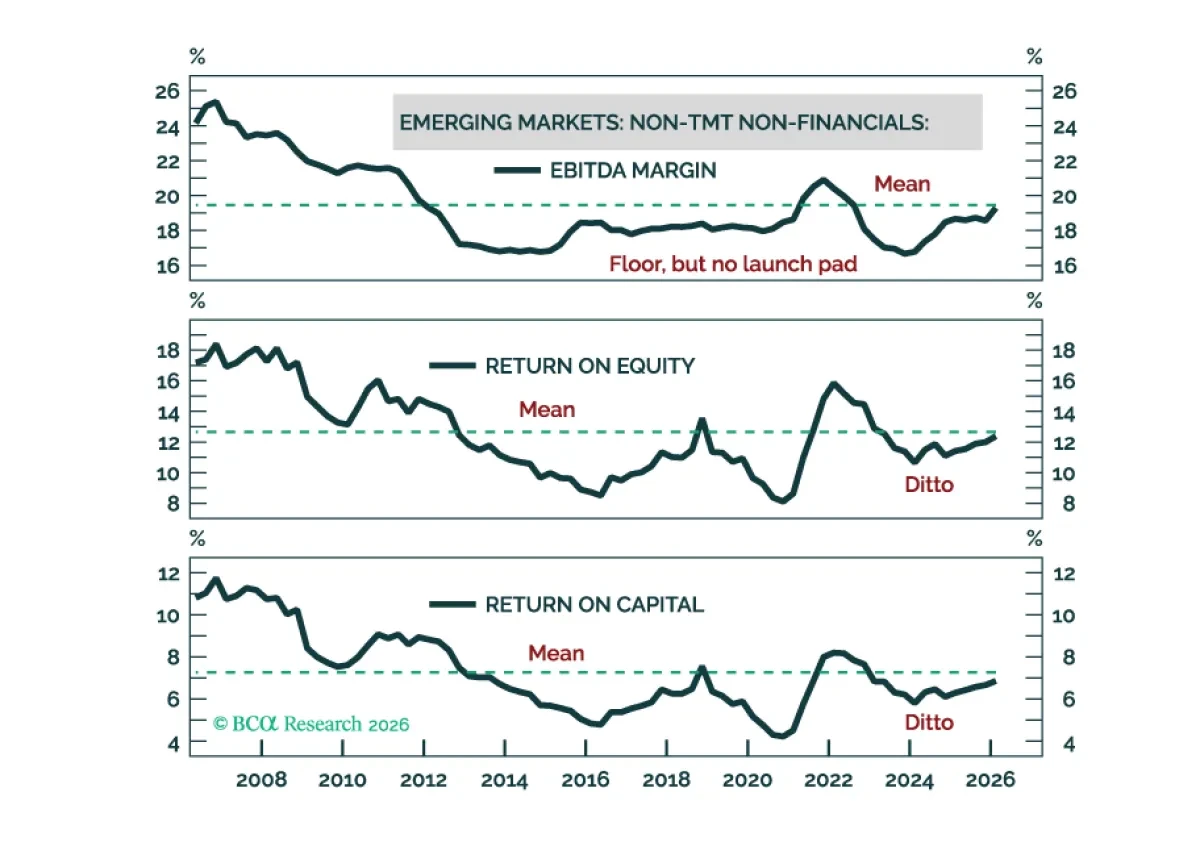
Outside semiconductor stocks, EM/China profitability has been well below both their US peers and the levels that prevailed during the EM structural bull market in the 2000s. Over a 3- to 5-year horizon, EM/China relative equity performance versus global will be range-bound....
Read more
Report
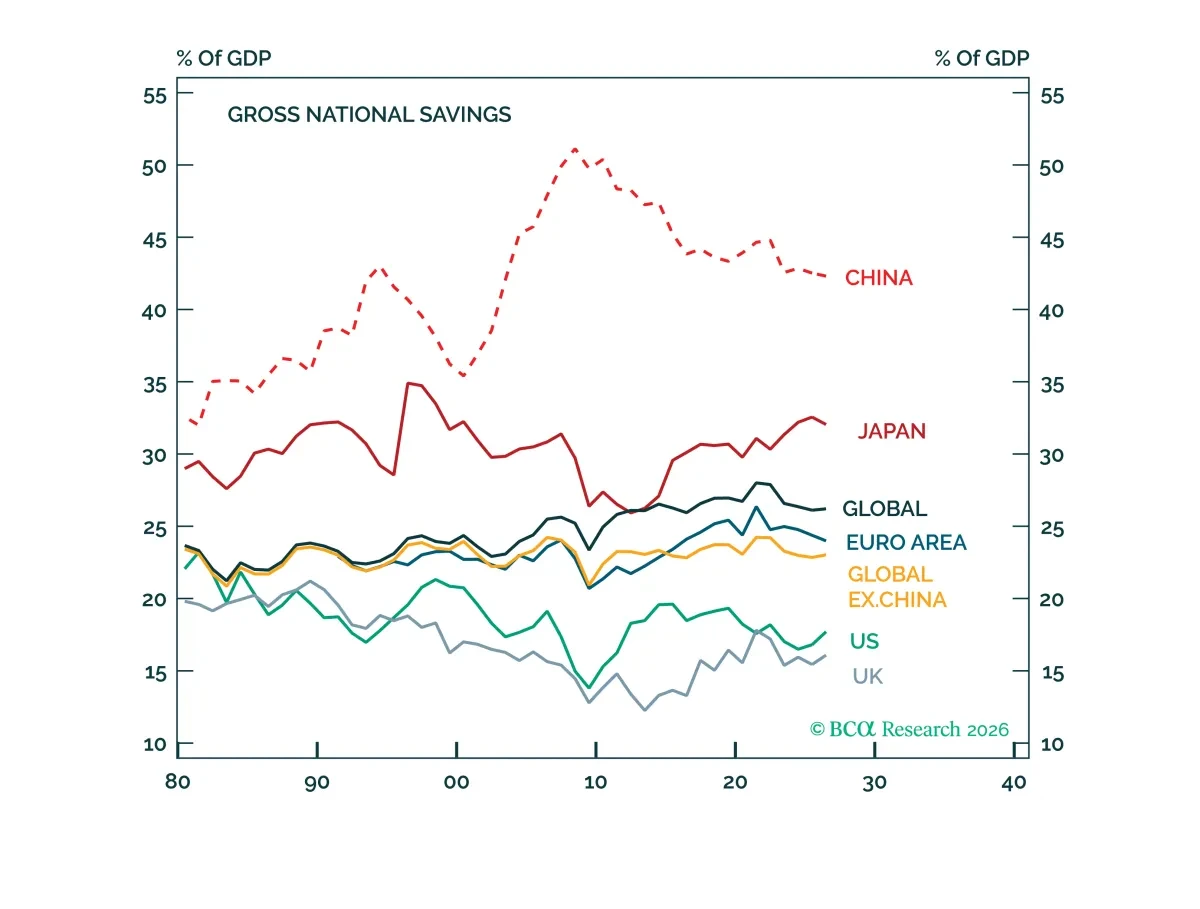
China does not produce too much. It spends too little. The only viable way for China to reduce investment without raising unemployment is by lowering national savings. Doing so is likely to be politically challenging, however. This suggests that China will suffer from subpar growth and deflationary ...
Read more
Report
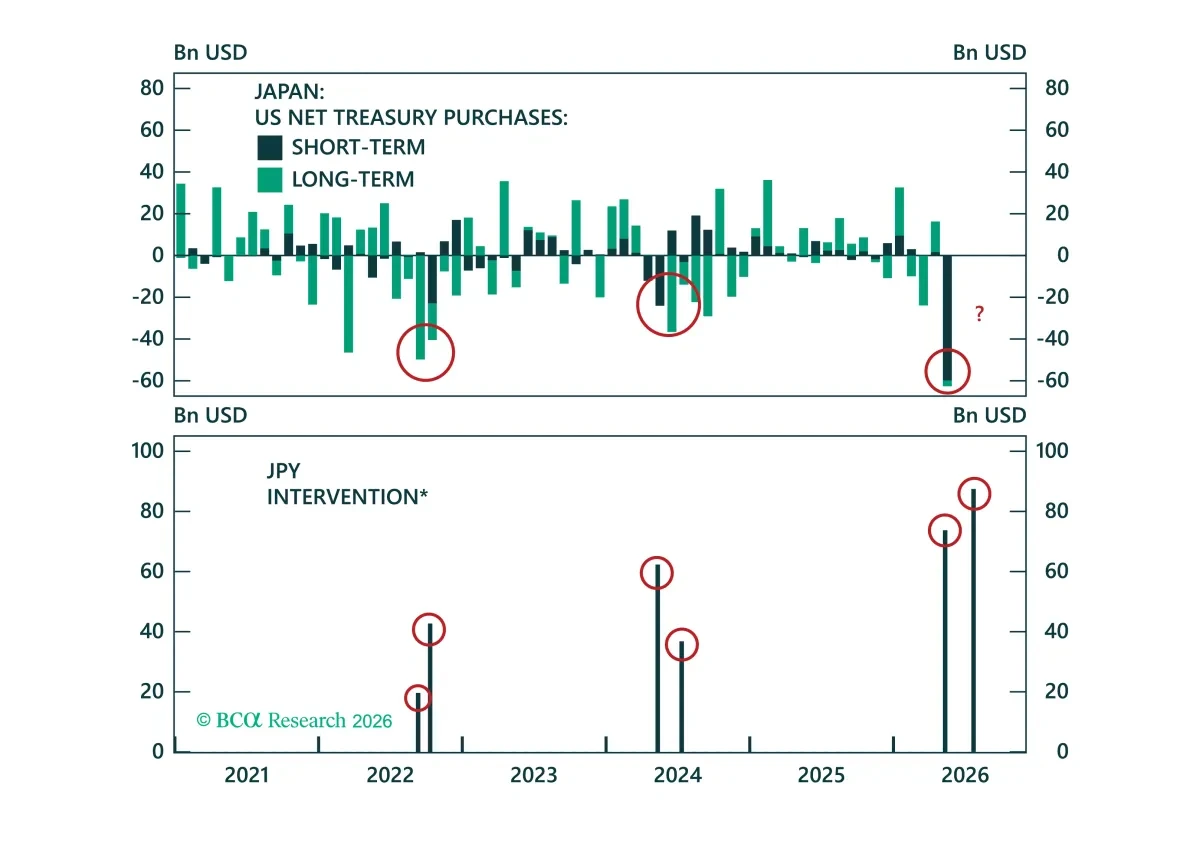
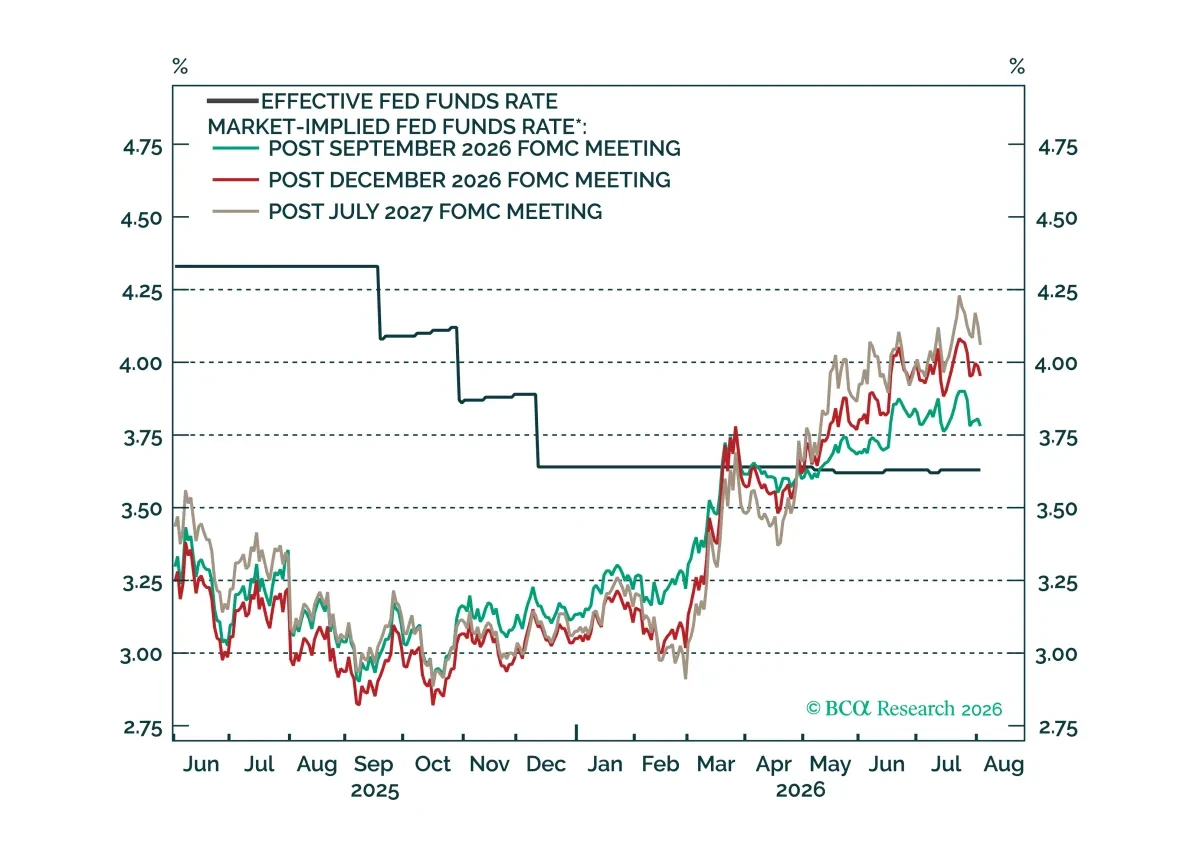
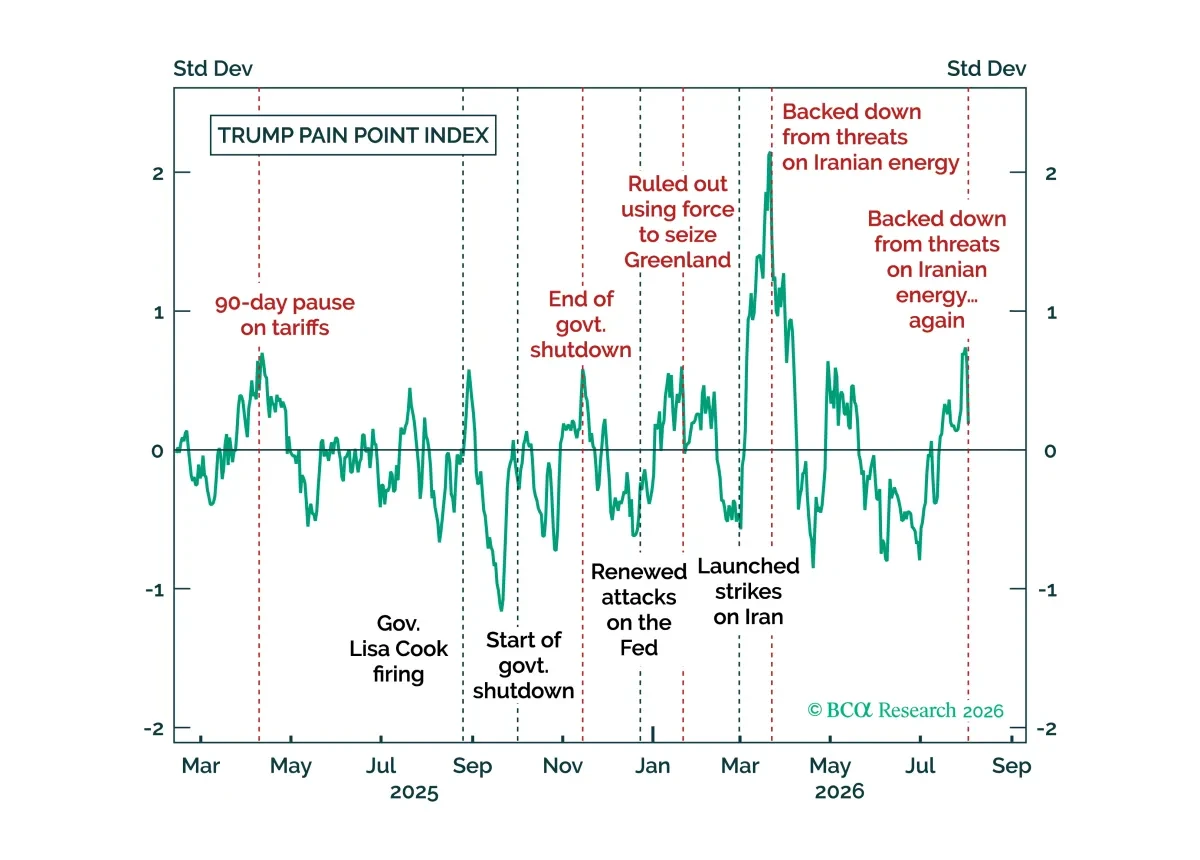
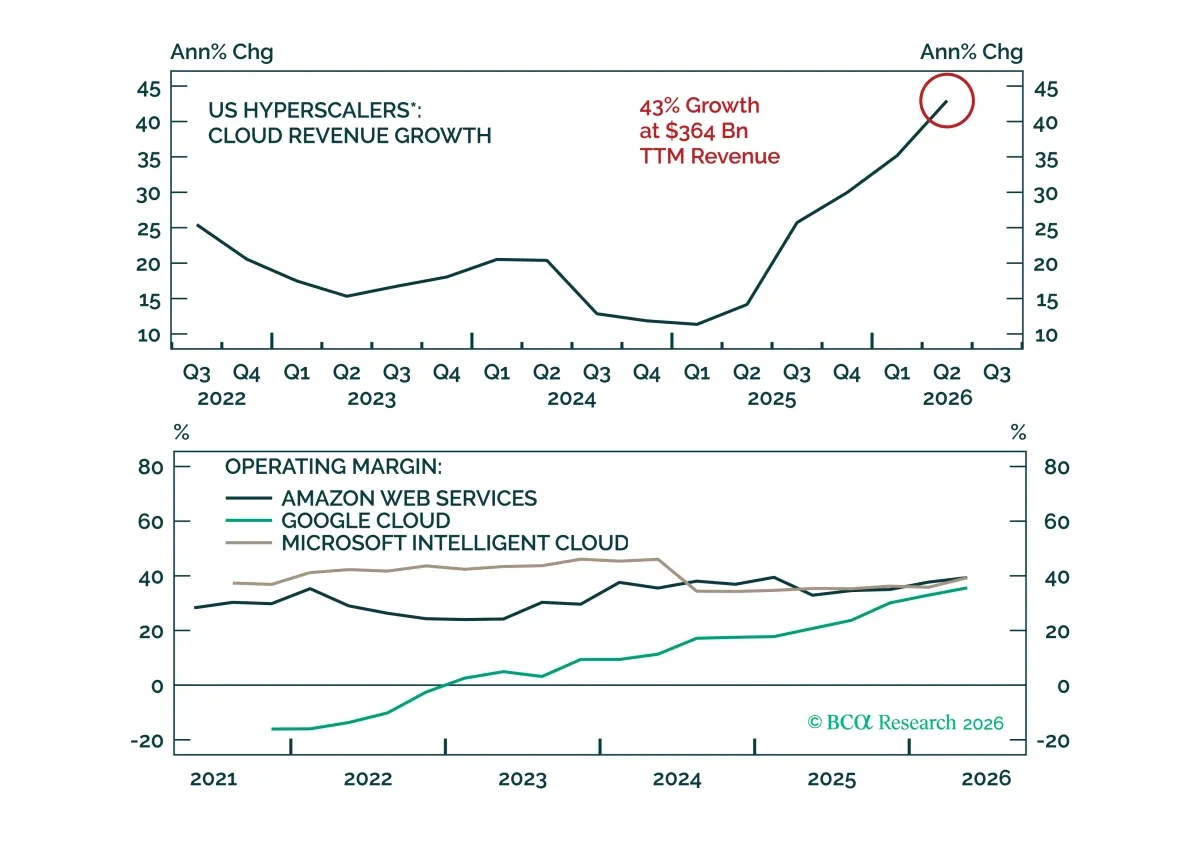
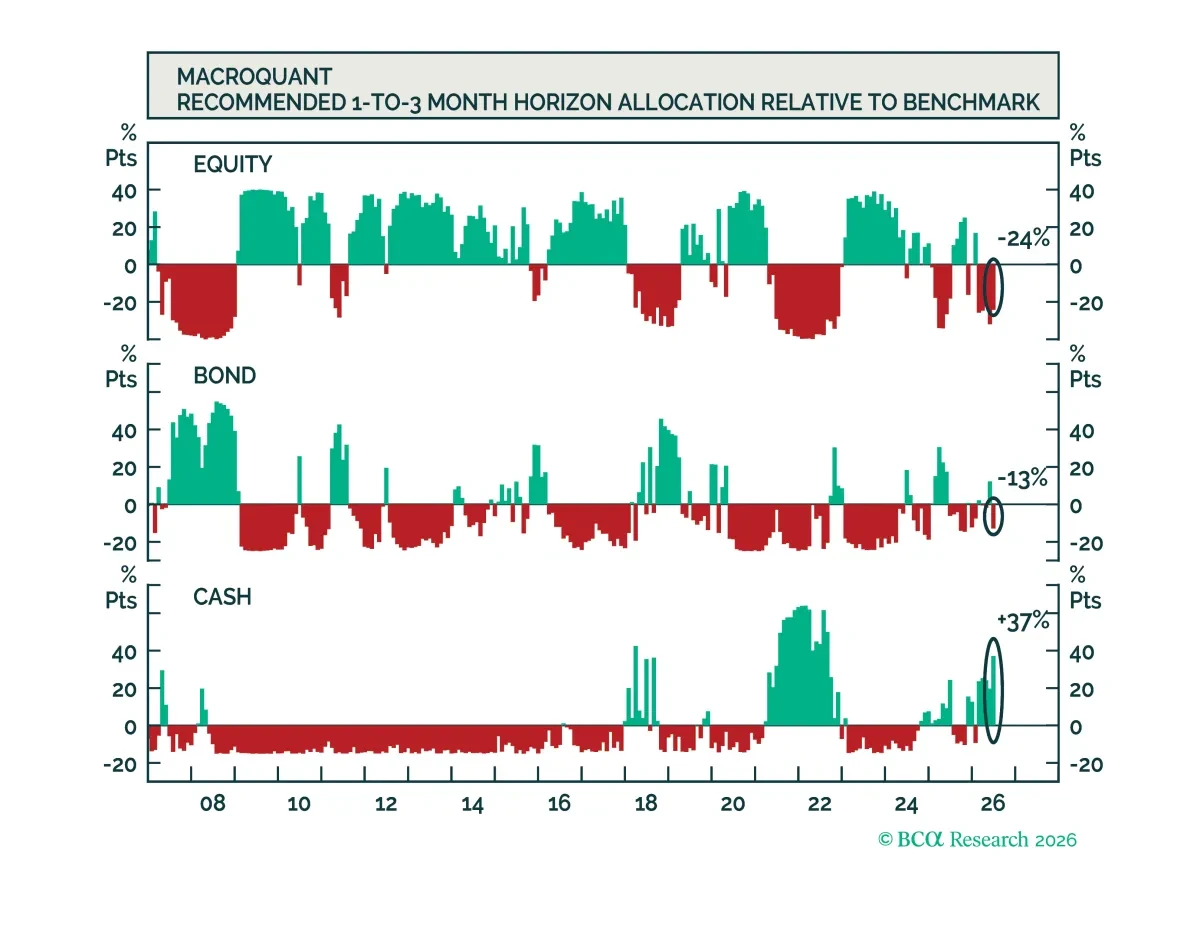
Last month we "stuck our neck out" and reaffirmed our bullishness towards risk asset. This month, we have confirmation that the risky bet is paying off. Iran and the US remain materially constrained from total war. The AI capex thesis is holding up and slowly mutating into a price war that will only...
Read more
Report
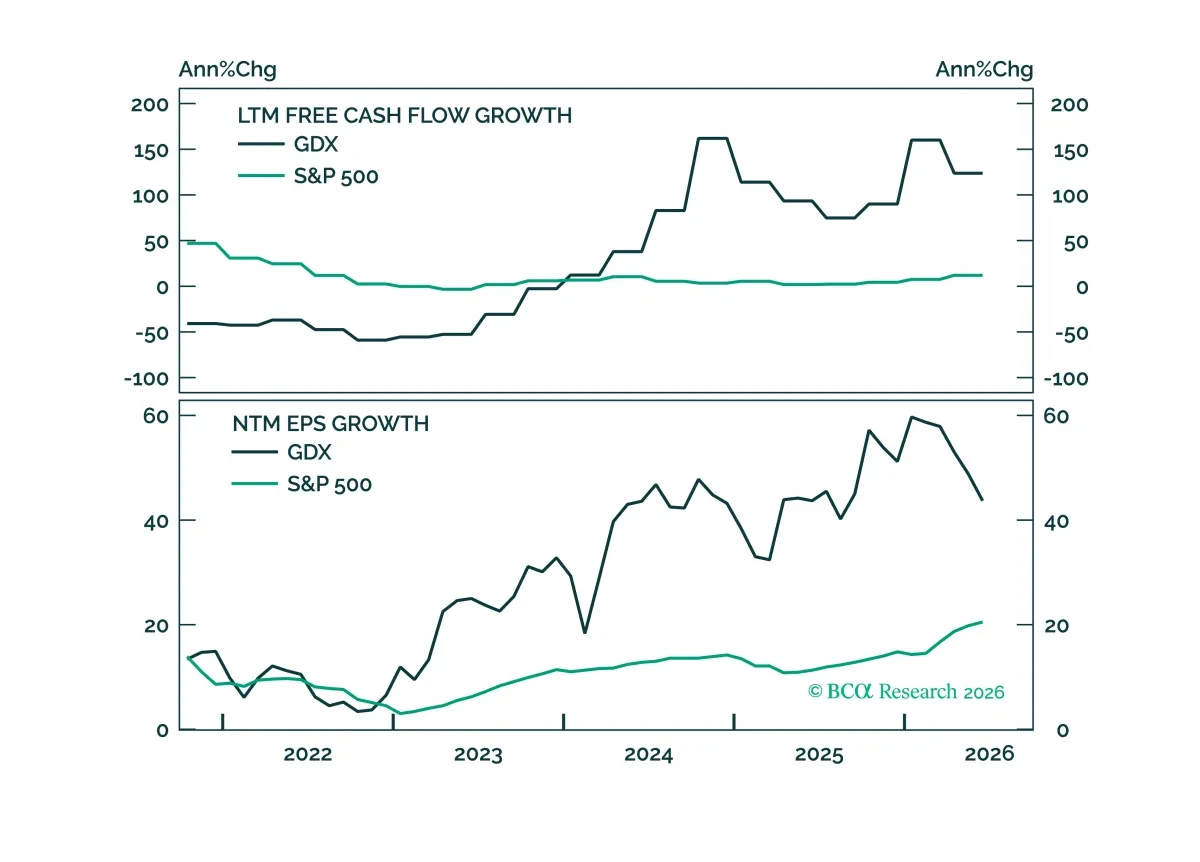
Gold and goldminers have corrected 25% from January highs. With our commodity team bullish gold, we are getting long GDX. Goldminers offer a gold-linked hedge against macro outcomes that would likely be damaging for equities, while improvements in profitability, capital discipline, and balance-sheet...
Read more
Report
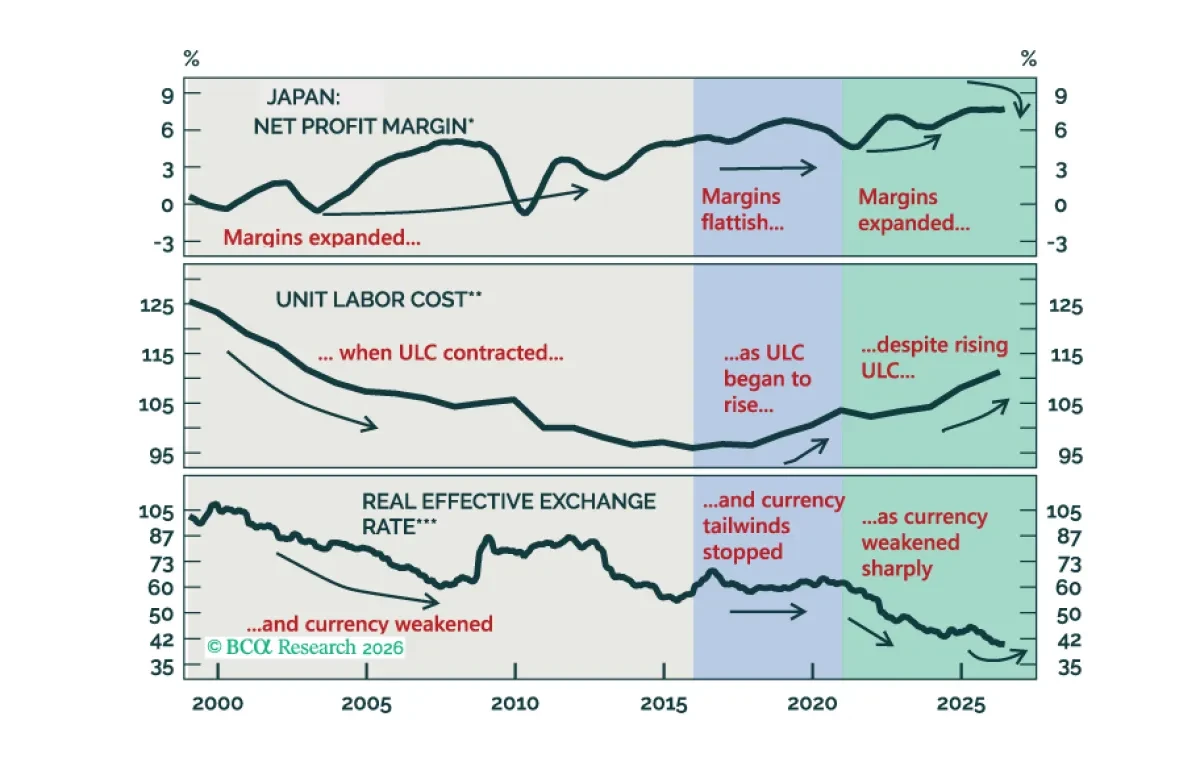
Over the past 10 years, Japan’s profit margin expansion has been driven neither by advances in labor productivity nor by operational efficiency gains, but by massive currency devaluation and lower depreciation charges. Going forward, higher wages and unit labor costs, as well as currency appreciatio...
Read more
Report
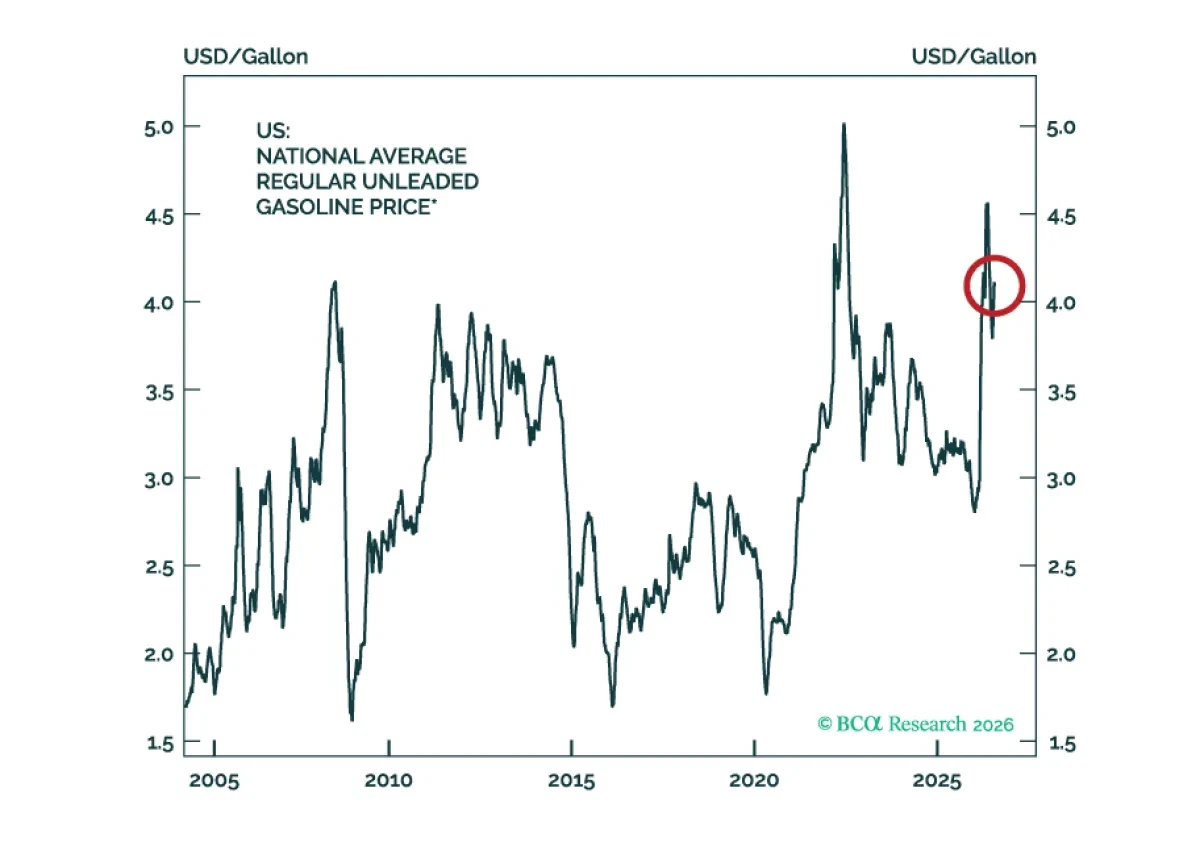
Section I outlines BCA’s views on the US-Iran conflict, Europe’s near-term outlook, the currency and bond selloffs in Japan and the early days of the Warsh Fed. In Section II, Roukaya, Matt, and Artem argue that the worst of gold's downturn is likely behind us. Real rates and the dollar — which have...
Read more