UK
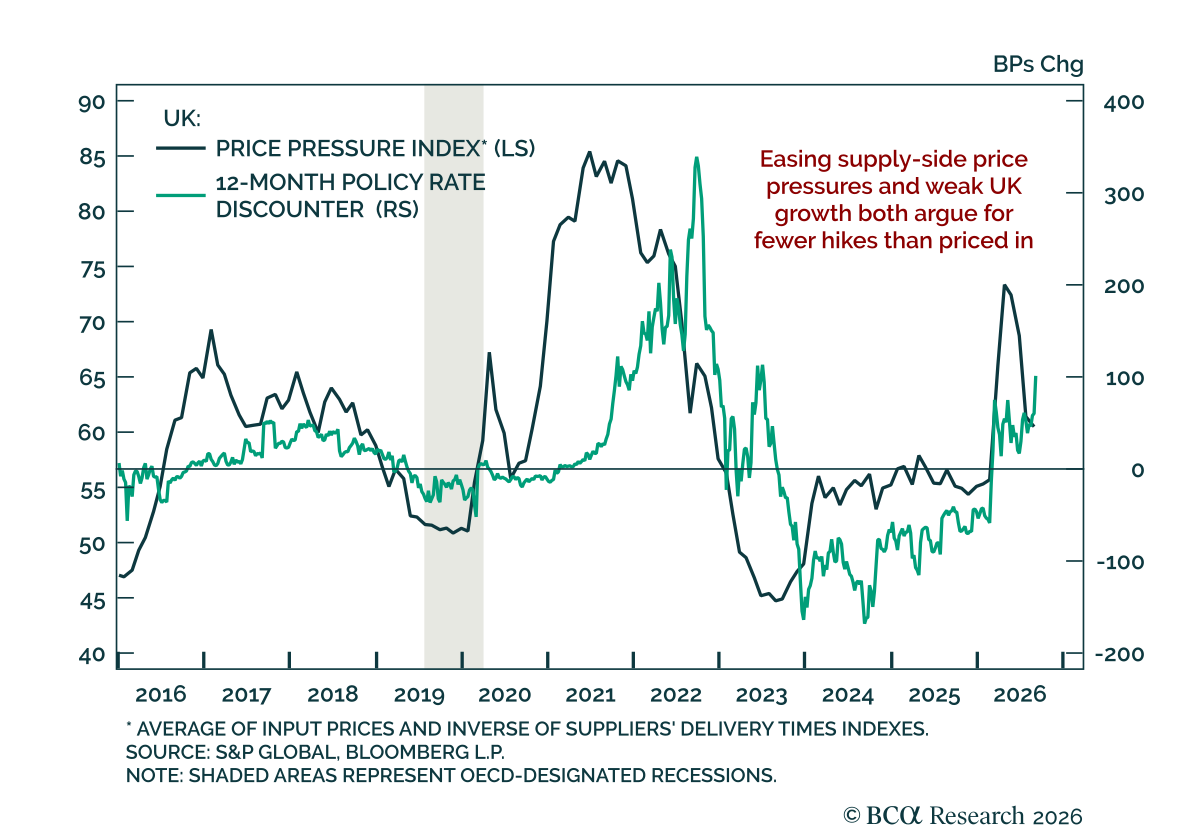
The BoE held rates at 3.75%, but despite a more cautious tone on inflation, the UK economy still shows little risk of overheating or second-round effects, supporting our overweight on gilts. The decision was split 6-3, with Greene, Mann, and Pill voting for a…
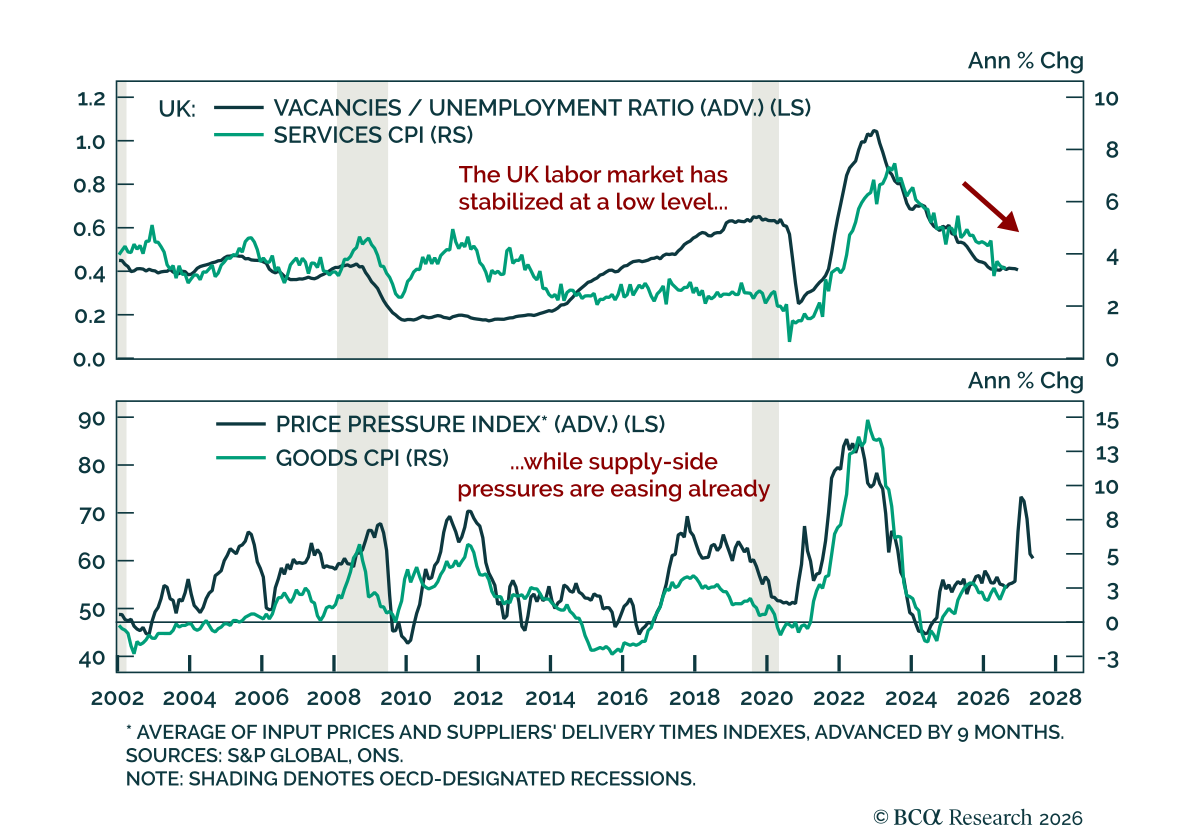
The latest UK employment and inflation data show a labor market with some slack and no sign of accelerating inflation, supporting an overweight on UK gilts. Payrolls fell by 26k in August, more than expected and faster than the negatively revised 19k decline…
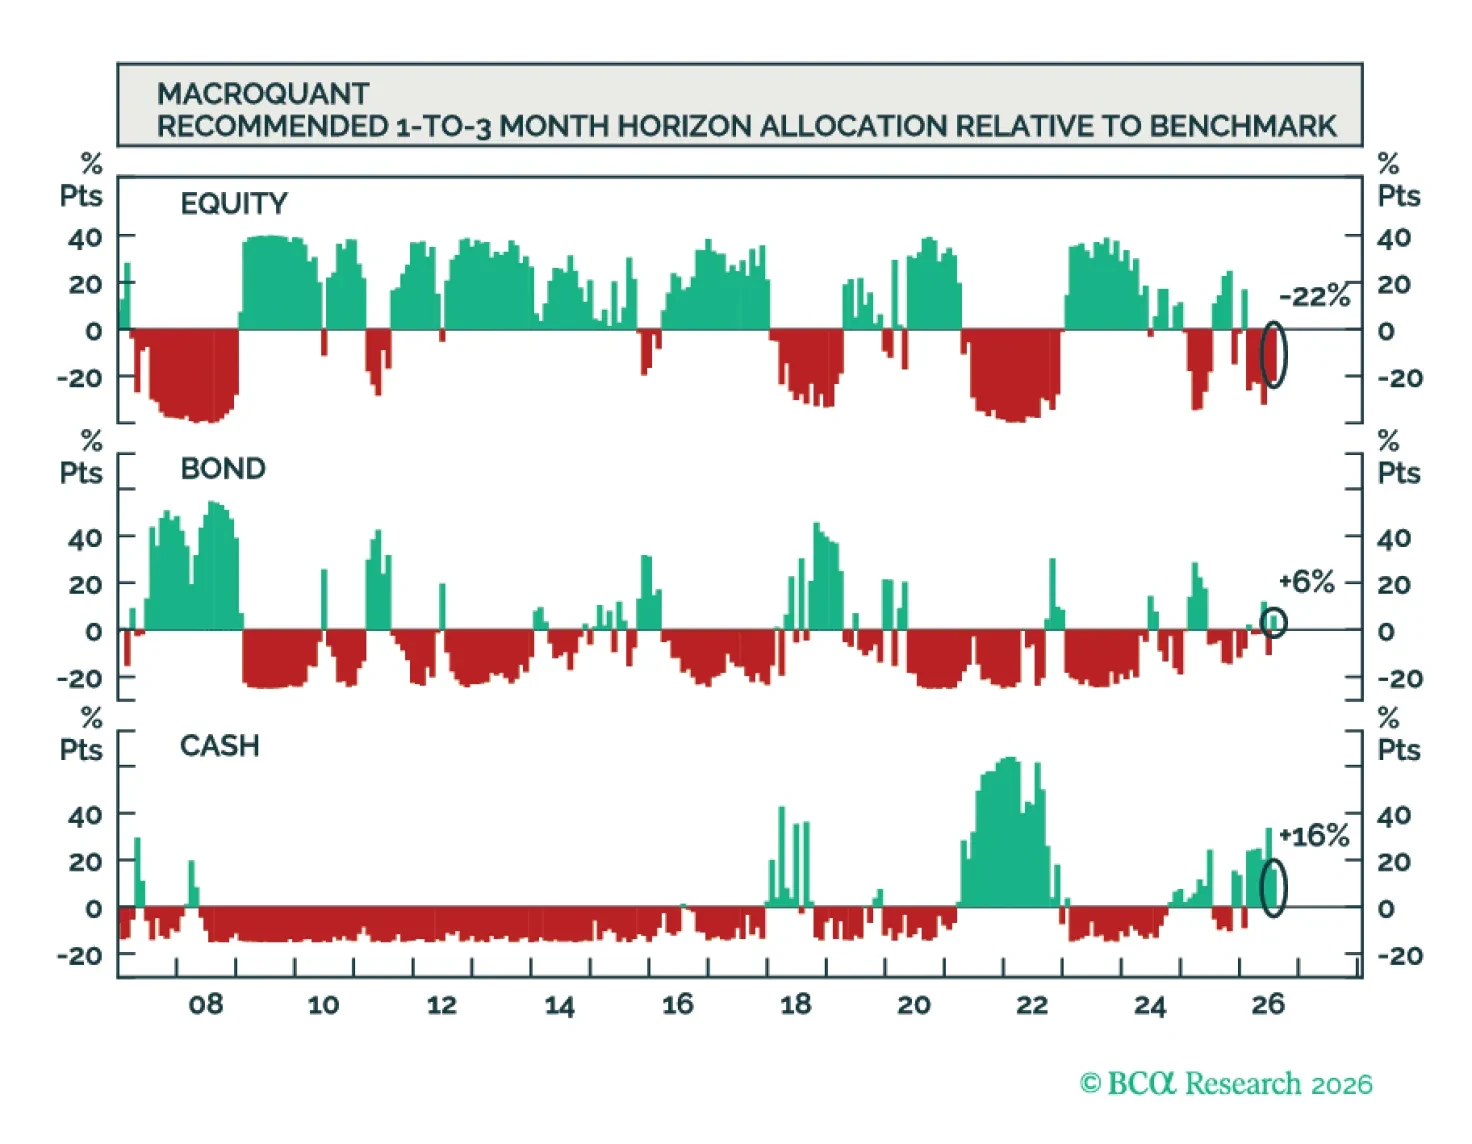
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
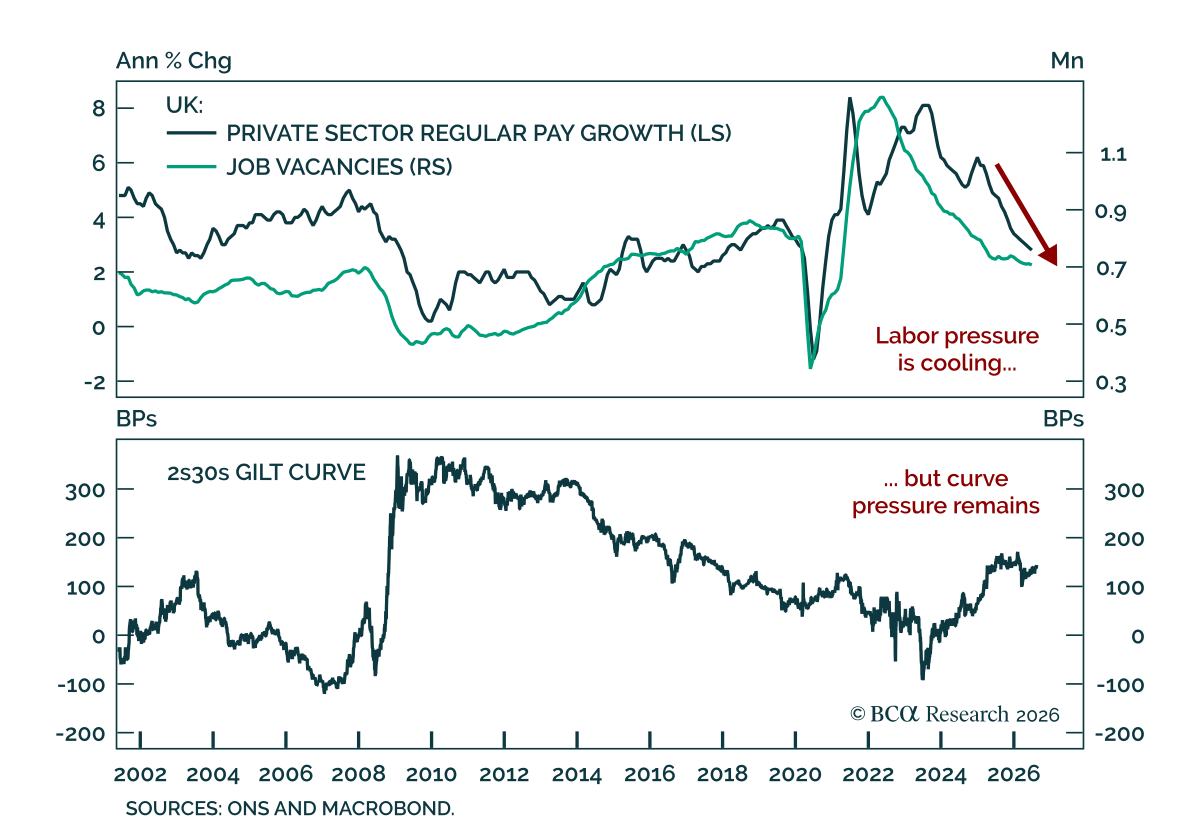
Softer UK labor data argues for a 2s30s gilt steepener, not a broad duration rally. Private-sector wage growth ex. bonuses slowed to 2.8% y/y in the three months to June, the weakest since late 2020, while vacancies fell to 707k, the lowest in more than five…

UK hard data surprised to the upside in June, but leading indicators still point to weak growth and poor momentum ahead. Monthly GDP rose 0.3% m/m, accelerating from a downwardly revised flat reading in May. The details were mixed. Services rose 0.4% m/m,…
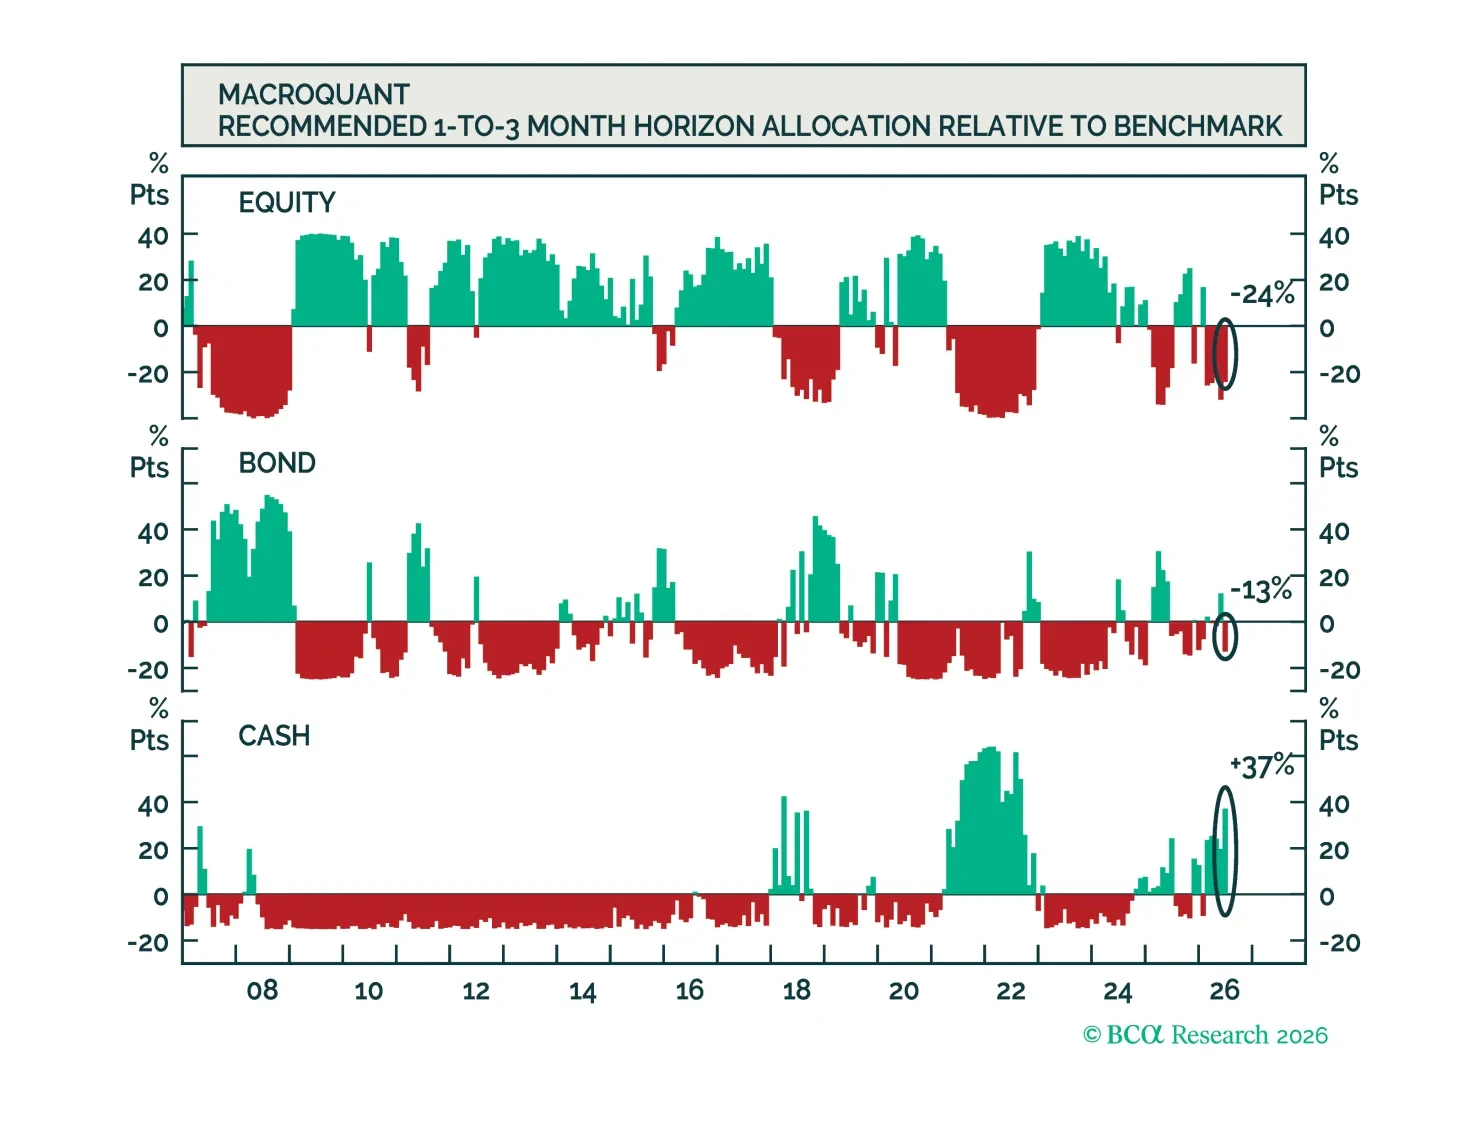
MacroQuant recommends a slight underweight position in equities, and favors a below-benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, neutral on gold, constructive on copper, and very bullish on oil.

A sidelined BoE confronted with weak growth and easing price pressures supports an overweight in UK gilts and an underweight in GBP. The BoE held rates at 3.75% for the fifth consecutive meeting. The 6-3 decision saw Mann, Greene, and Pill dissent in favor of…
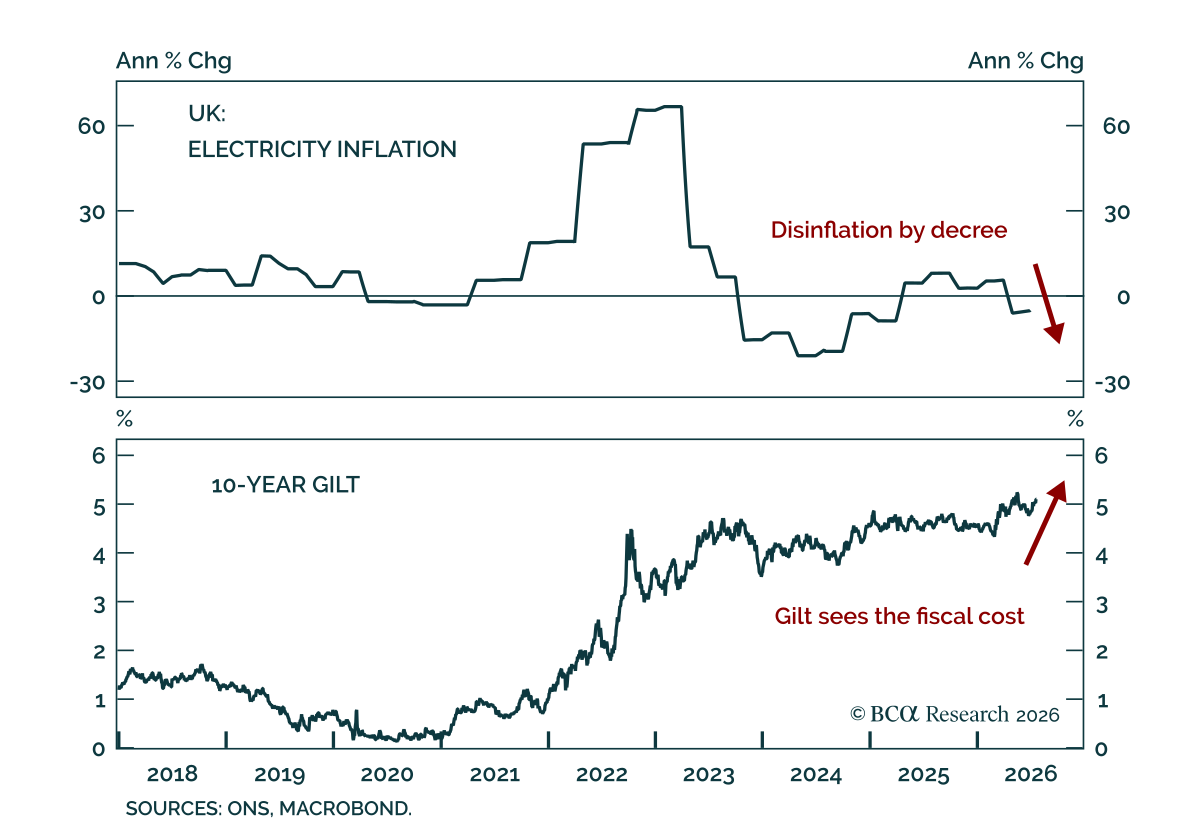
The UK’s latest cost of living relief may lower measured inflation, but it risks worsening concerns about fiscal credibility. June CPI was cooler than expected, falling to a 15-month low at 2.6%. Yet, this is not a clean disinflation story. UK inflation has…

UK May/June employment data came in marginally above consensus, yet only point to a labor market stabilizing at a weak level. Payrolled employees fell by 4k in June, versus expectations for an 8k decline. Job vacancies were broadly flat, as were the…

UK May hard data surprised to the upside, but still pointed to weak growth and limited scope for further BoE tightening. Hard data refers to directly measurable activity such as production, employment, and spending. Monthly GDP rose 0.1% m/m after contracting…