Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Consumer

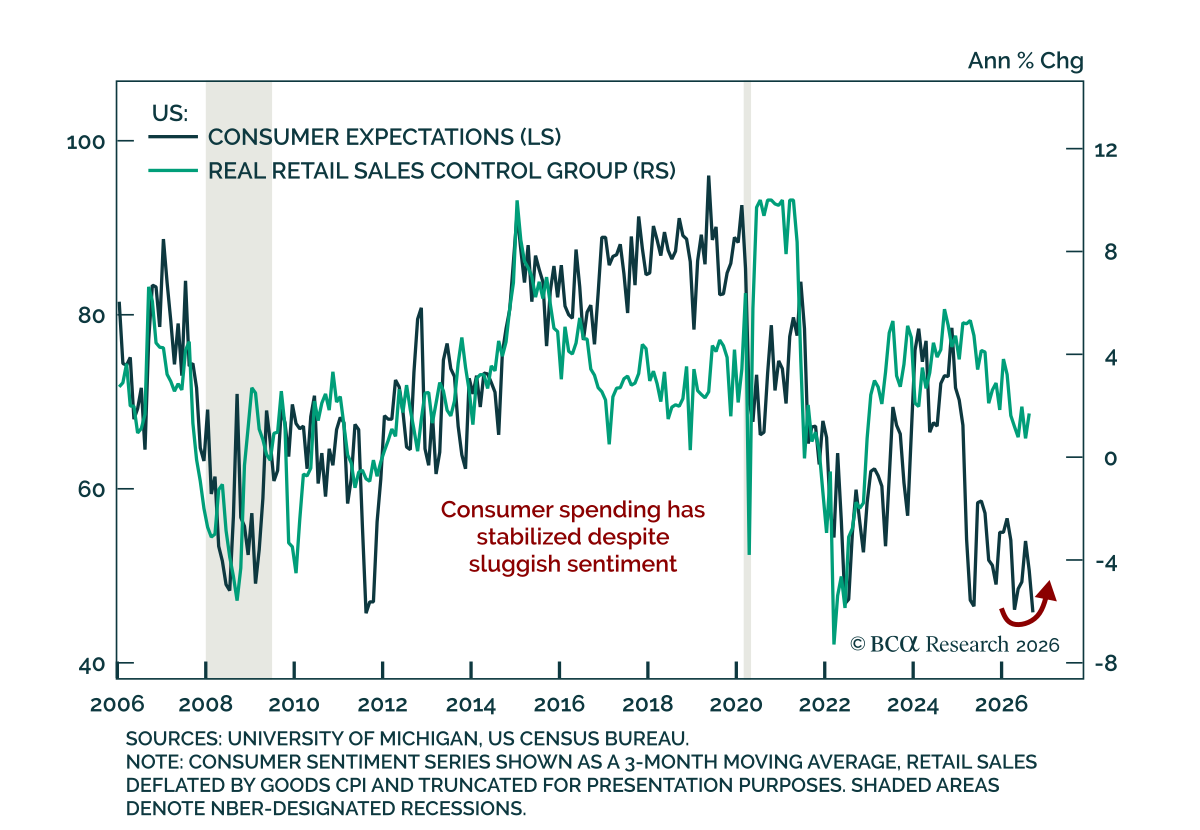
August retail sales were stronger than estimates and showed a clear rebound in consumer spending, but the broader pattern still does not point to an overheating US economy. Headline sales rose 1.2% m/m after falling 0.5% in July. The core measure excluding…
Our Bank Credit Analyst colleagues recommend maintaining benchmark allocations to equities and other risk assets, as the post-pandemic expansion remains intact amid balanced growth. Hiring has revived after a weak 2025, with employers adding an average of 80k…

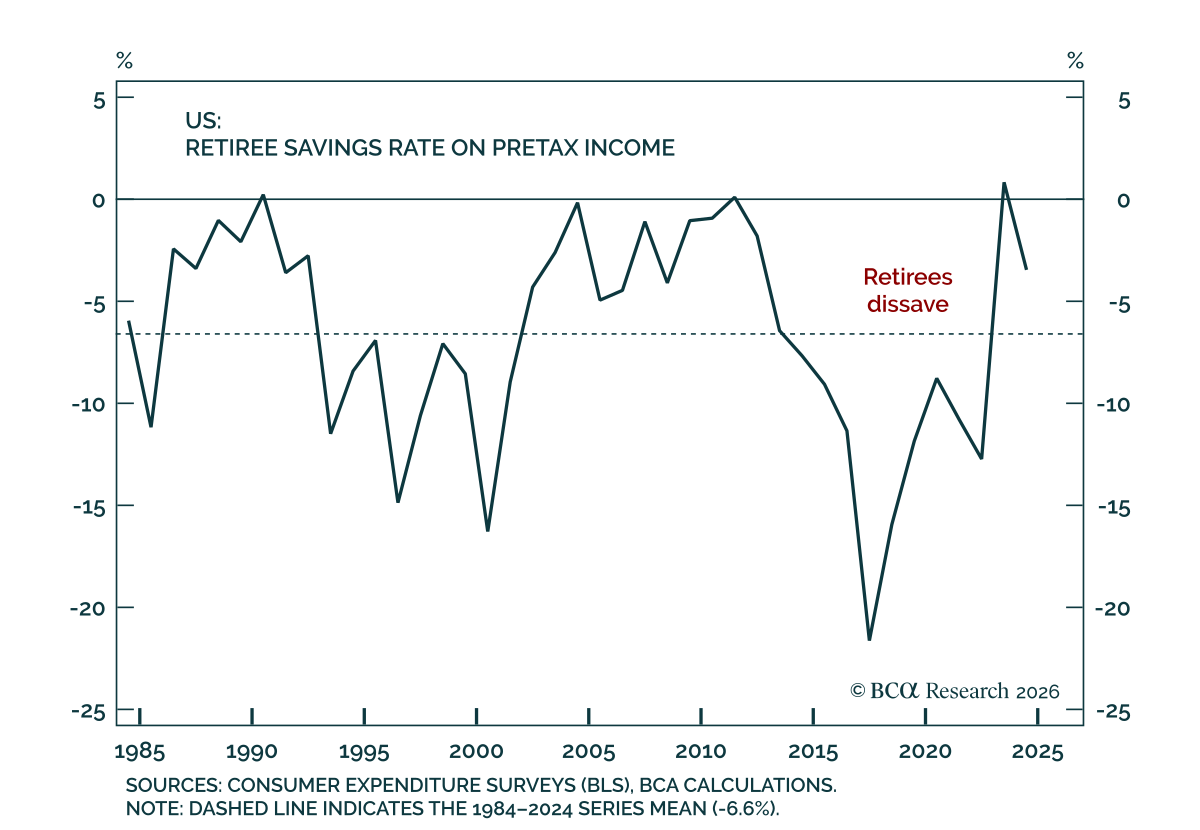
Concerns about the savings rate’s sustainability ease after adjusting for retirements and capital gains. The US economy continues to grow at a pace that is neither too hot nor too cold and investors should remain fully invested in risk assets.
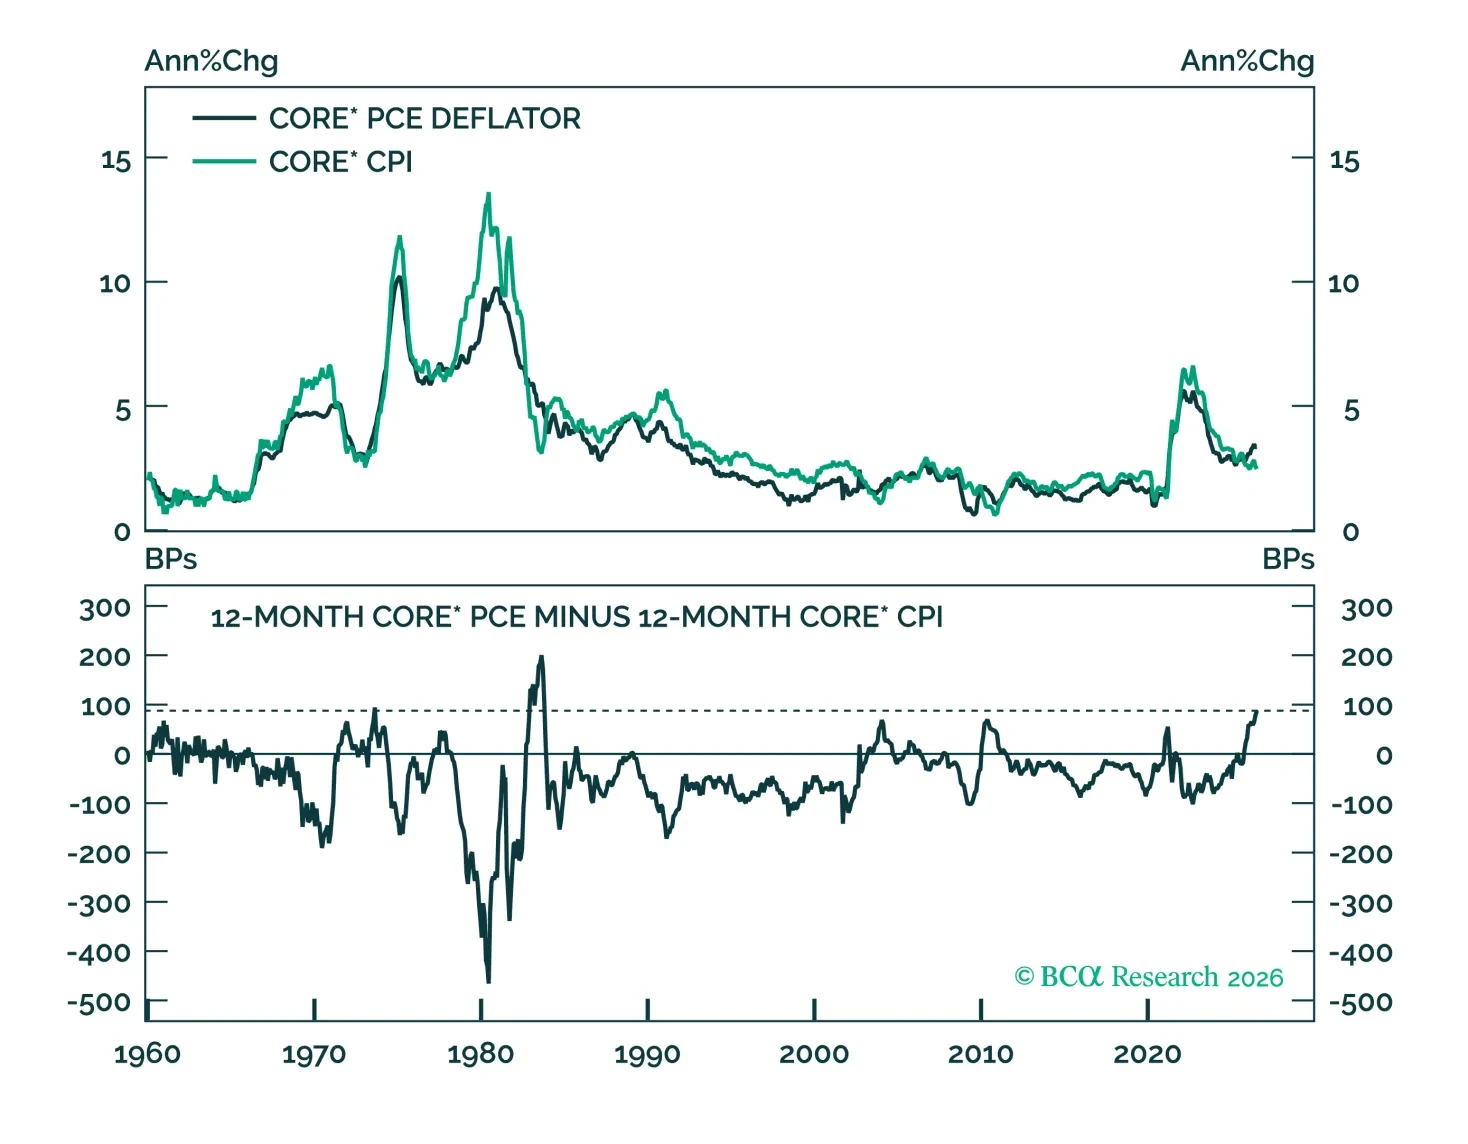
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
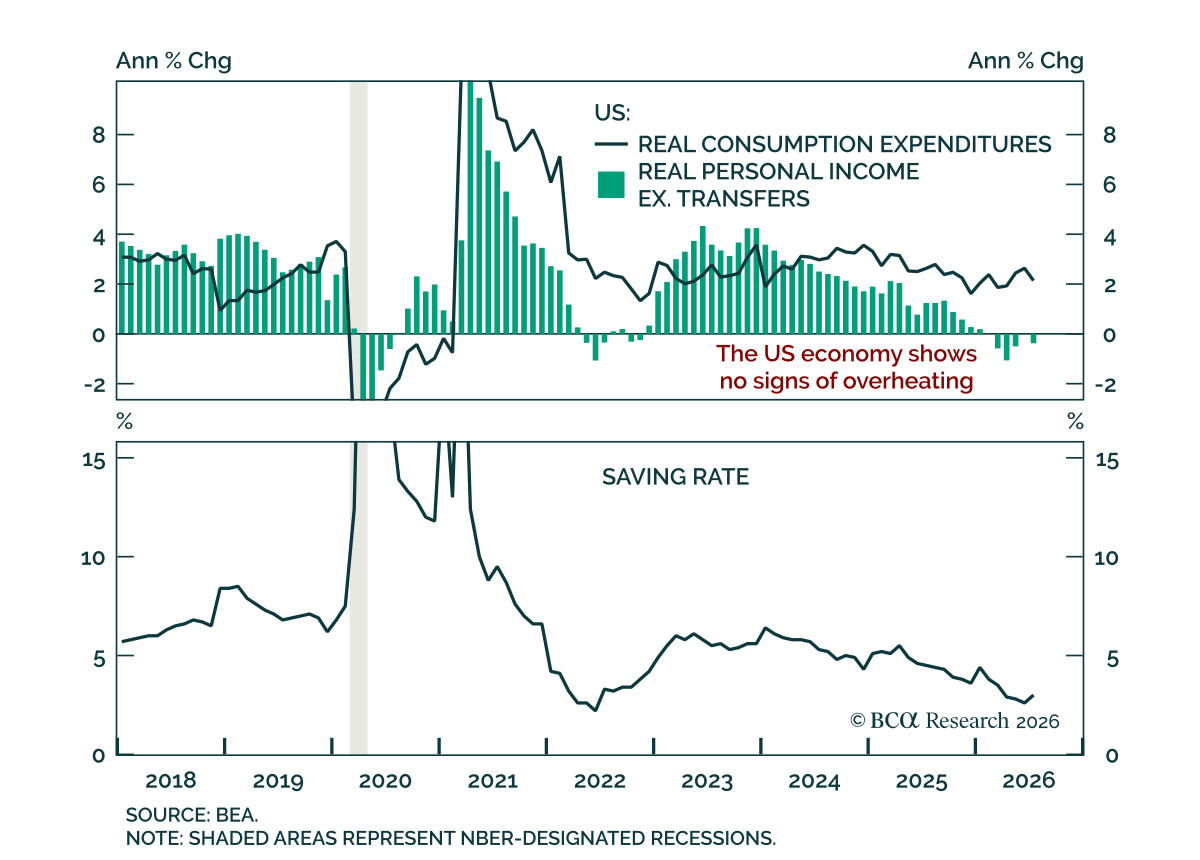
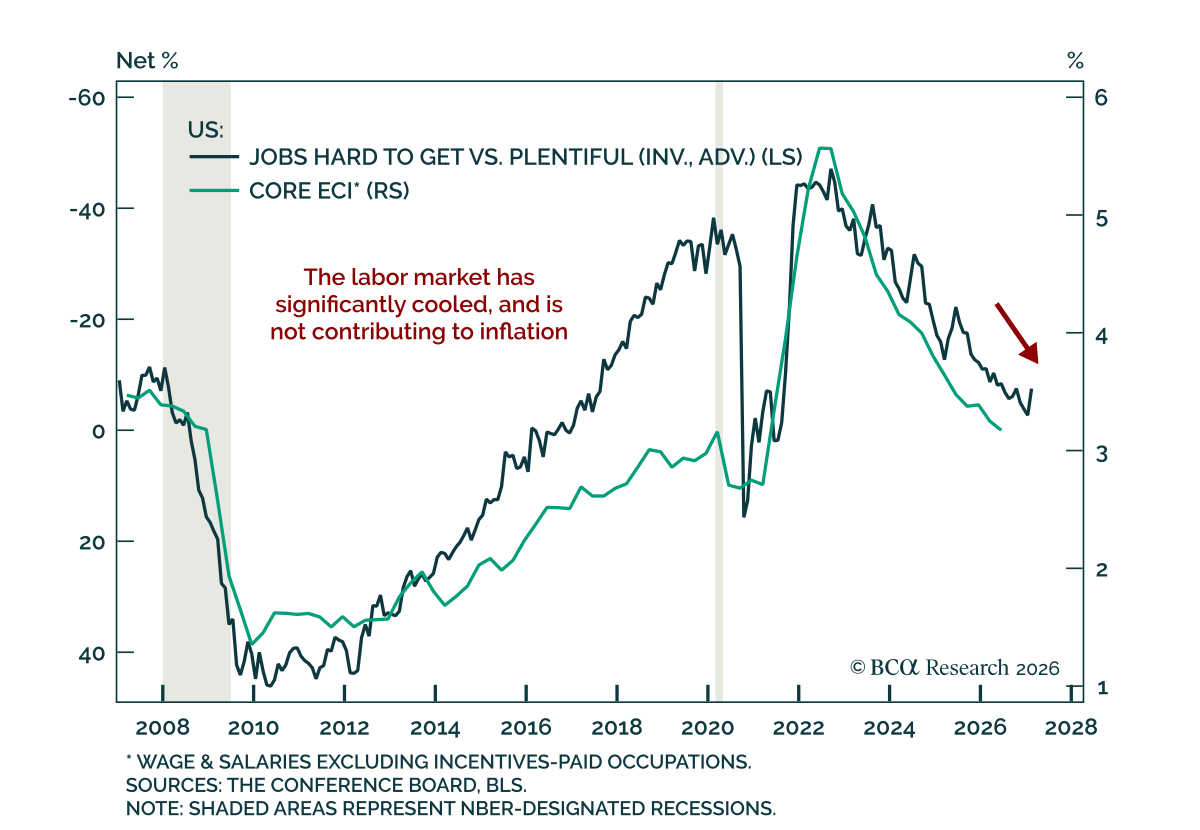
 

The July Personal Income and Outlays report showed firmer household income, flat real spending, and no renewed acceleration in inflation, giving the Fed little reason to tighten more aggressively. Nominal spending rose 0.2% m/m, slightly above estimates, but…
The August Conference Board survey was mixed, but a rebound in labor perceptions and stronger current conditions point to continued consumer resilience. The headline index fell to 89.4 from a downwardly revised 90.2, missing estimates. Consumers’ assessment…
Special Report

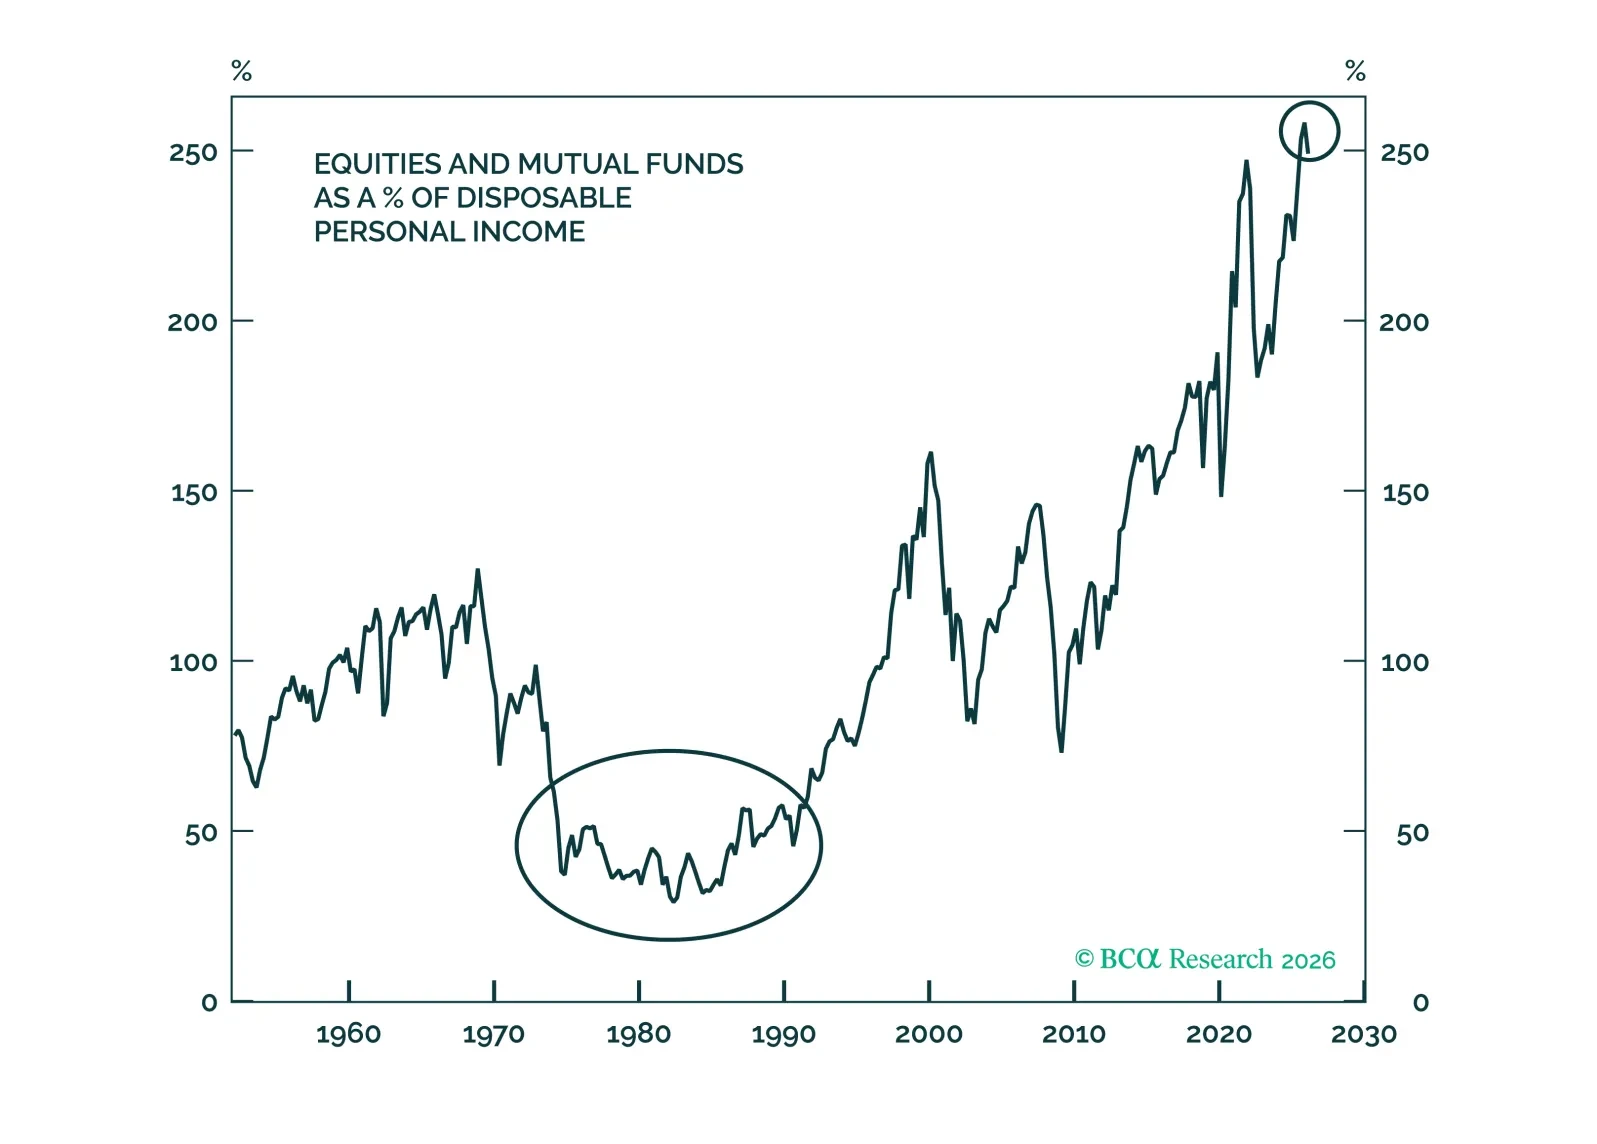
Four decades of robust stock market gains have positioned the equity wealth effect to play a larger role in the business cycle.
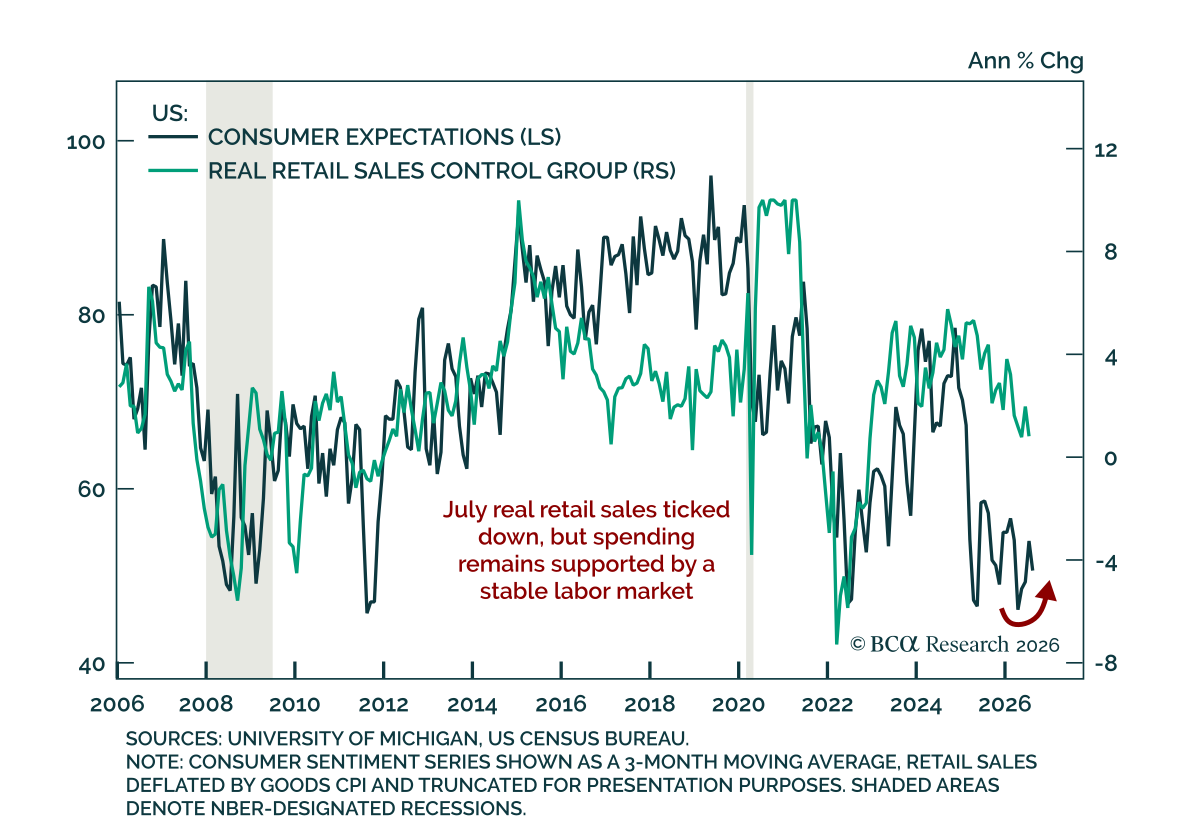
The latest consumer data show cooling momentum, reinforcing that the US economy is not overheating while leaving the broader equity case intact. July retail sales were weaker than estimates across the board. Headline sales fell 0.6% m/m, the core measure…
Special Report

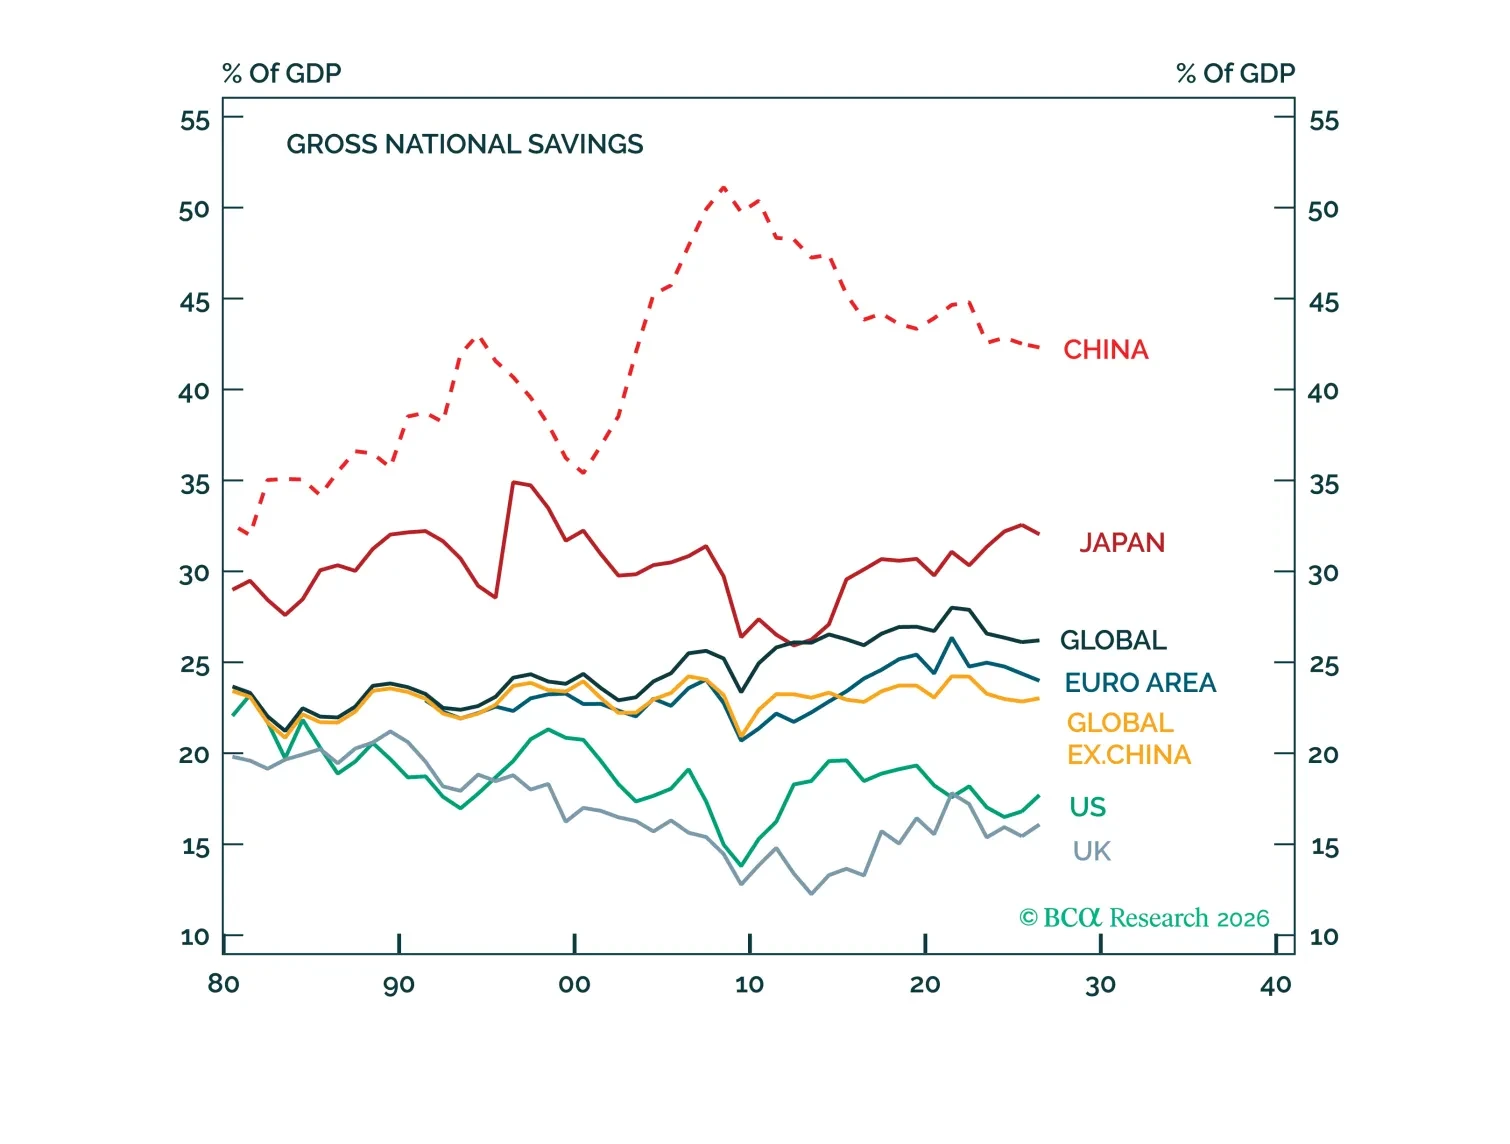
China does not produce too much. It spends too little. The only viable way for China to reduce investment without raising unemployment is by lowering national savings. Doing so is likely to be politically challenging, however. This suggests that China will suffer from subpar growth and deflationary pressures for the foreseeable future.
As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.