Financial Markets
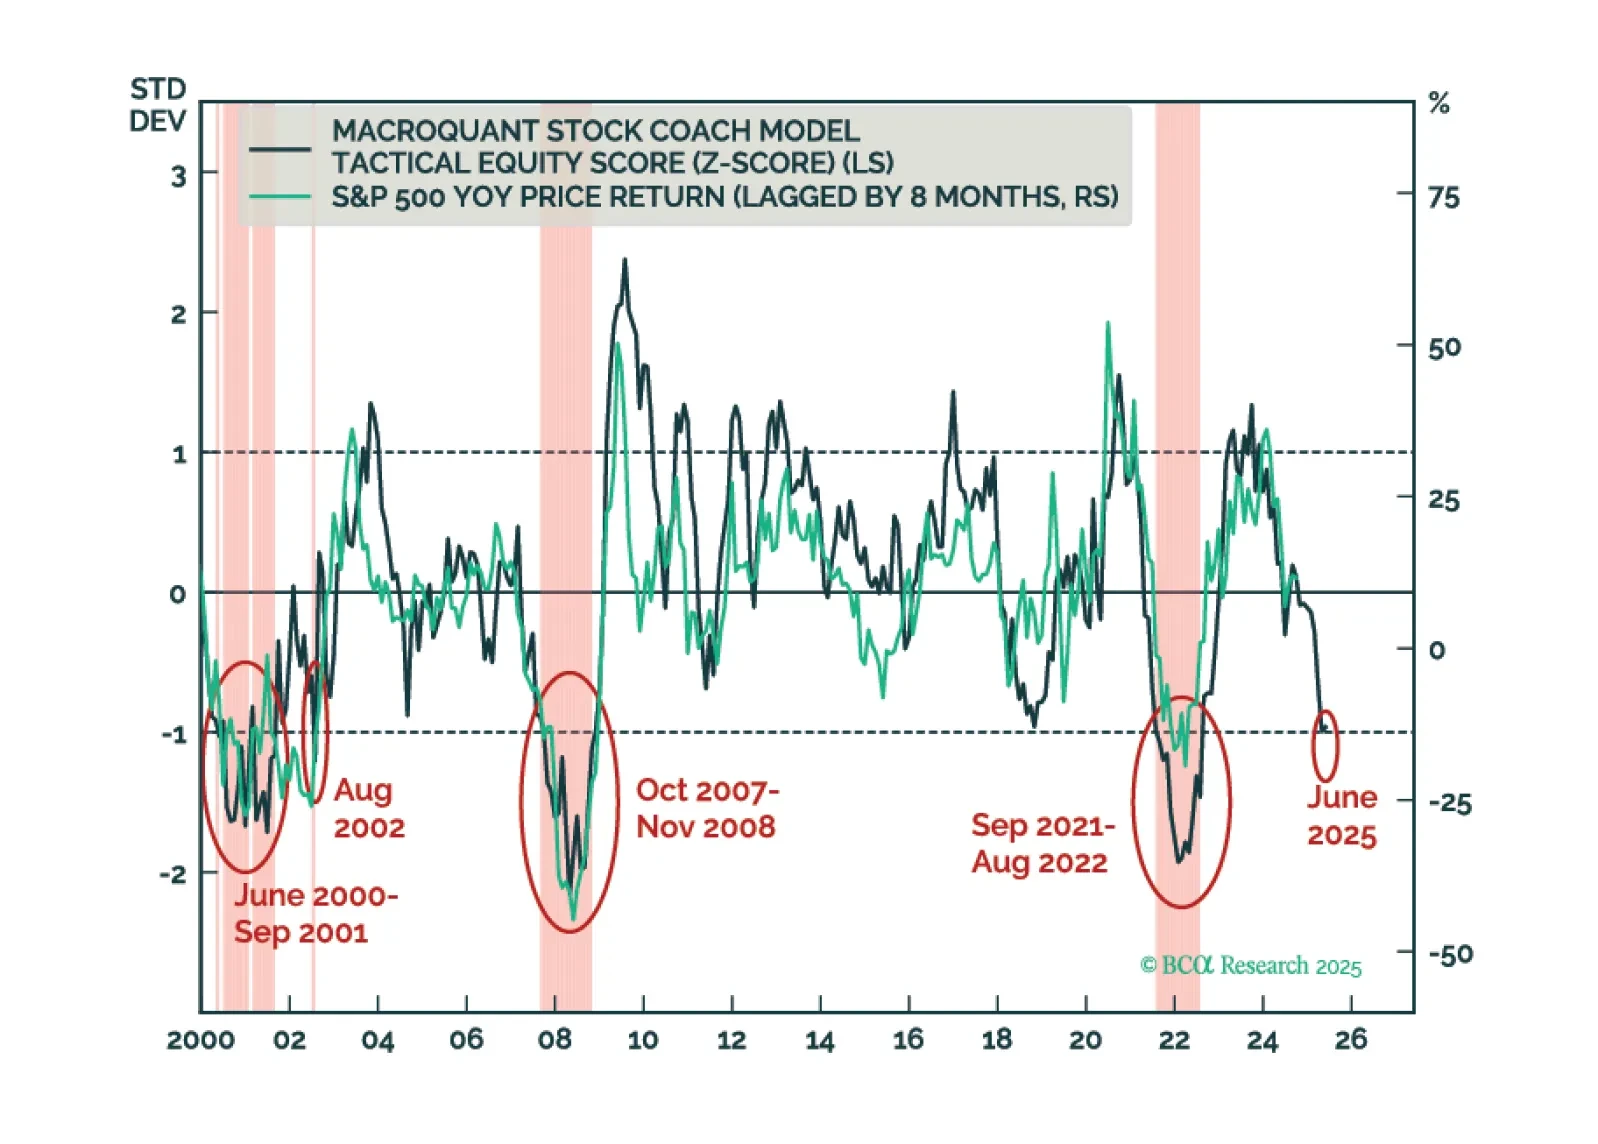
Investors should modestly underweight equities in their portfolios and look to turn more aggressively defensive once the whites of the recession’s eyes are visible. We think that will happen within the next few months.
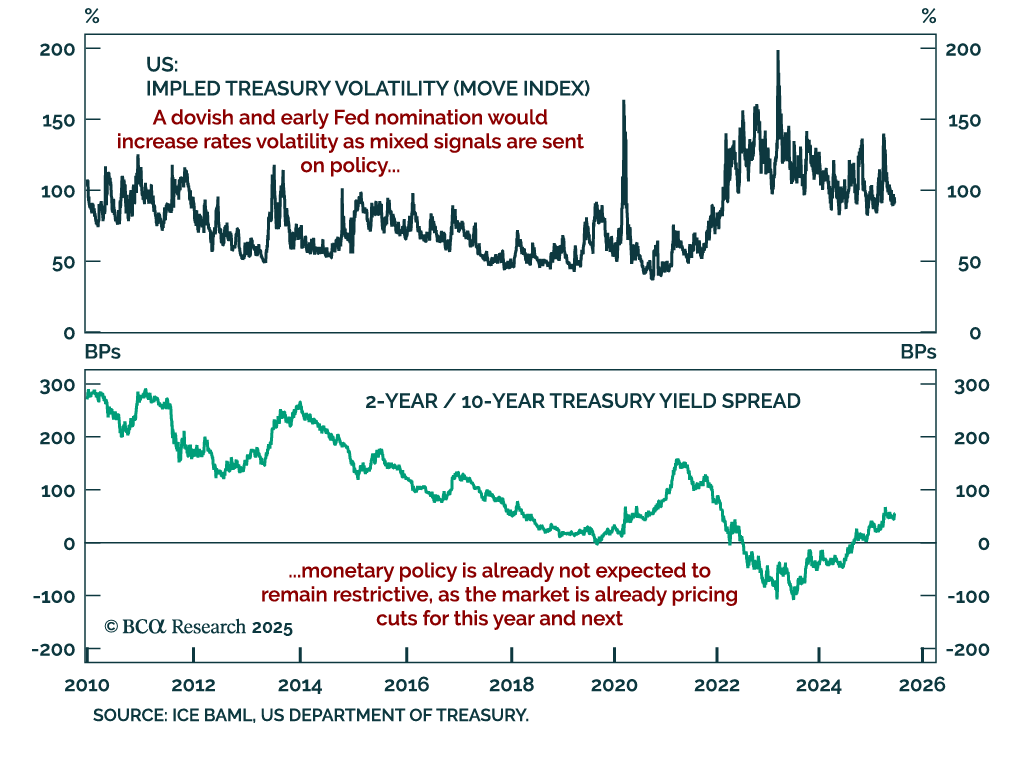
A dovish early Fed nominee would increase volatility in rates and FX as markets reassess the credibility of US monetary policy. News reports indicate the Trump administration is considering nominating a Fed successor ahead of the end of Chairman Powell’s…
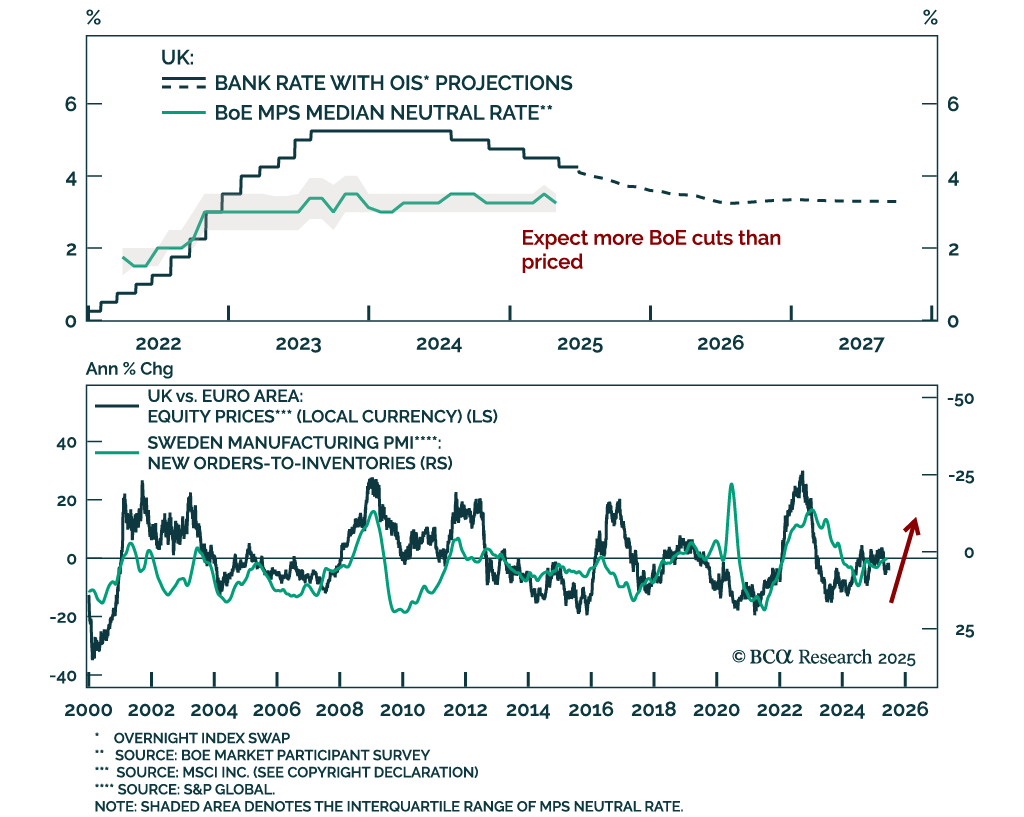
Our Global Fixed Income, FX, and European strategists expect aggressive BoE easing amid disinflation and labor market weakness, supporting an overweight in Gilts and UK equities versus the euro area. While UK productivity remains sluggish, a recovery in labor…
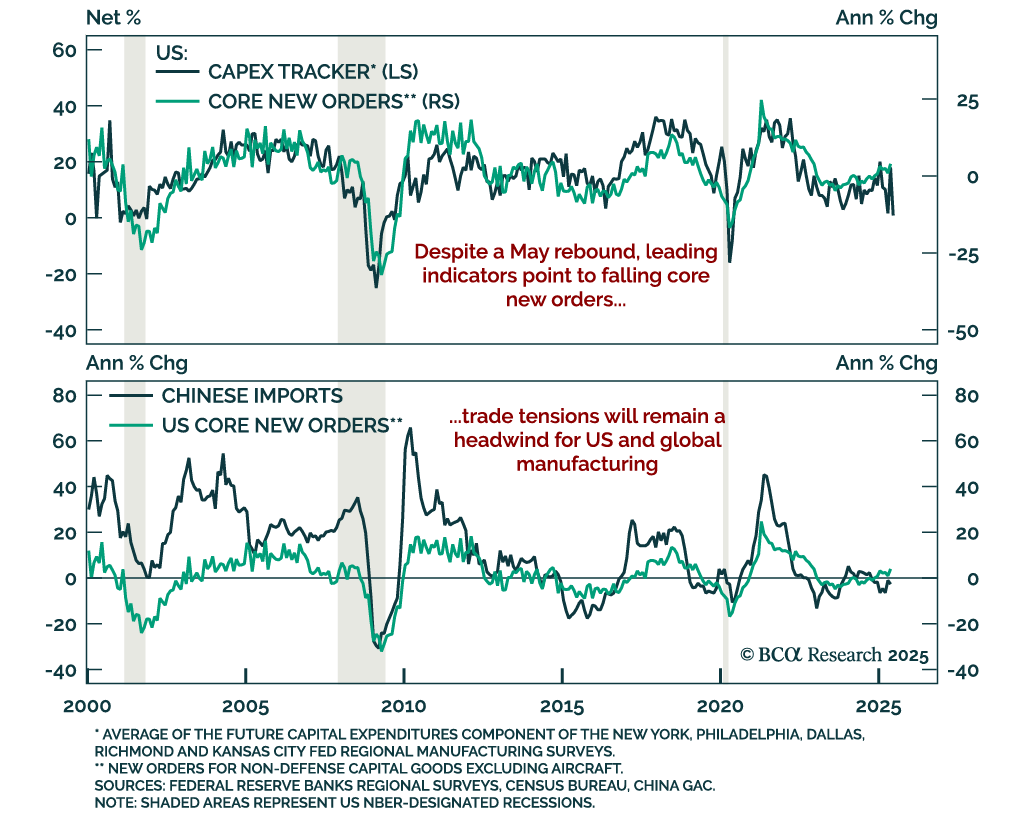
Headline strength in US capital goods orders is unlikely to last, reinforcing our defensive stance and preference for steepeners. New orders for core capital goods (nondefense ex-aircraft) rose 1.7% m/m in May, beating expectations after a 1.5% drop in April.…
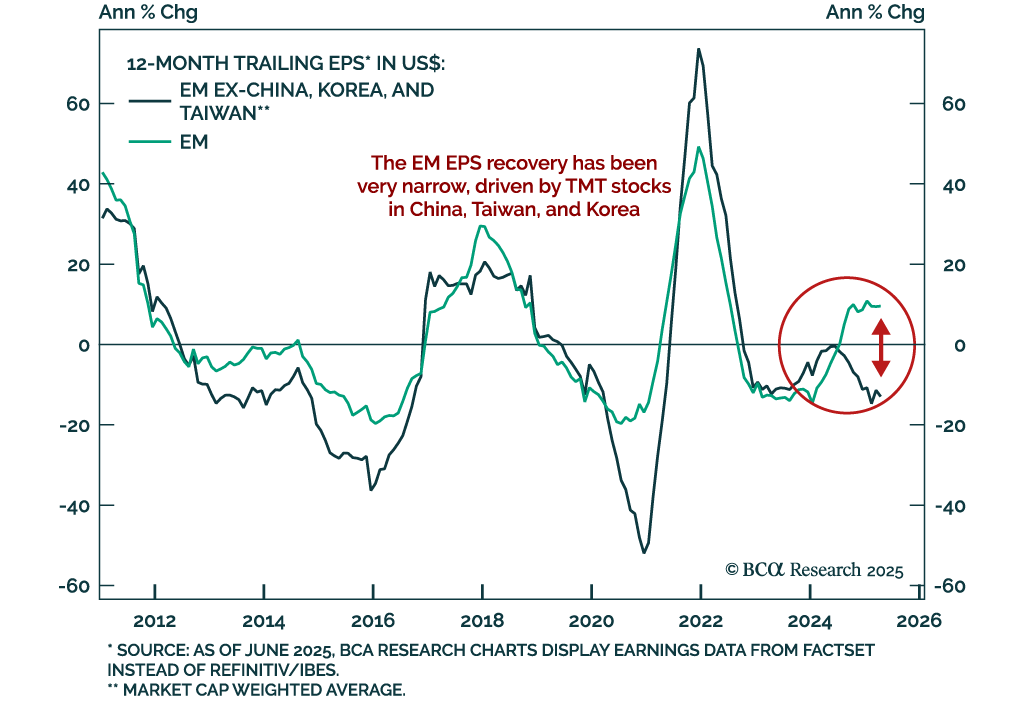
BCA’s EM strategists remain downbeat on EM equities despite a bearish US dollar view, citing profit headwinds and limited valuation support. The ongoing EM earnings recovery has been narrowly concentrated in TMT sectors across China, Taiwan, and Korea,…
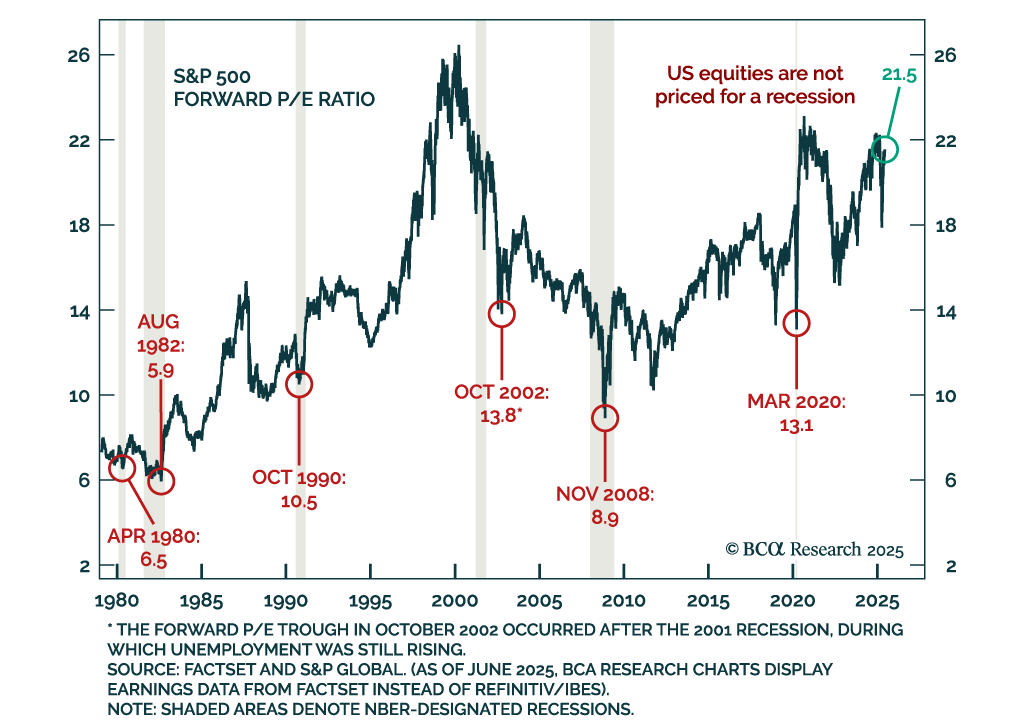
Geopolitical risks and fragile margins reinforce a defensive allocation stance, as oil shocks and high US equity valuations pose growing downside risks. At this month’s Views Meeting, our strategists discussed the potential fallout from an Iran-Israel…
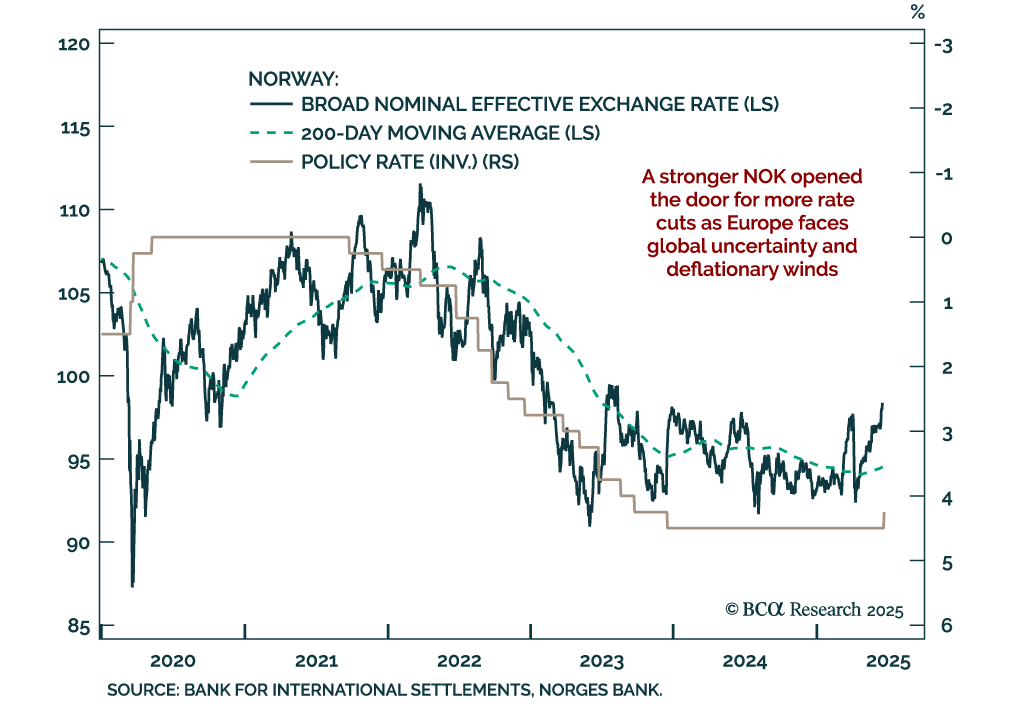
A stronger Norwegian krone has opened the door to more rate cuts, making Norwegian government bonds more attractive. Our Chart Of The Week comes from Jeremie Peloso, European Strategist. With its surprise 25 basis point cut, the Norges Bank made its first…
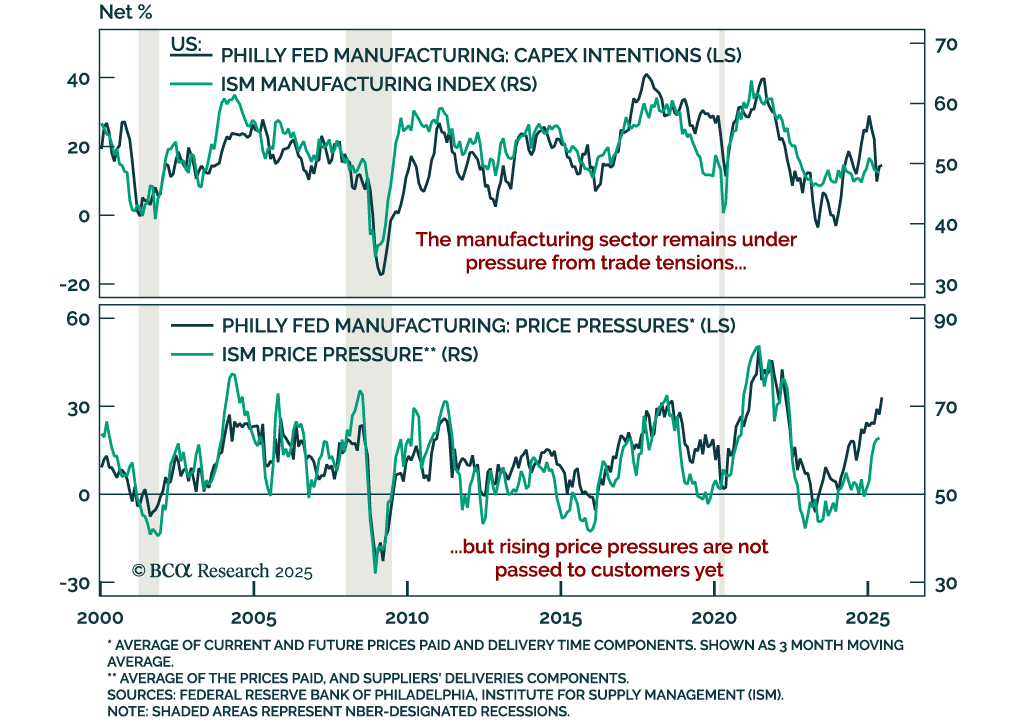
Worsening manufacturing momentum supports a long duration stance as recession risks remain elevated. The June Philly Fed survey came in below expectations, unchanged at -4.0. While shipments increased, new orders decelerated and employment measures fell.…
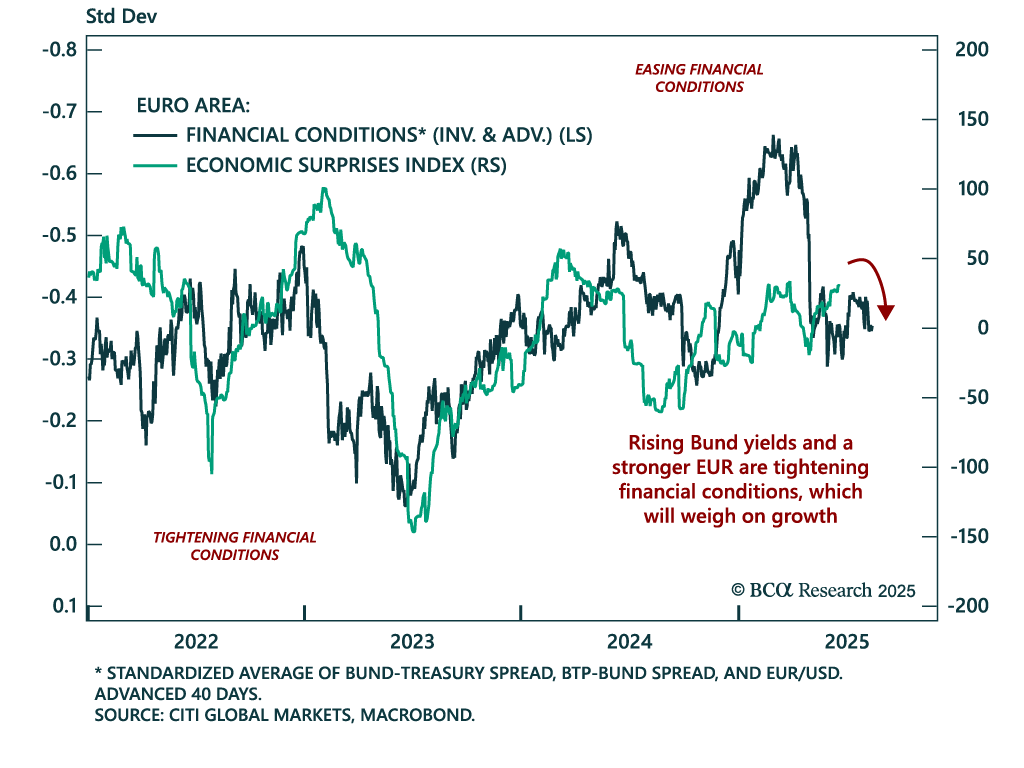
Tightening financial conditions, deflationary headwinds, and rising geopolitical risks argue for short-term caution on European assets. European equities have outperformed in 2025, with the EURO STOXX 50 beating the S&P 500 and EUR/USD moving higher. This…
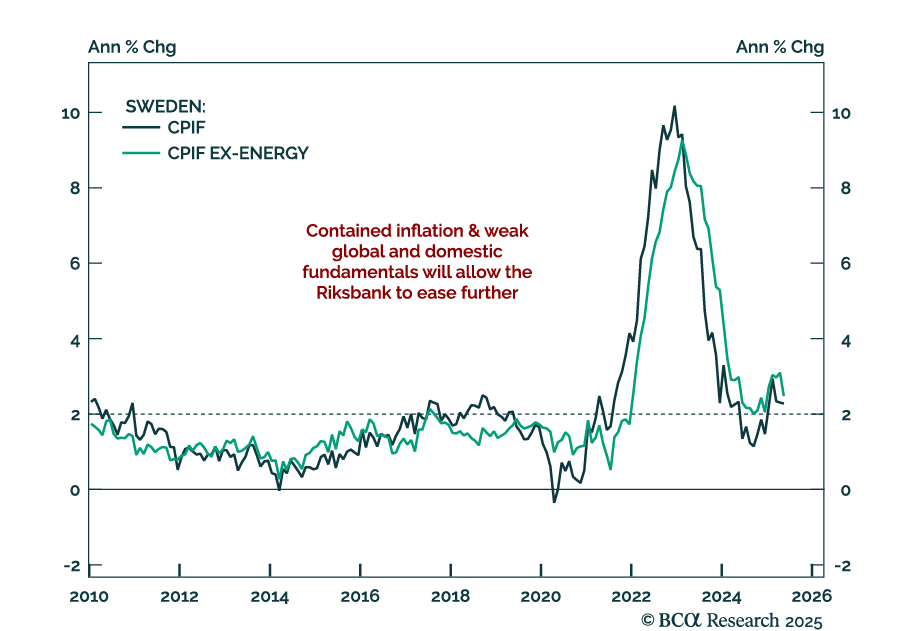
Sweden’s economic fragility and disinflation support further easing, reinforcing our long SEK rates and NOK/SEK trades. The Riksbank cut rates by 25 bps to 2.0% and projected an additional cut, consistent with prior OIS pricing. Forecasts for both headline…