Natural Gas
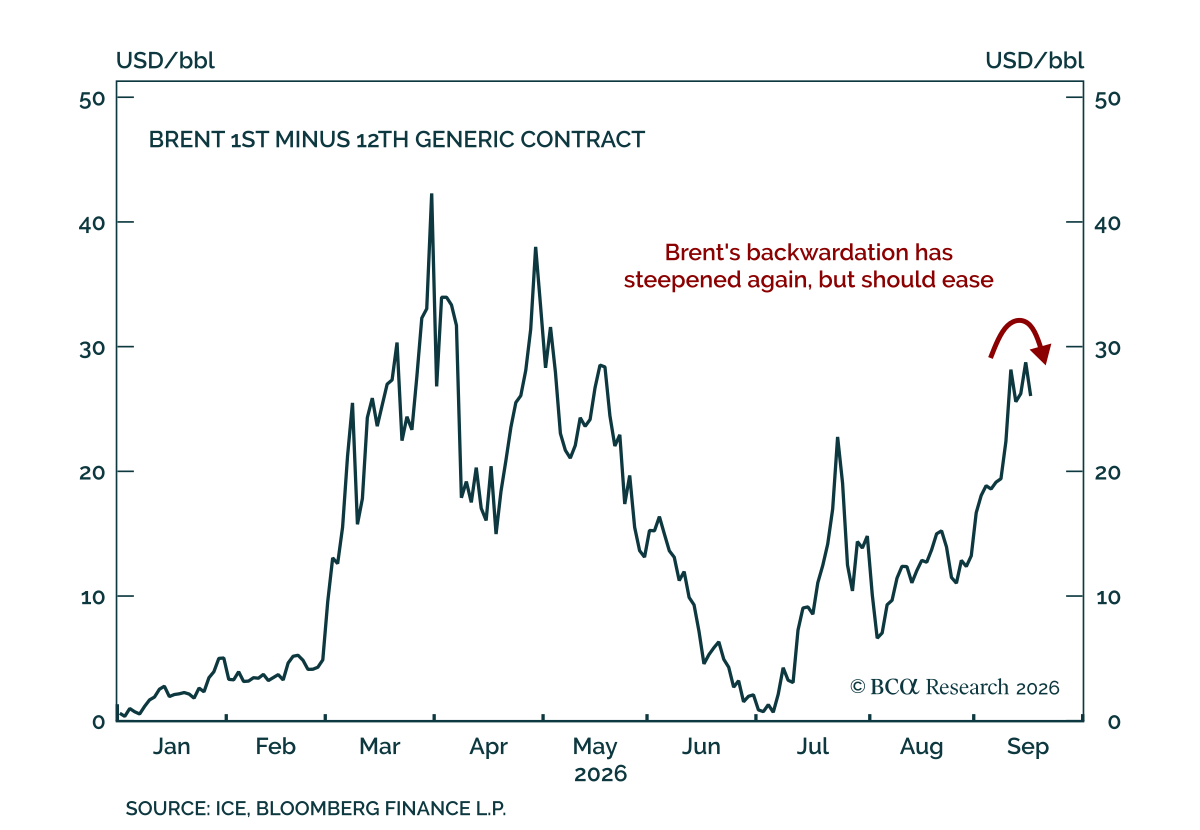
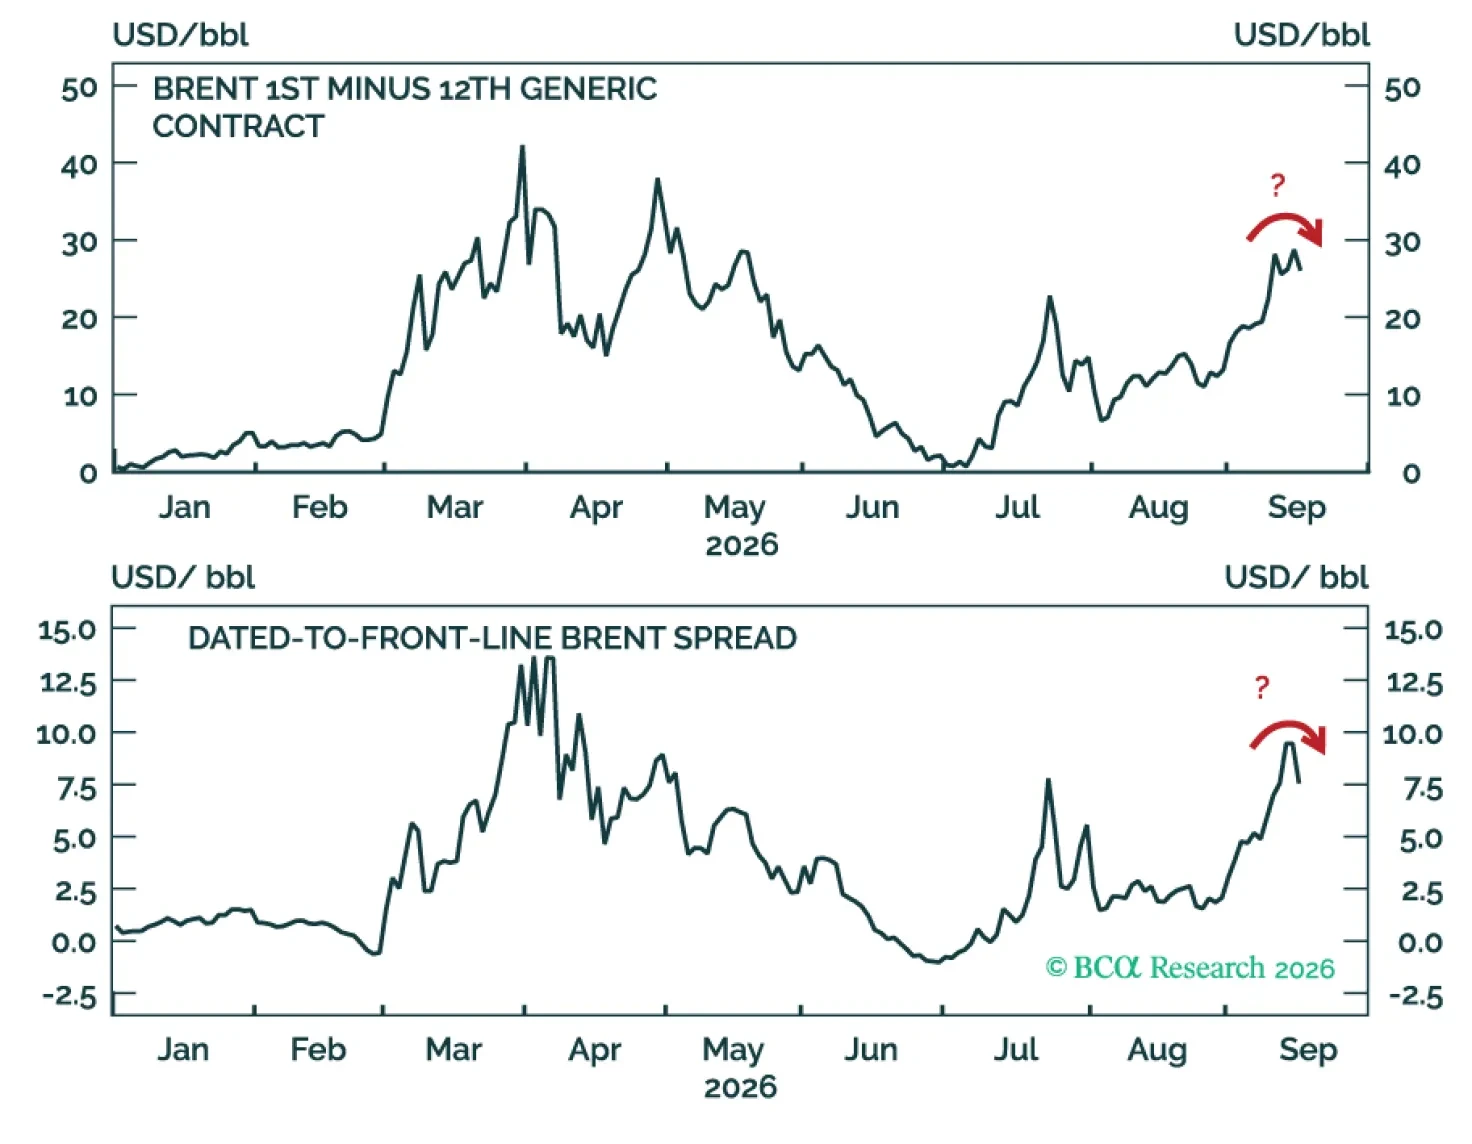
Recent oil market developments expose the limits of the adjustment mechanisms that have cushioned the global market since the Hormuz closure began. Fortunately, Hormuz dark transits have become the dominant shock absorber in recent months, and rising flows should help mitigate the latest supply disruption going forward.

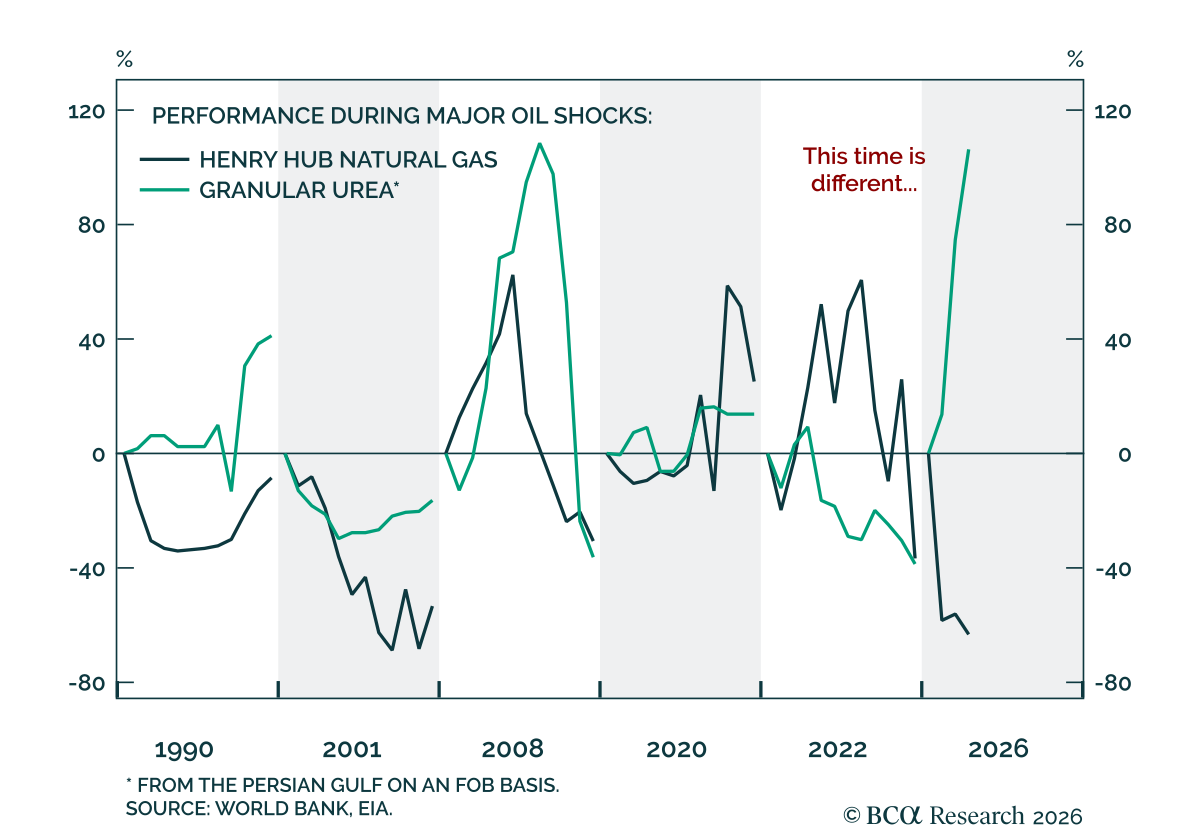

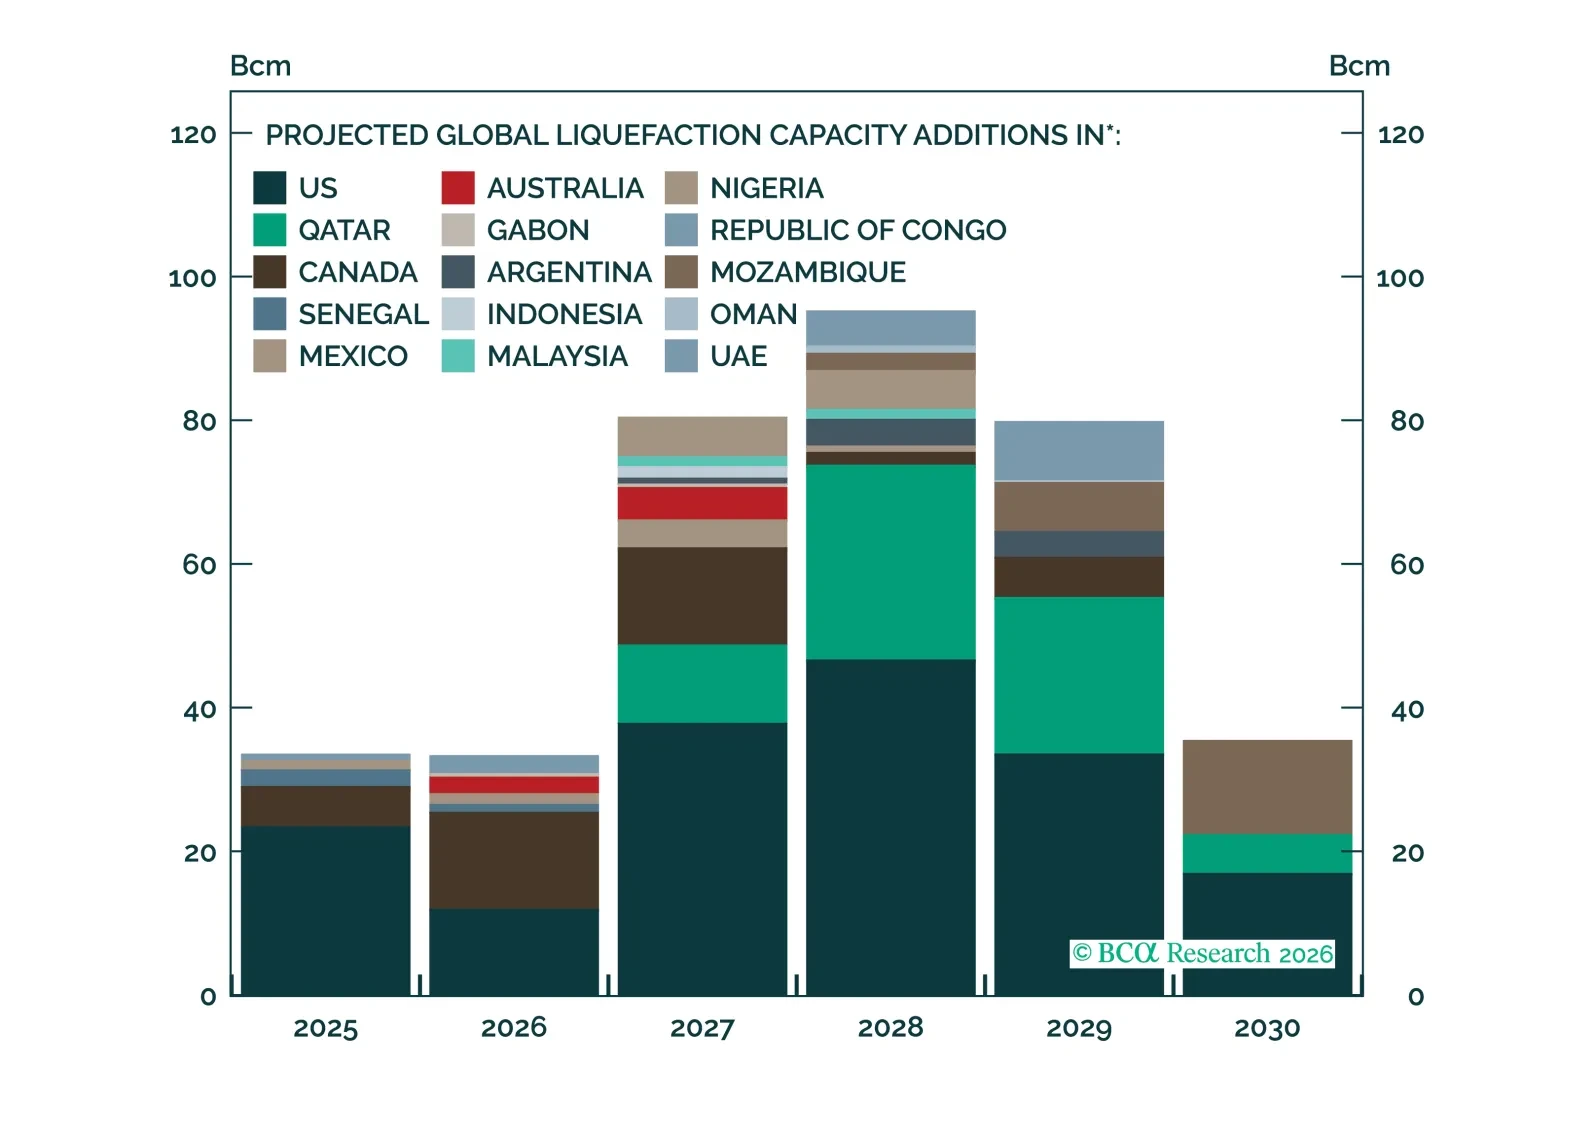
The Iran war has damaged LNG production capacity and halted tanker flows through the Strait of Hormuz. We assess the conflict's impact on LNG markets over cyclical and structural horizons.
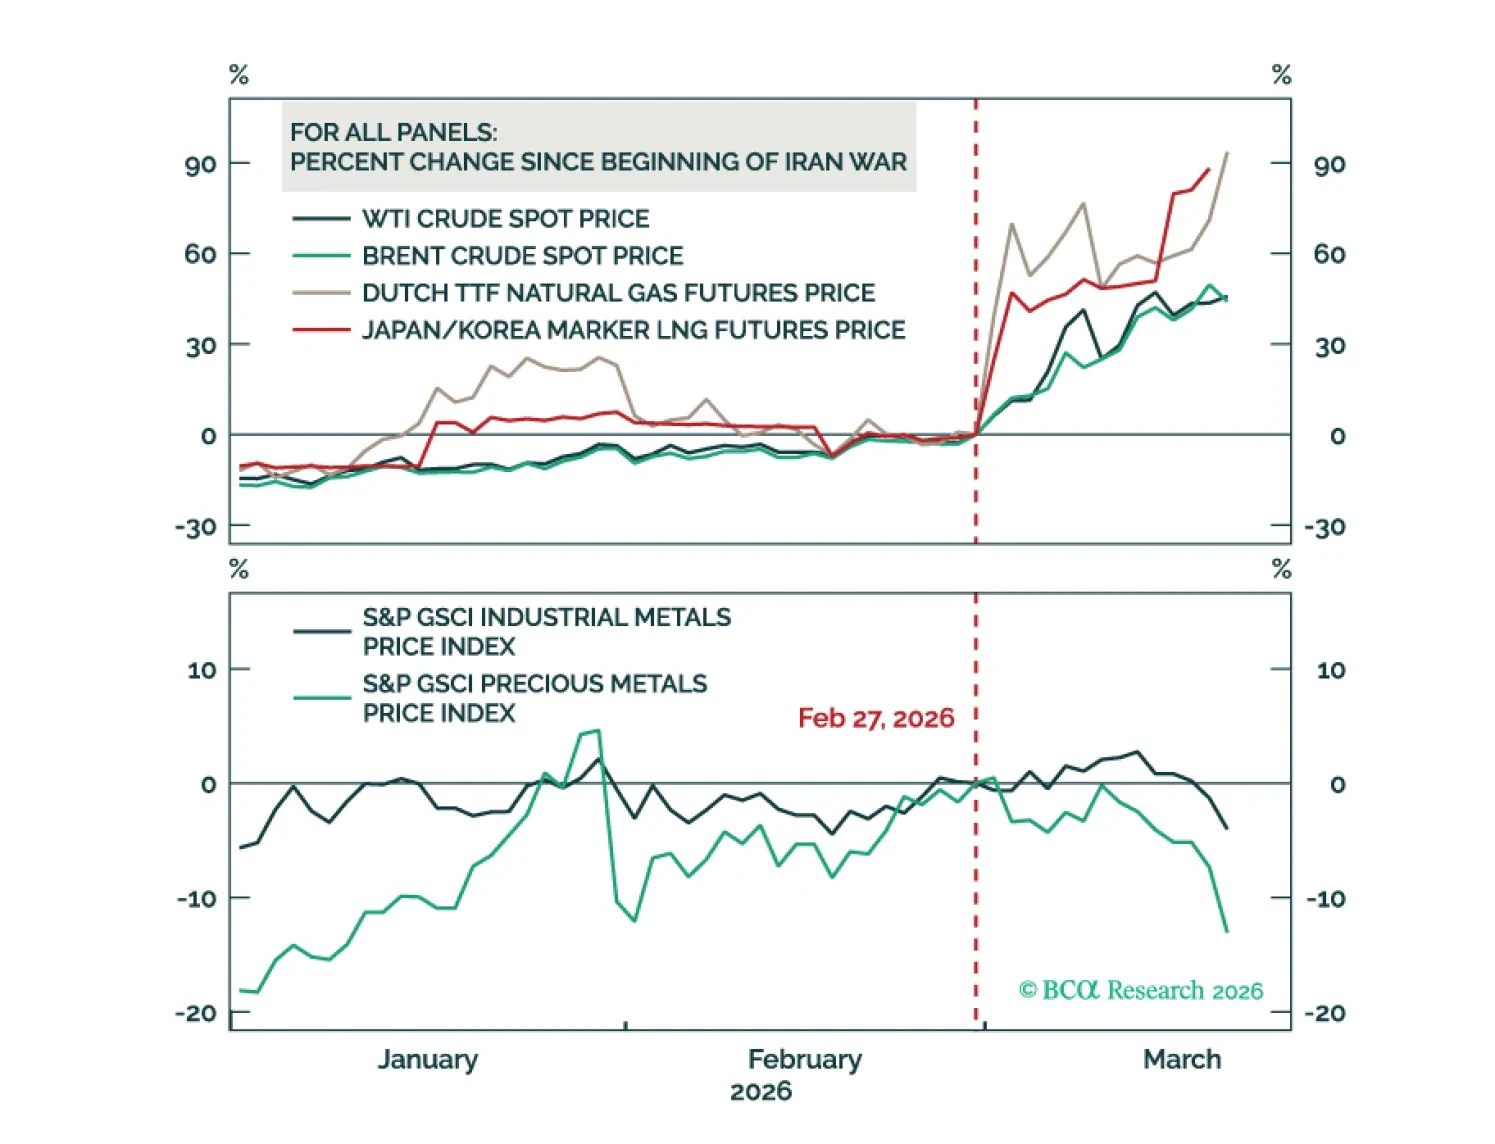
Higher oil prices threaten the global economy, warranting an underweight stance on equities. Over the long haul, industrial metals will fare better than crude.

Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
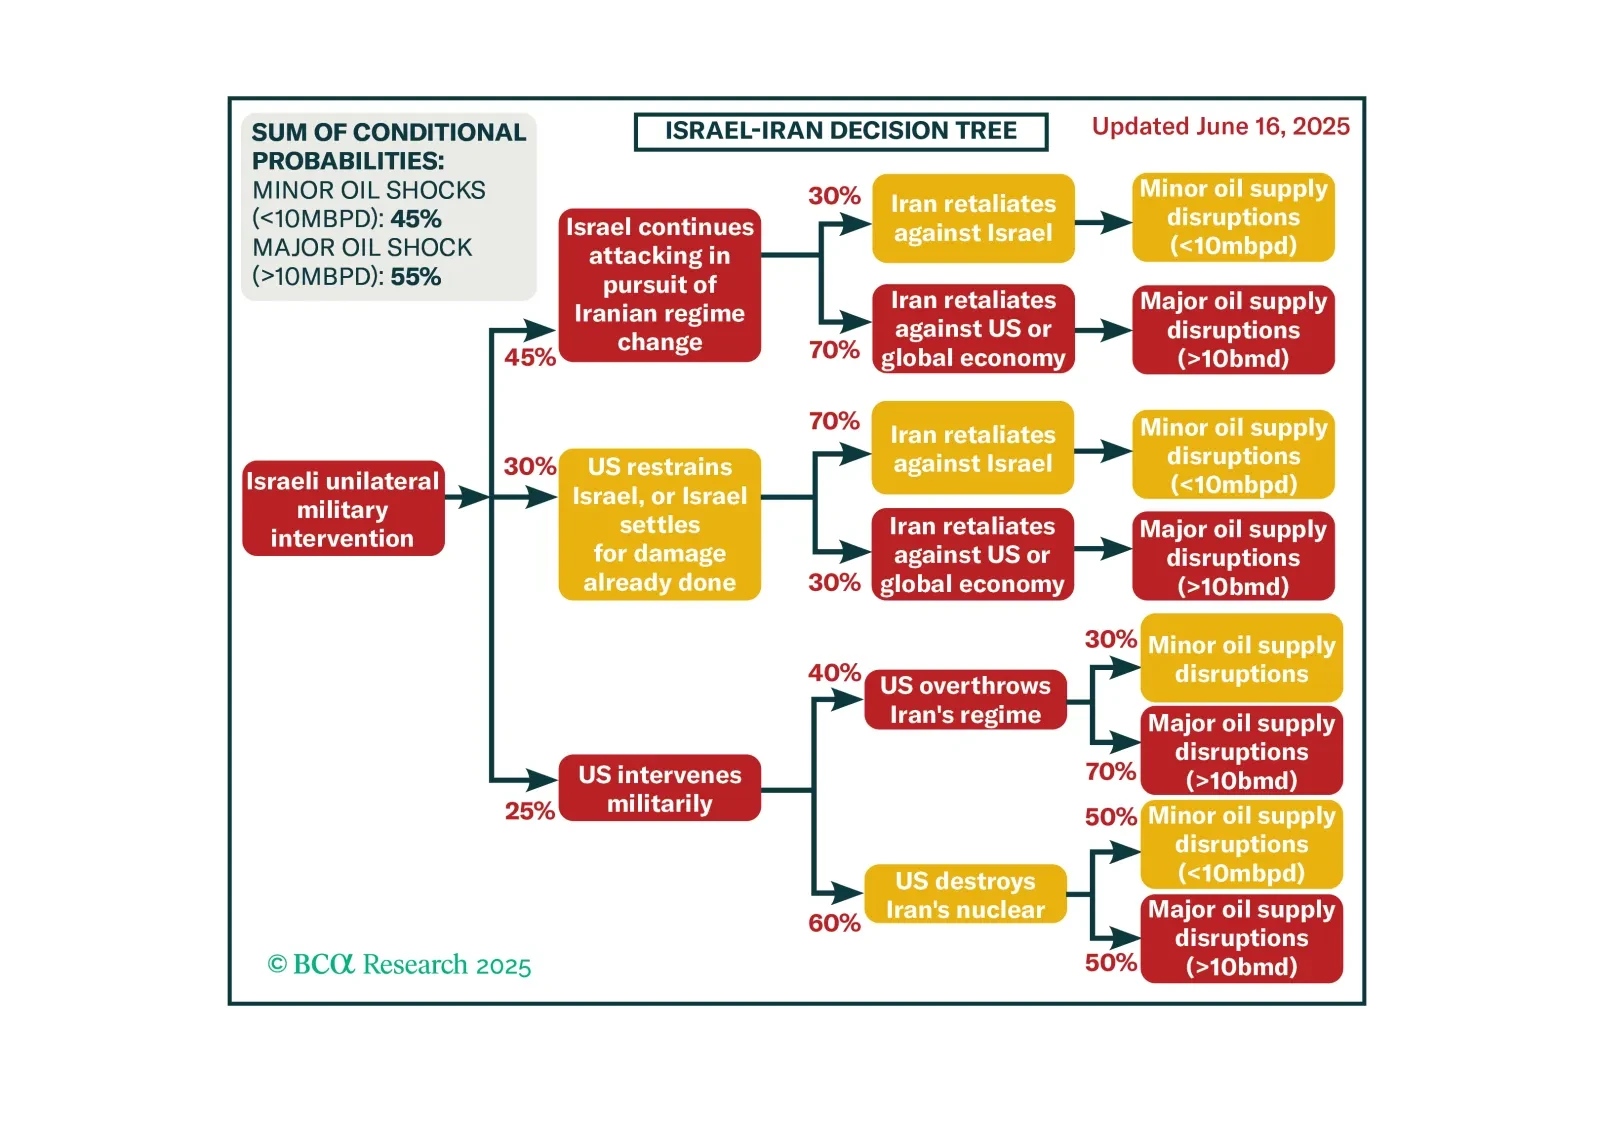
Israel’s attacks on Iran will continue until Iran is forced to strike regional oil supply to get the US to restrain Israel. That may not work. Investors should prepare for a broader economic impact of the conflict.
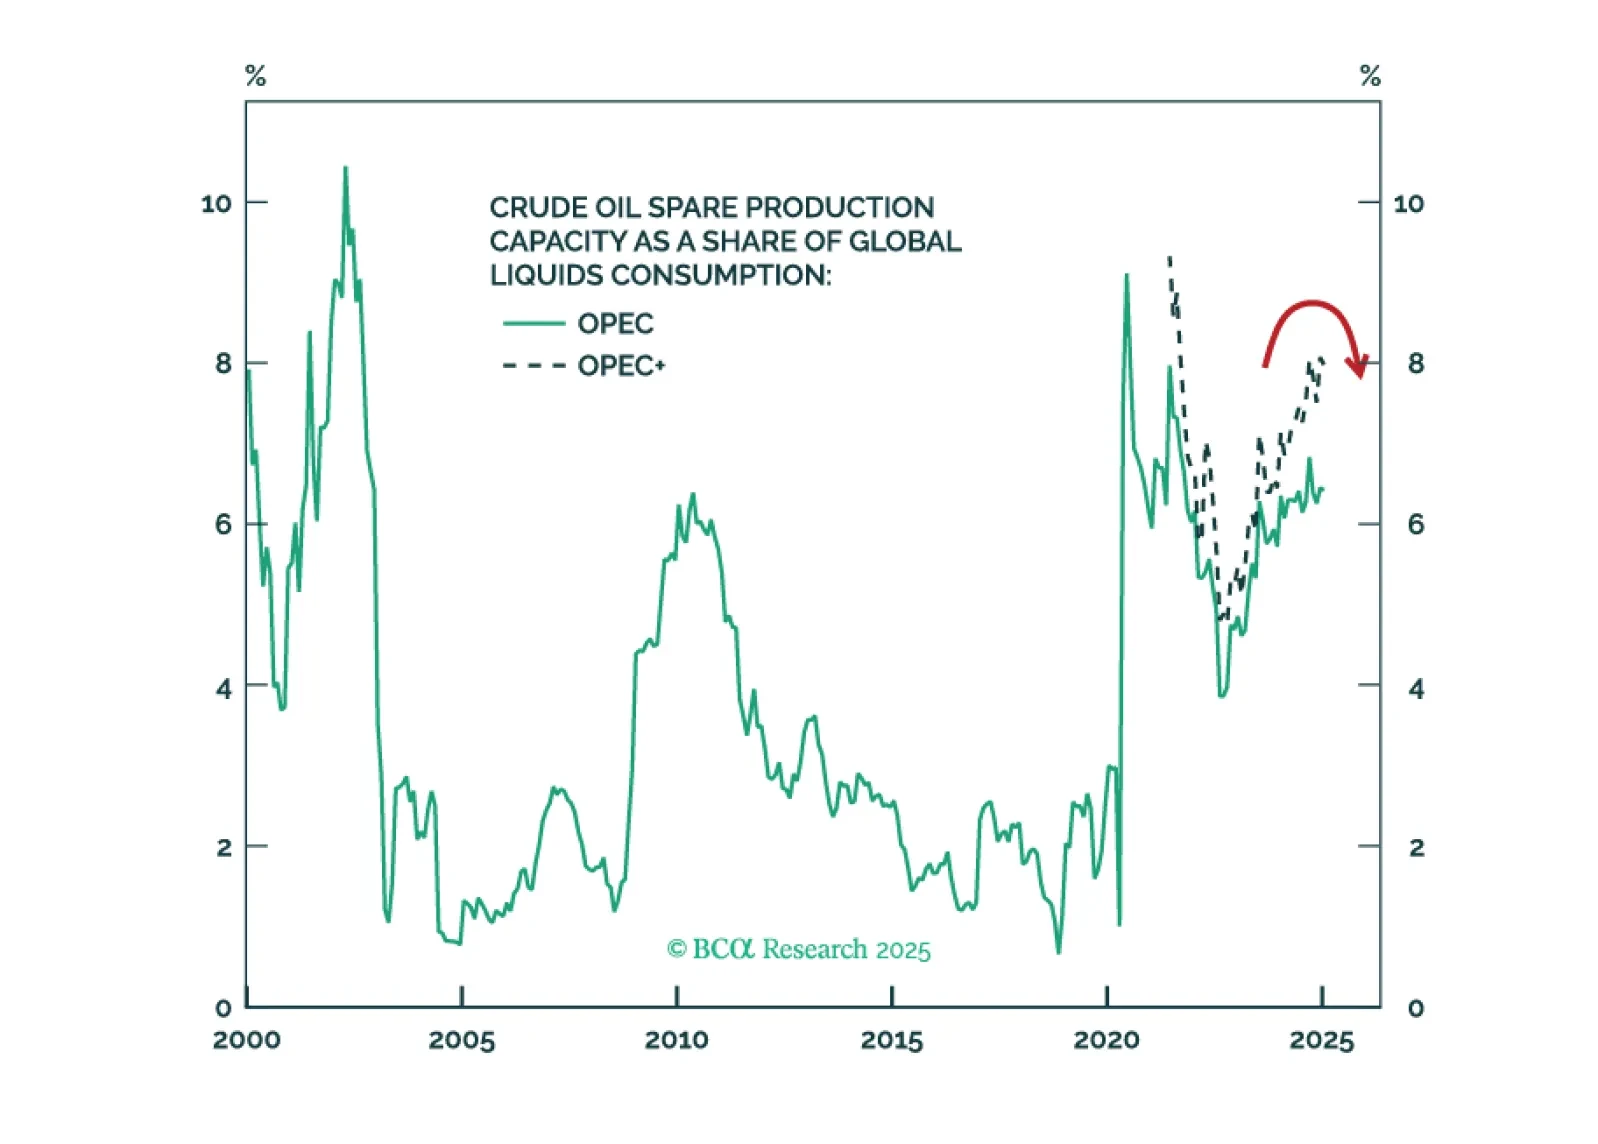
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.