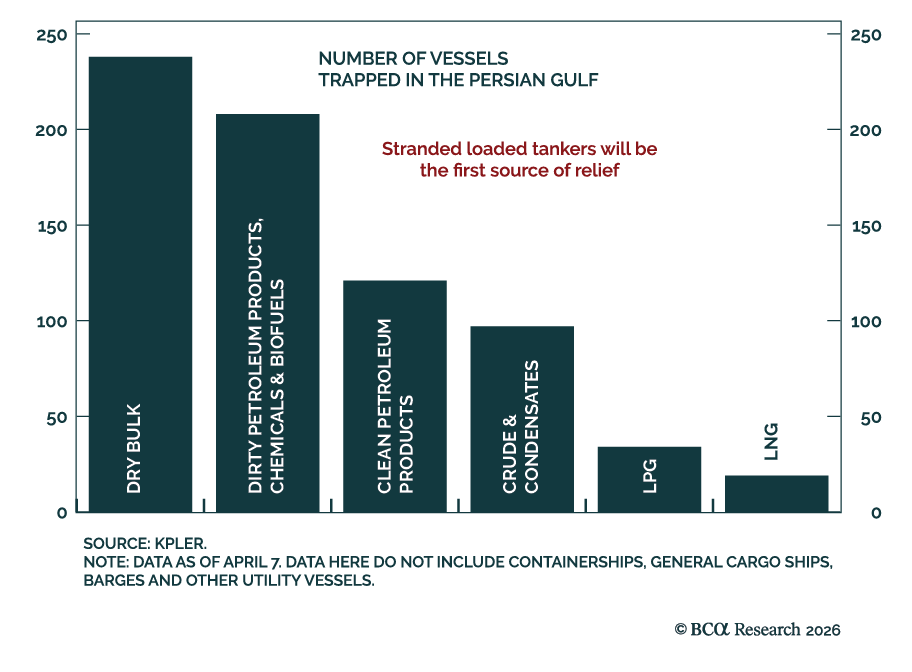
Oil
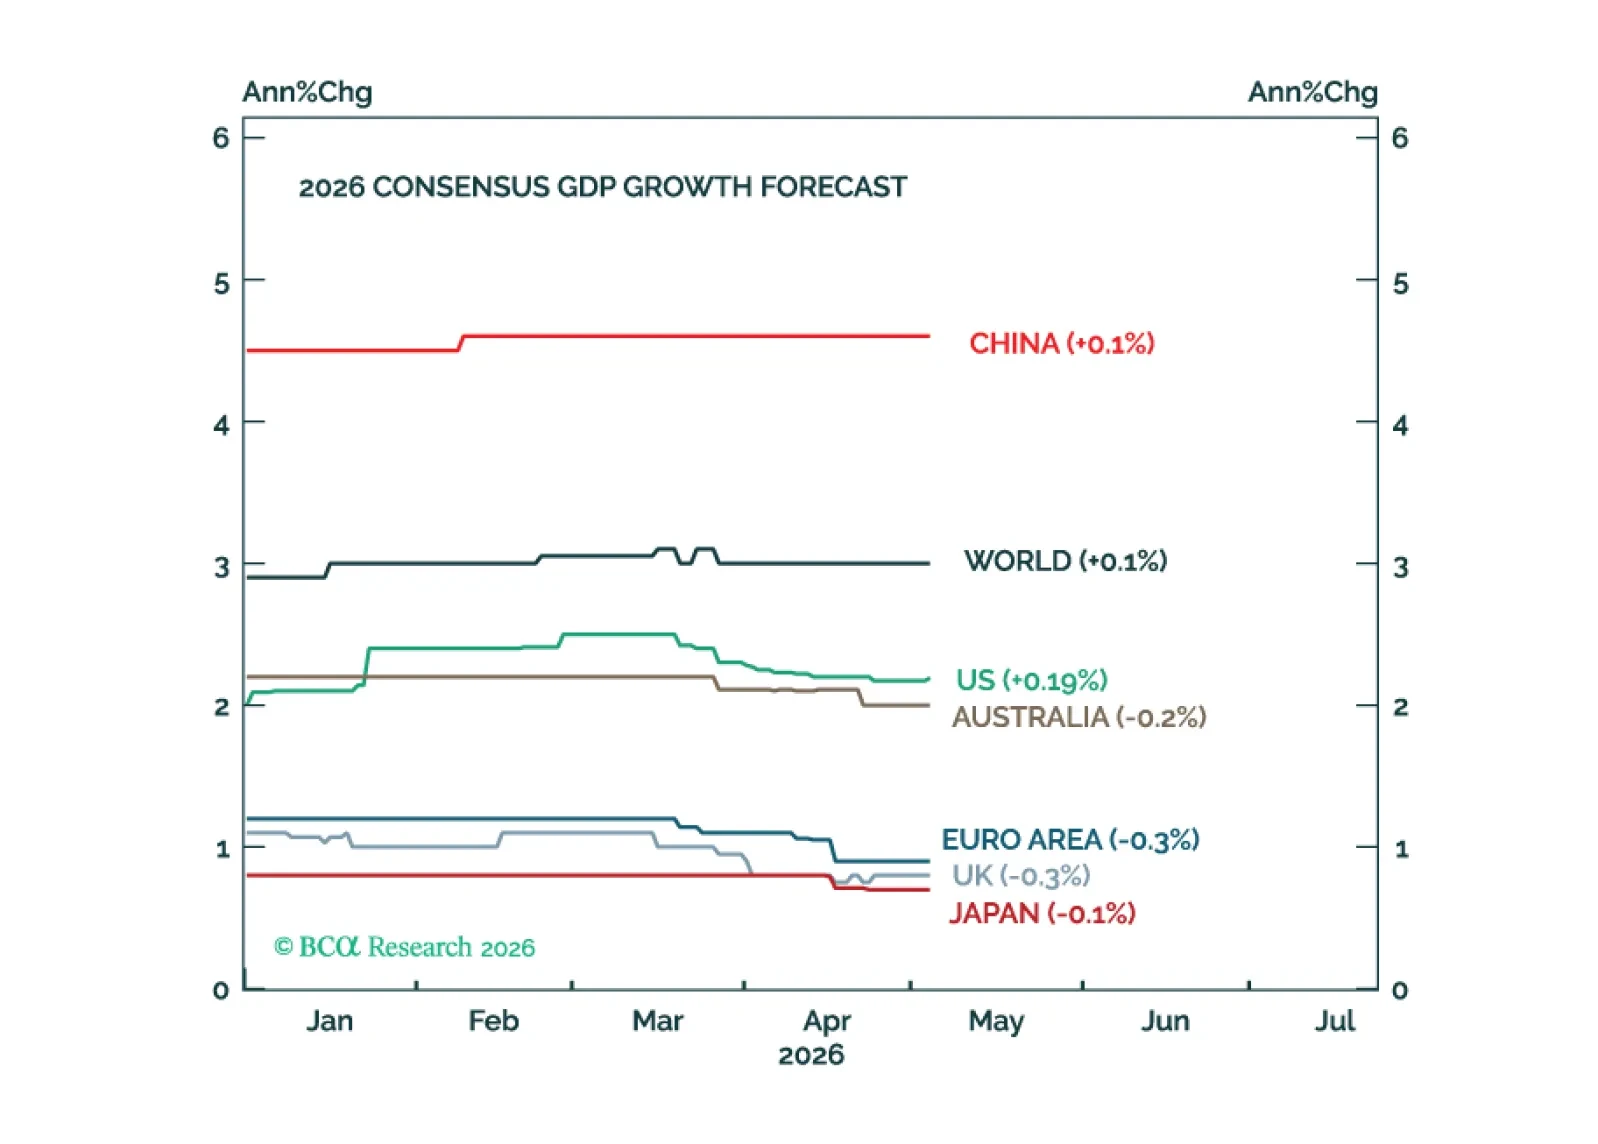
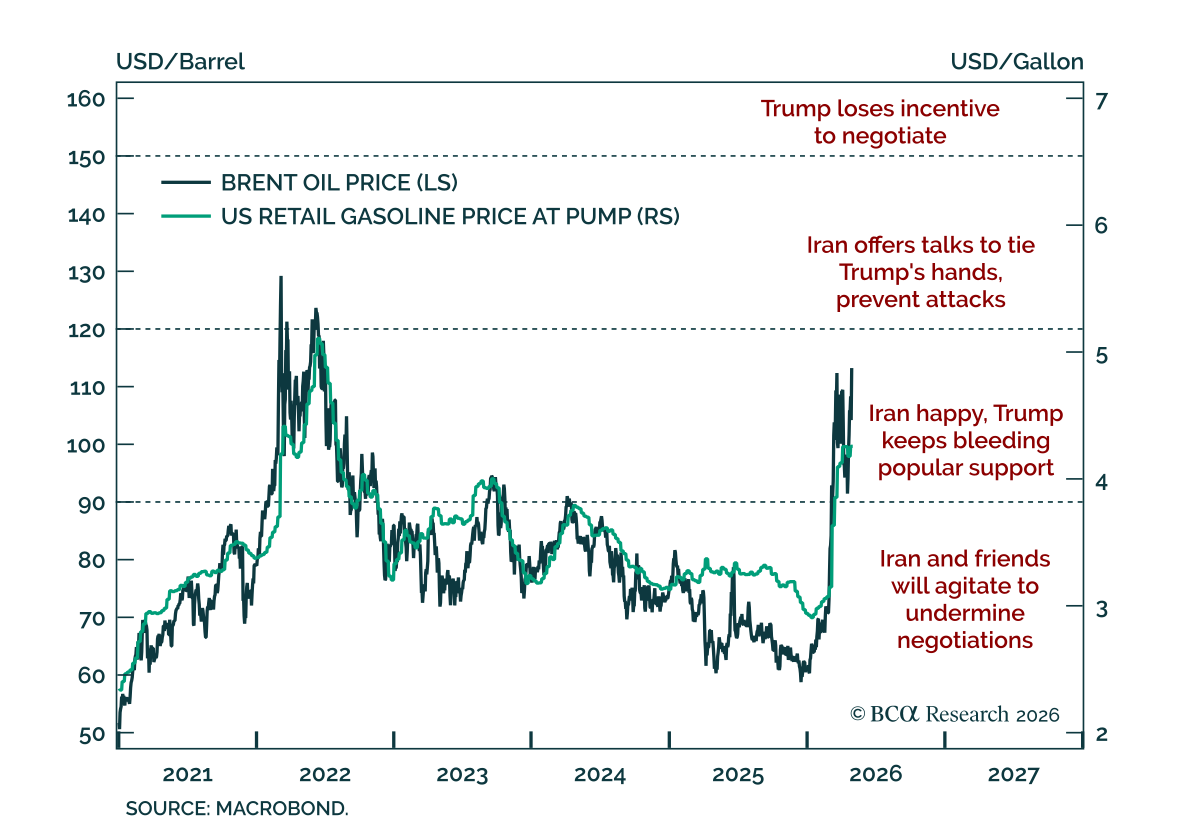
The global economy has weathered the oil shock reasonably well so far. However, the risk of a recession will increase meaningfully if the Strait of Hormuz remains closed into June.
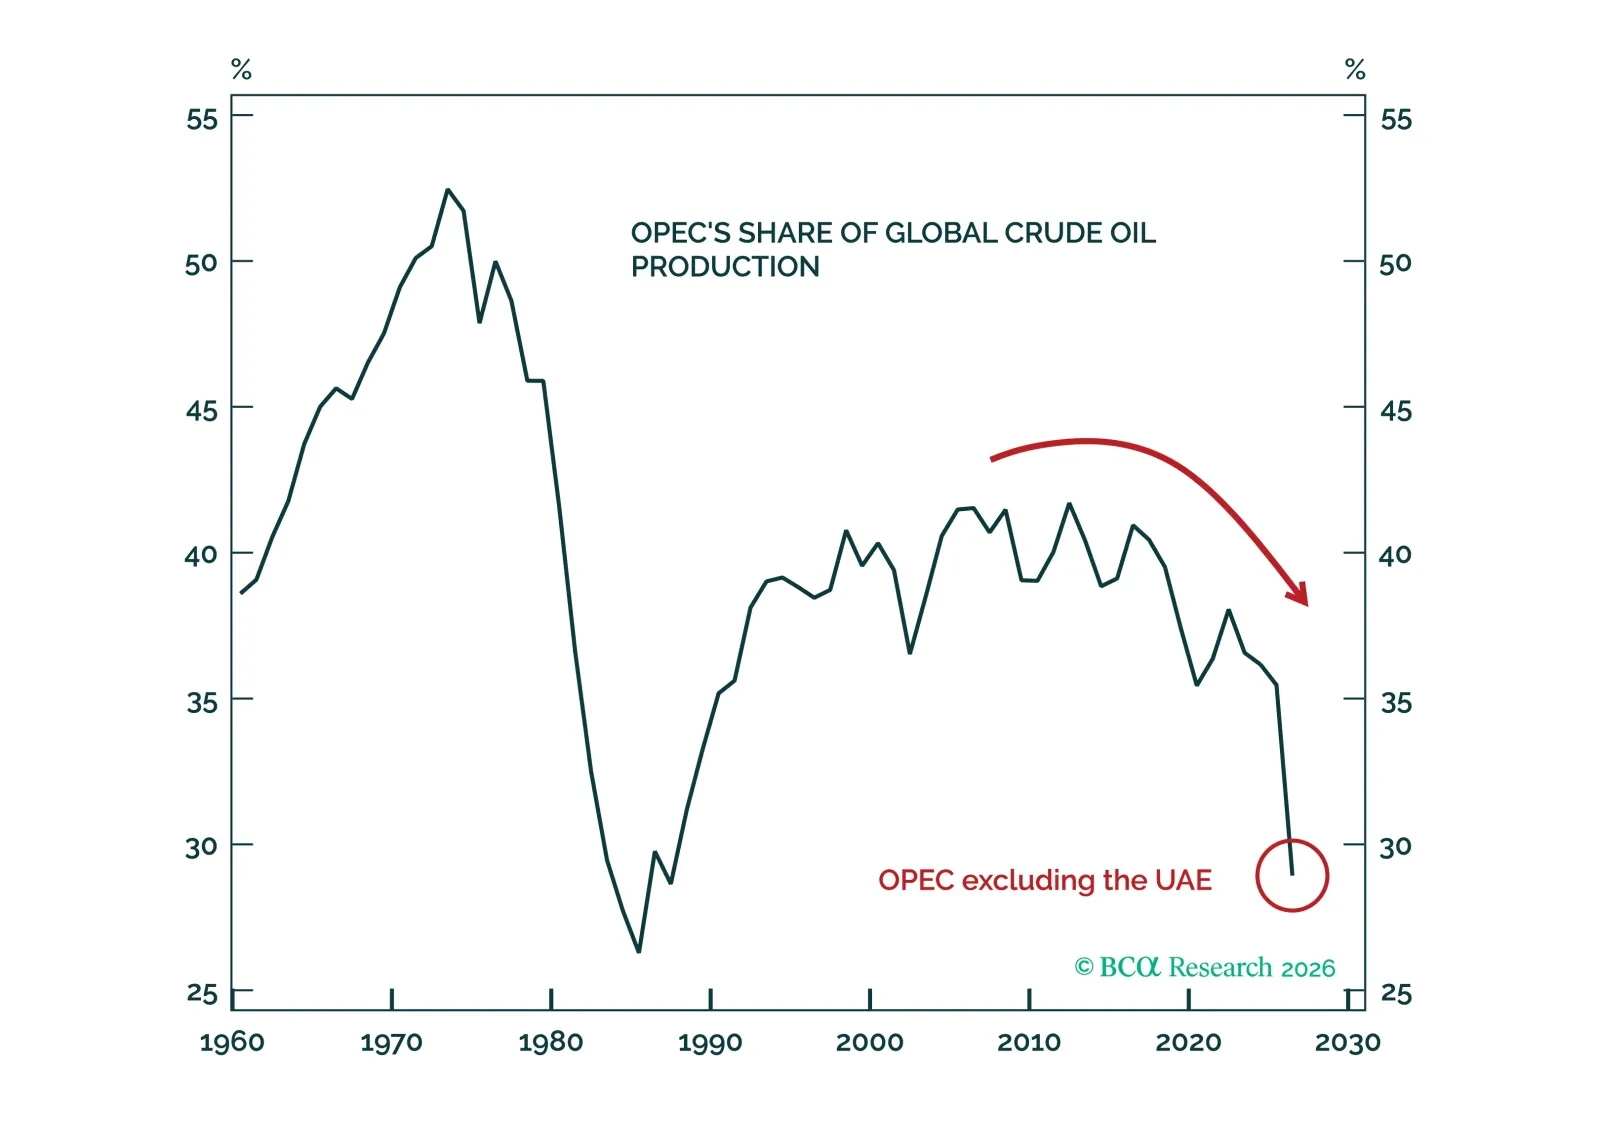
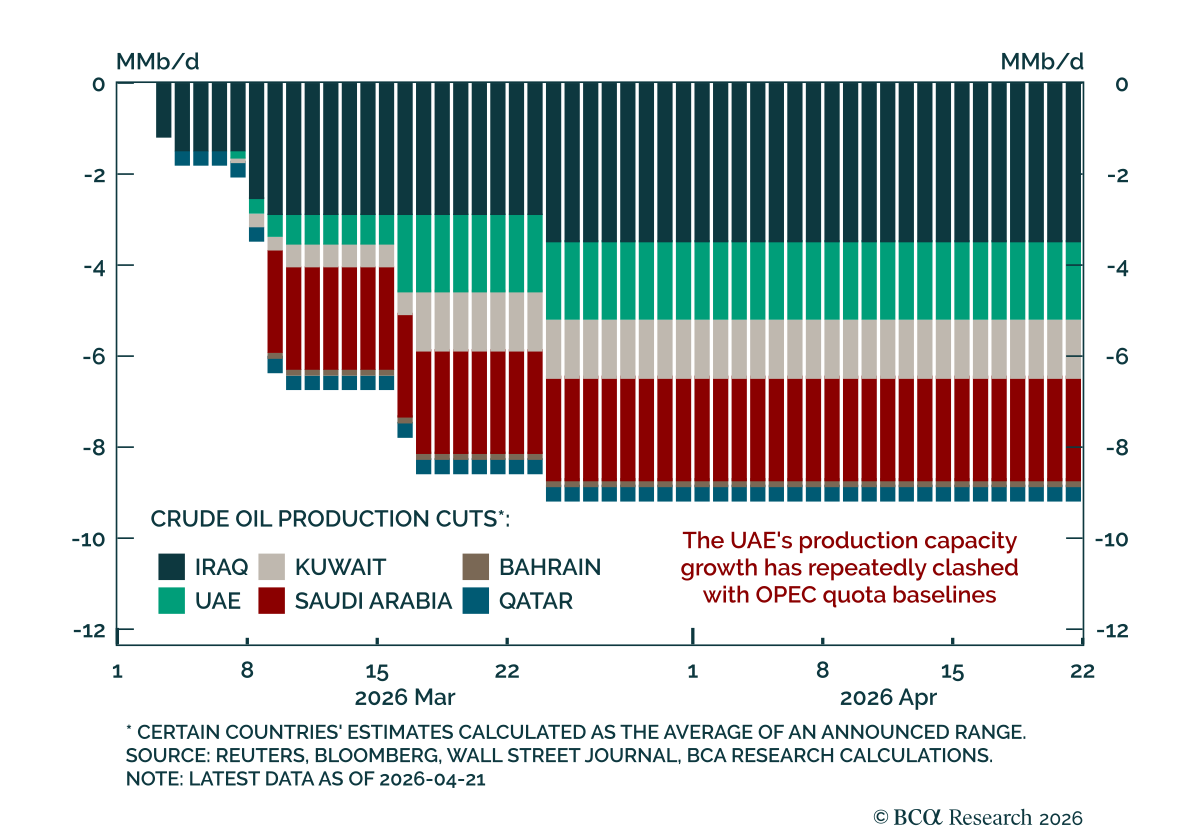
The UAE’s exit from OPEC is unlikely to impact oil markets in 2026. Over the longer term, however, the emergence of an “anti-OPEC club” of producers favoring unconstrained oil output growth would create a headwind to crude prices and weaken the price floor that OPEC seeks to defend.
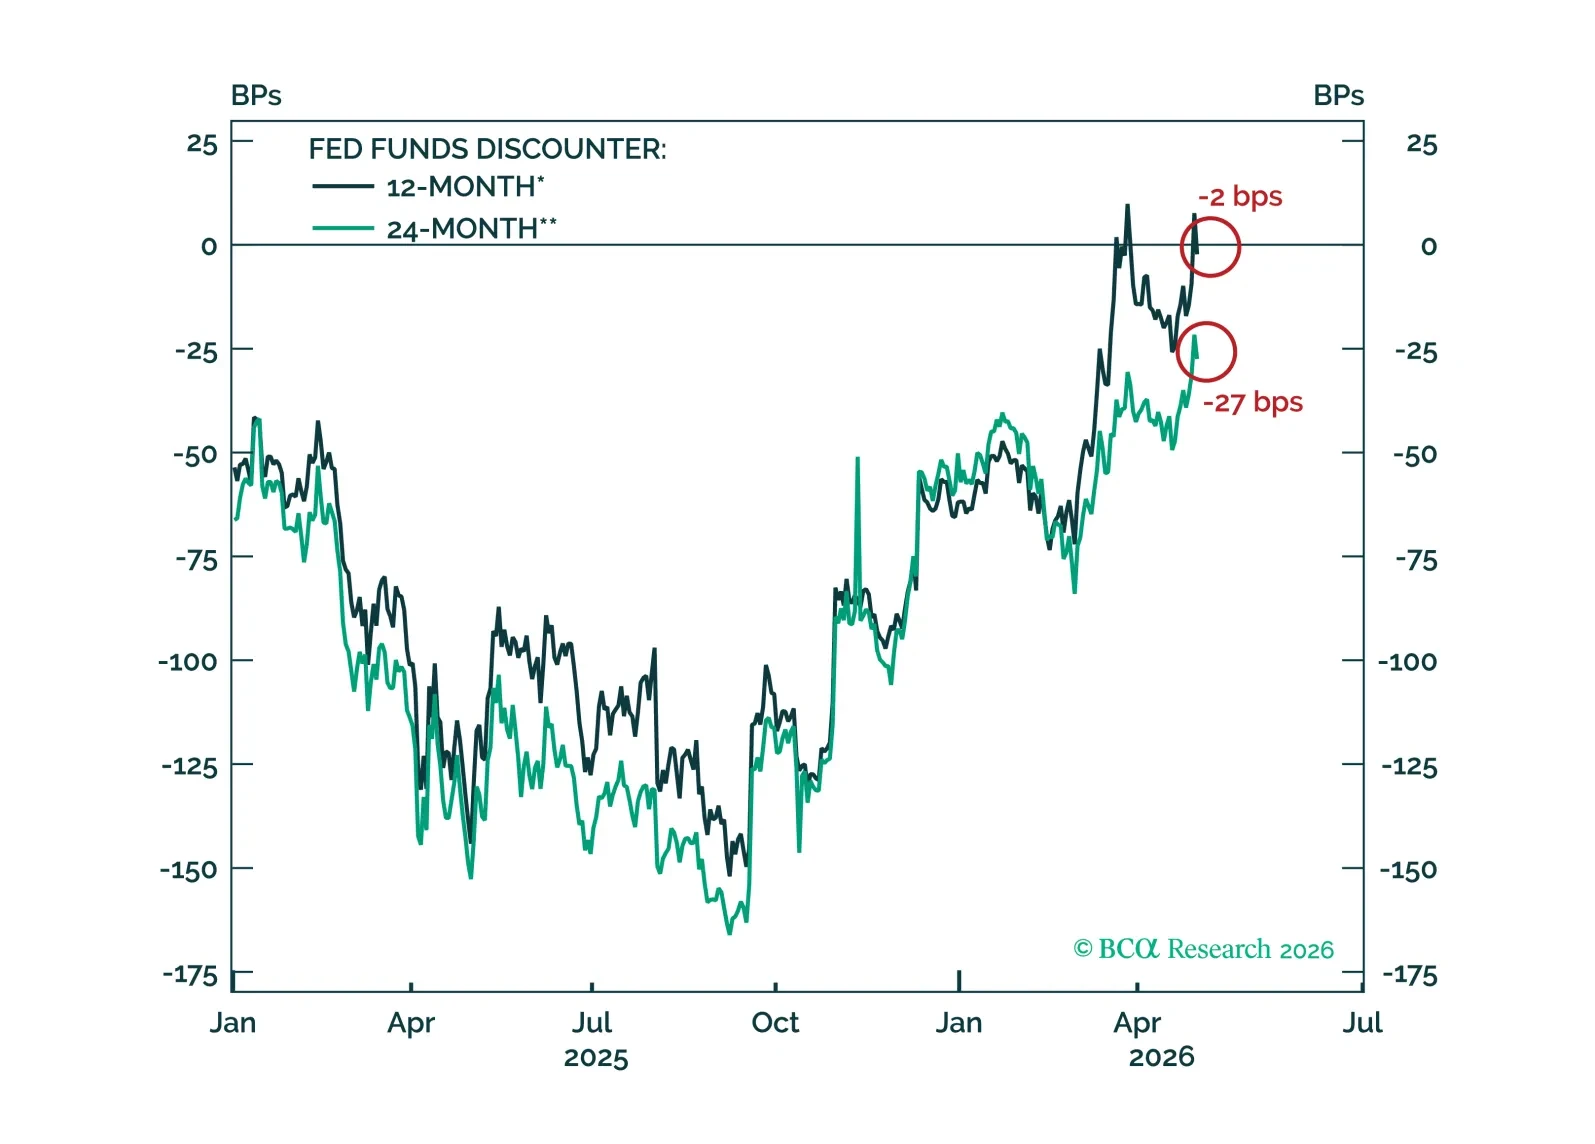
So far, there is no evidence of second-round effects from the oil price shock showing up in the US economy. Fed rate hikes are off the table unless those effects emerge.
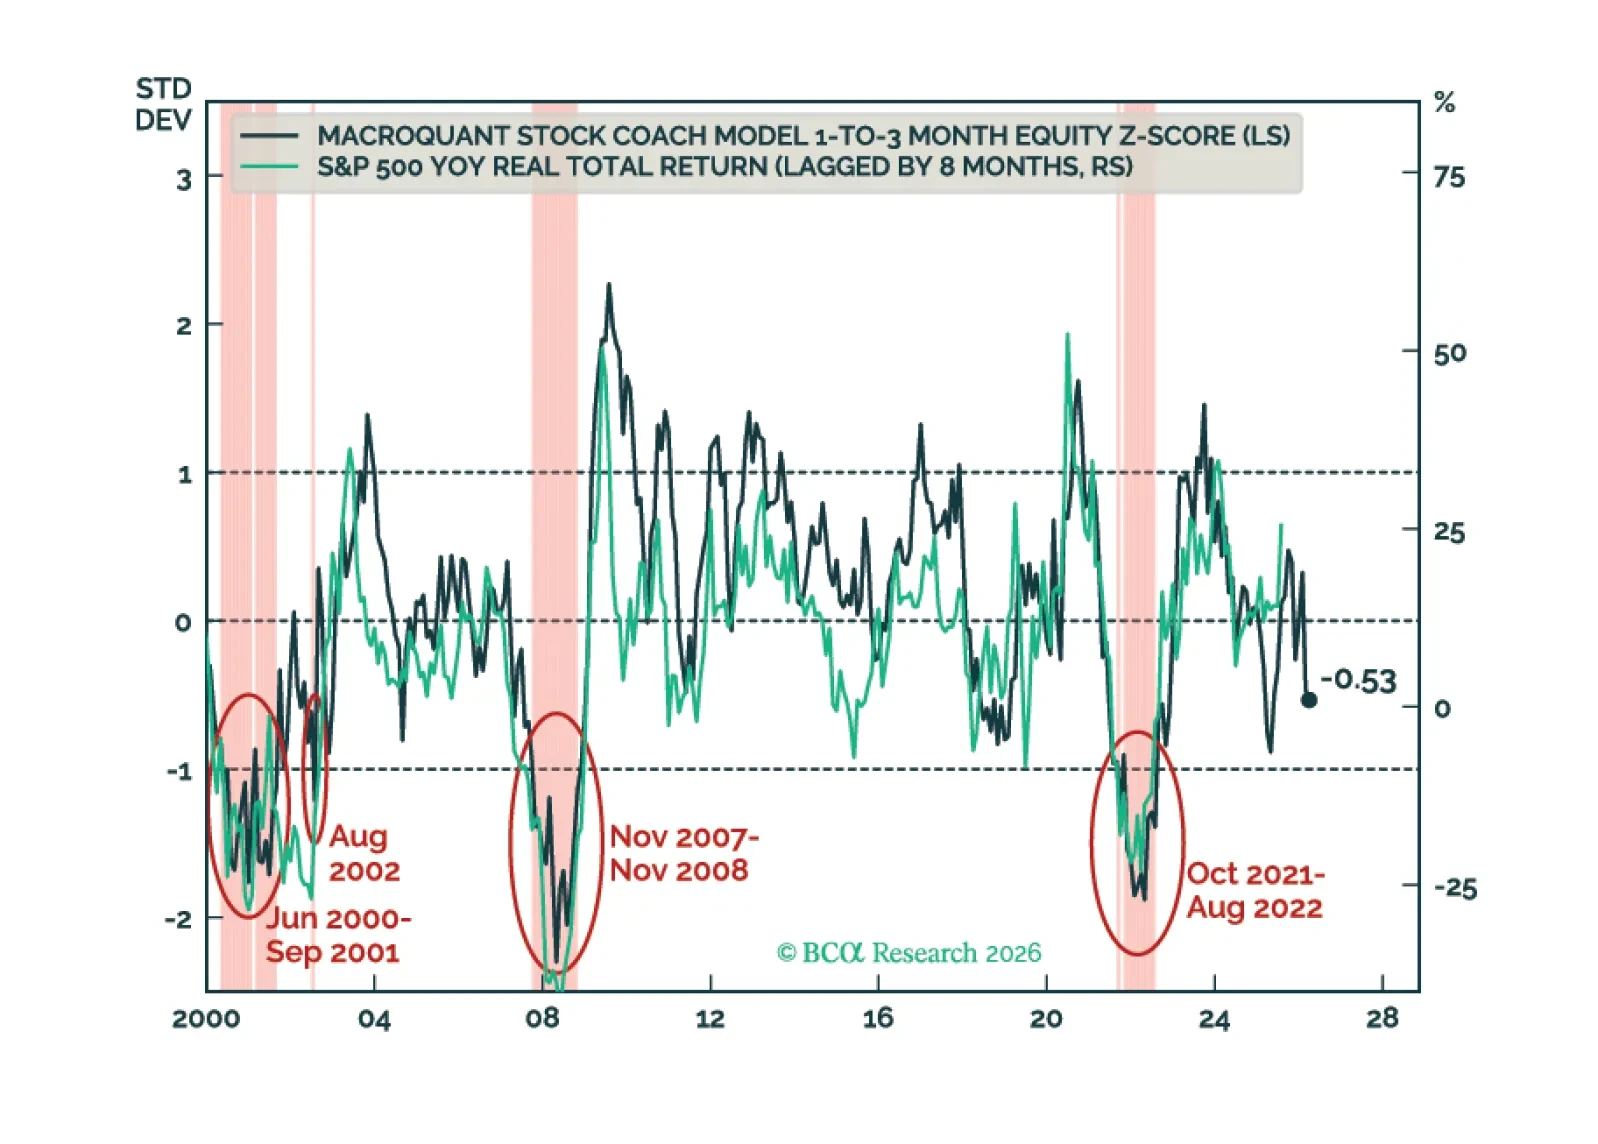
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.
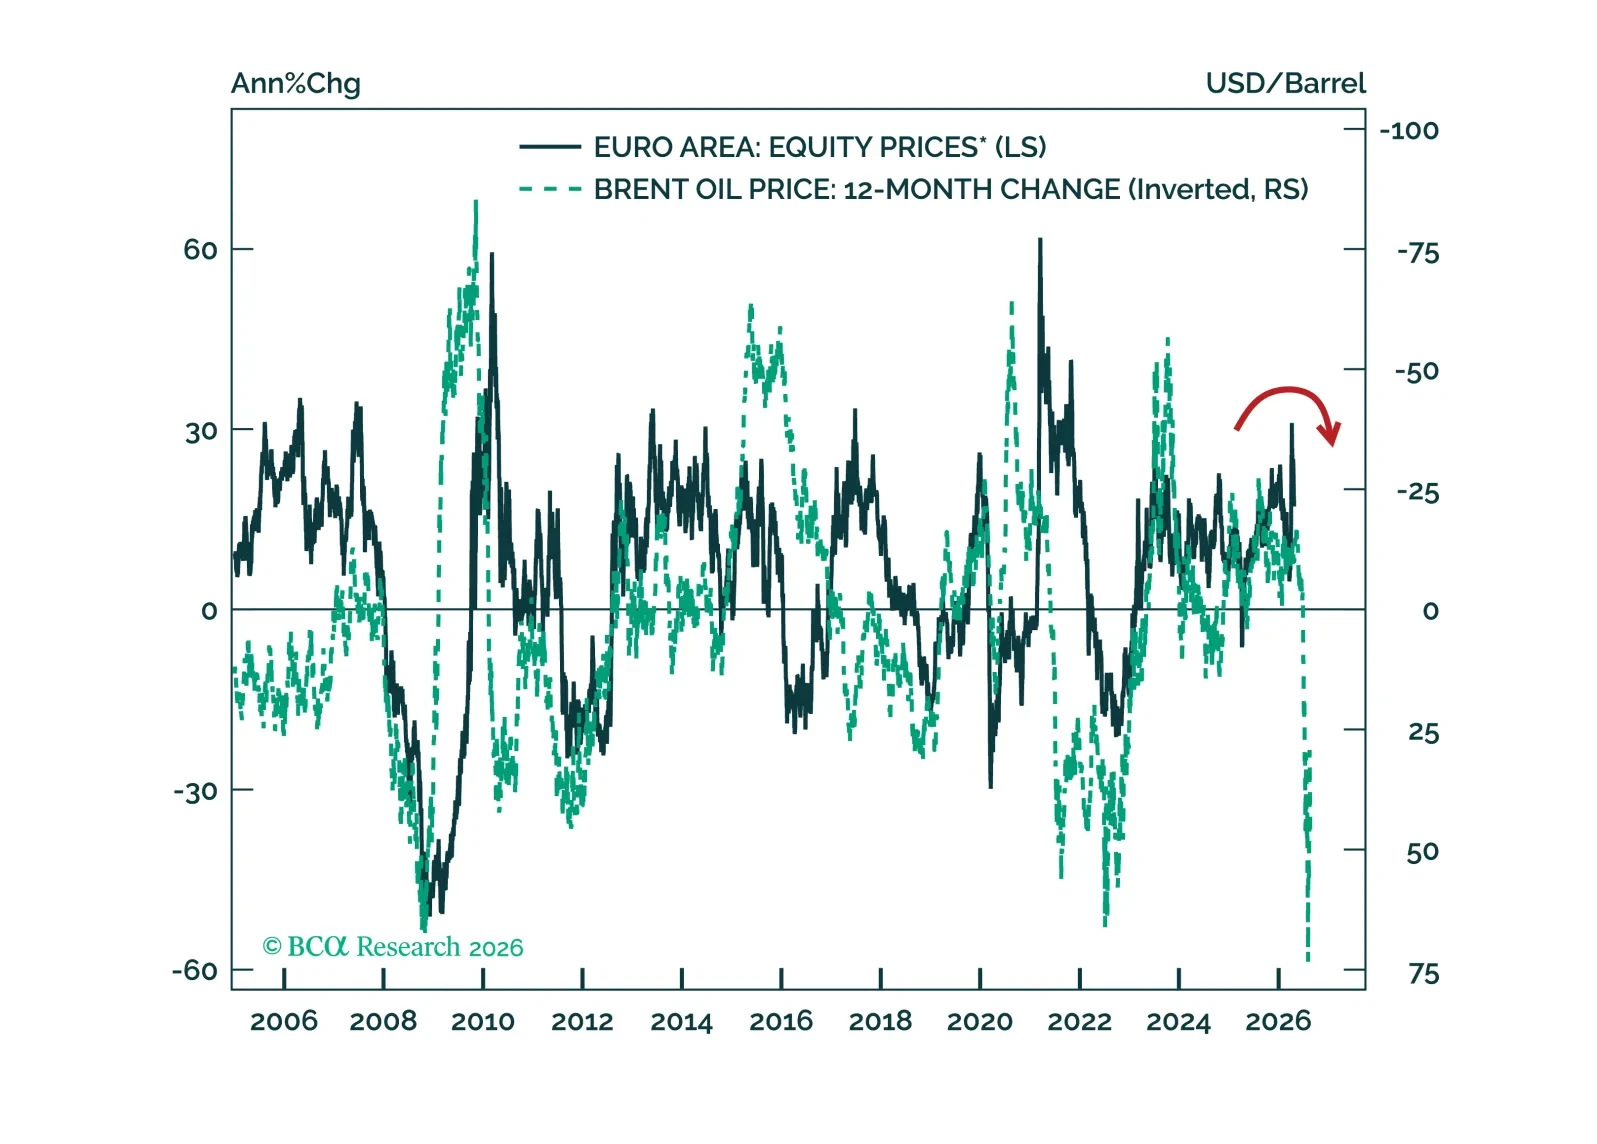
The longer the Strait of Hormuz remains closed, the more likely the Eurozone will experience an economic recession, as higher energy prices, supply chain disruptions, and weaker global demand slowly grind the European economy to a halt. The relief rally is running out of time. Investors should add exposure to the best-performing sectors following past oil supply shocks: Energy, pharma, and utilities.
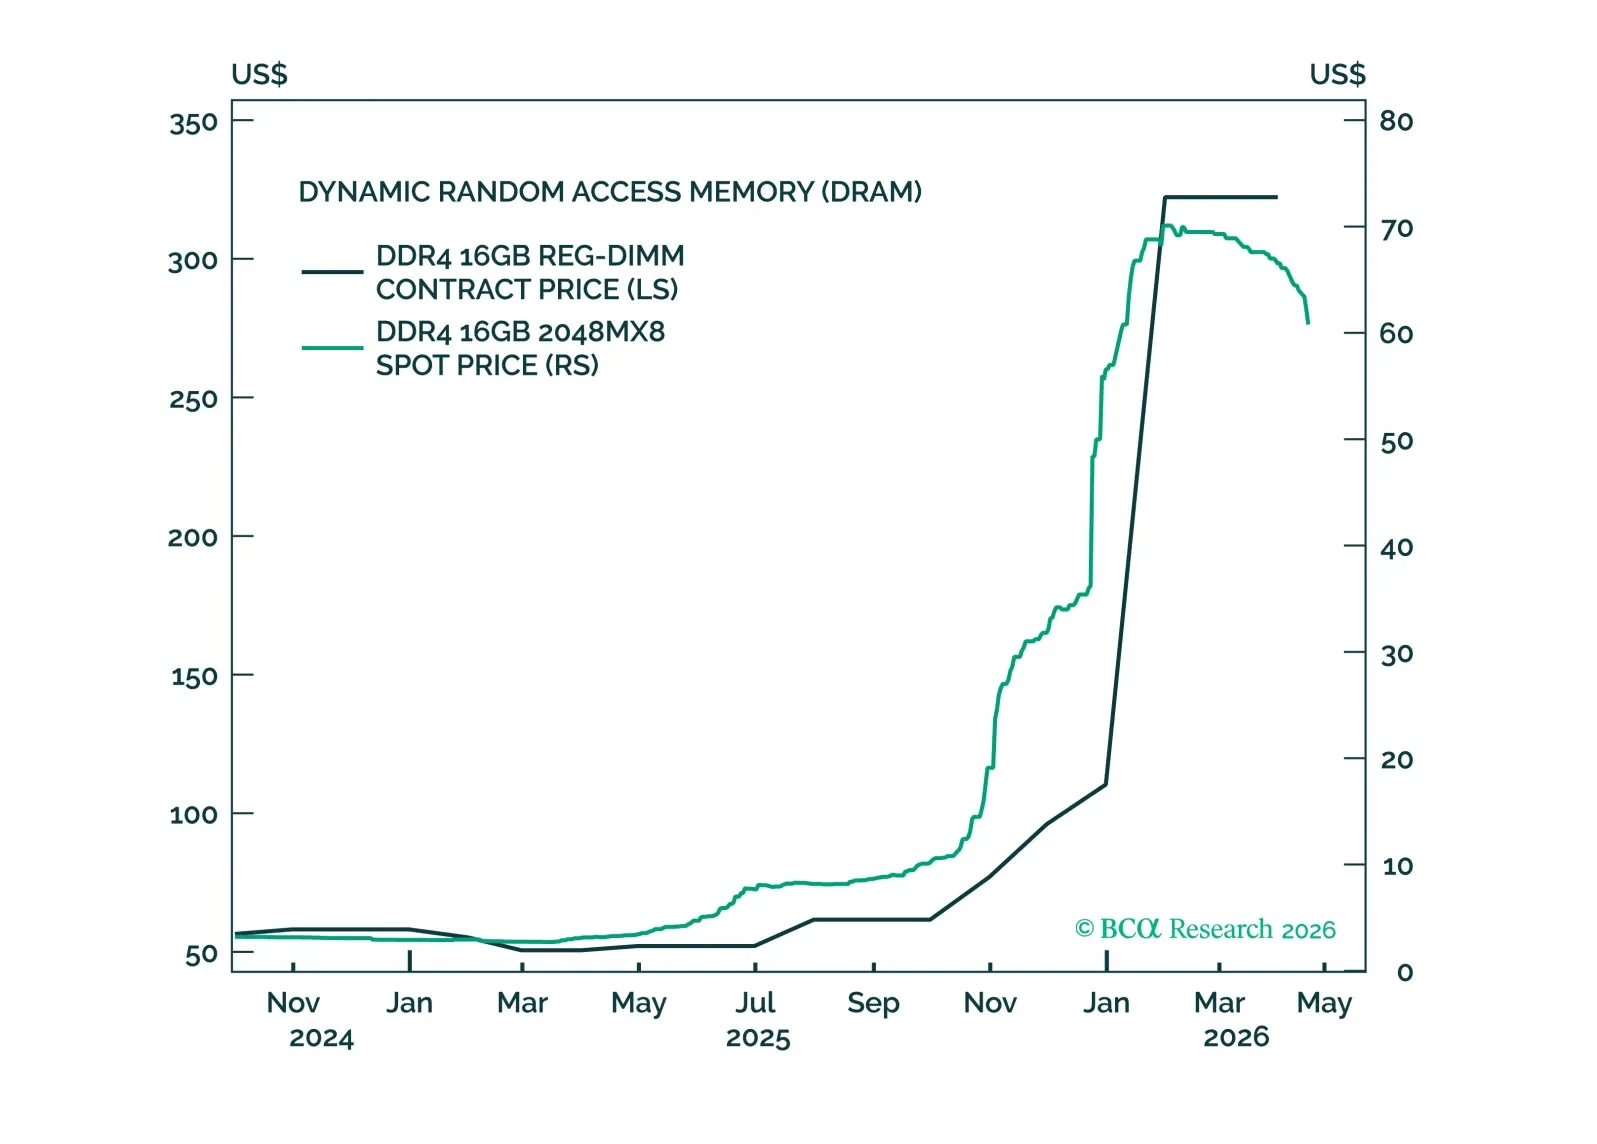
Most of the increase in S&P 500 earnings estimates this year has stemmed from shortages. The oil shortage, which has pushed up estimates for energy companies, will fade once the military conflict is resolved. However, the shortage of semiconductors and other AI paraphernalia could persist for a while longer. As such, we are moving our recommended 12-month equity allocation from a slight underweight to neutral. We are already neutral on a 3-month horizon.
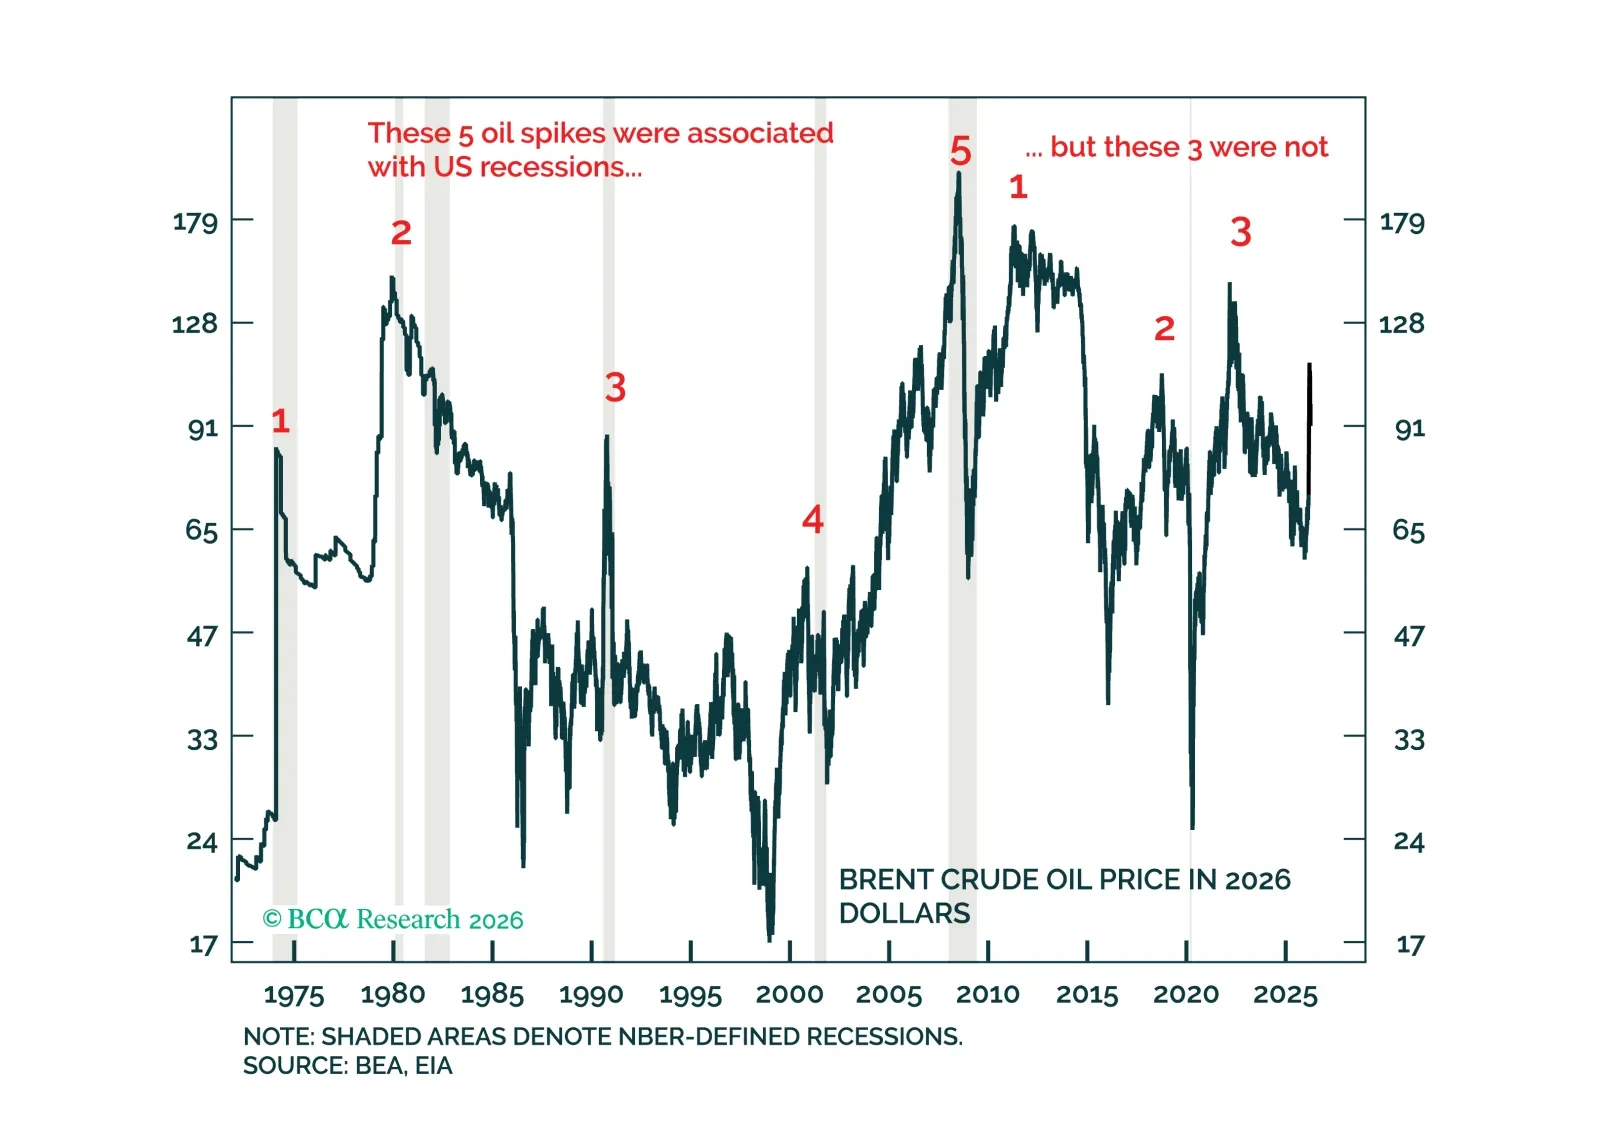
In the US, the oil shock’s impact is more inflationary than recessionary but in the other economies, like the UK, the impact is both inflationary and recessionary. This creates relative value opportunities for bond investors. Plus, we reiterate short AUD/JPY as a trade.