AI
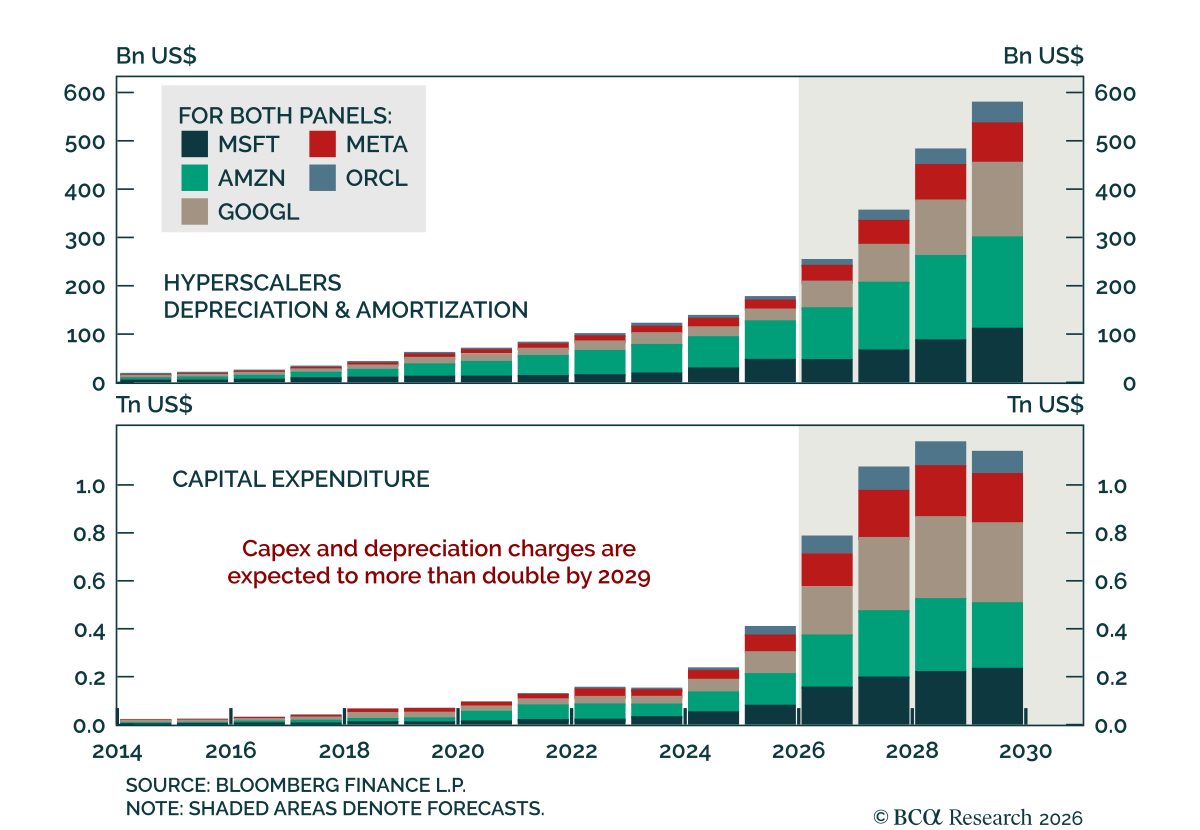
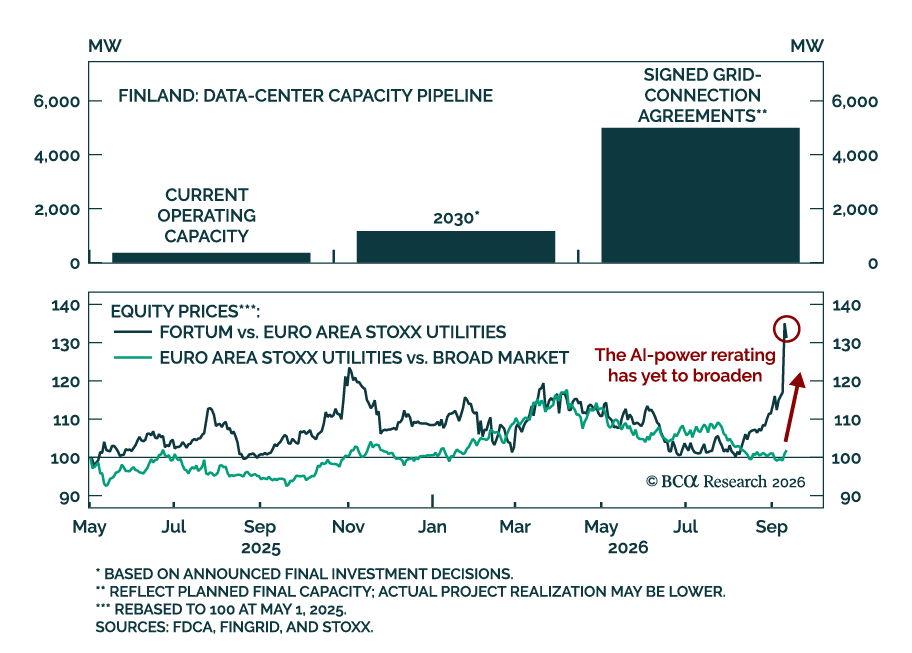
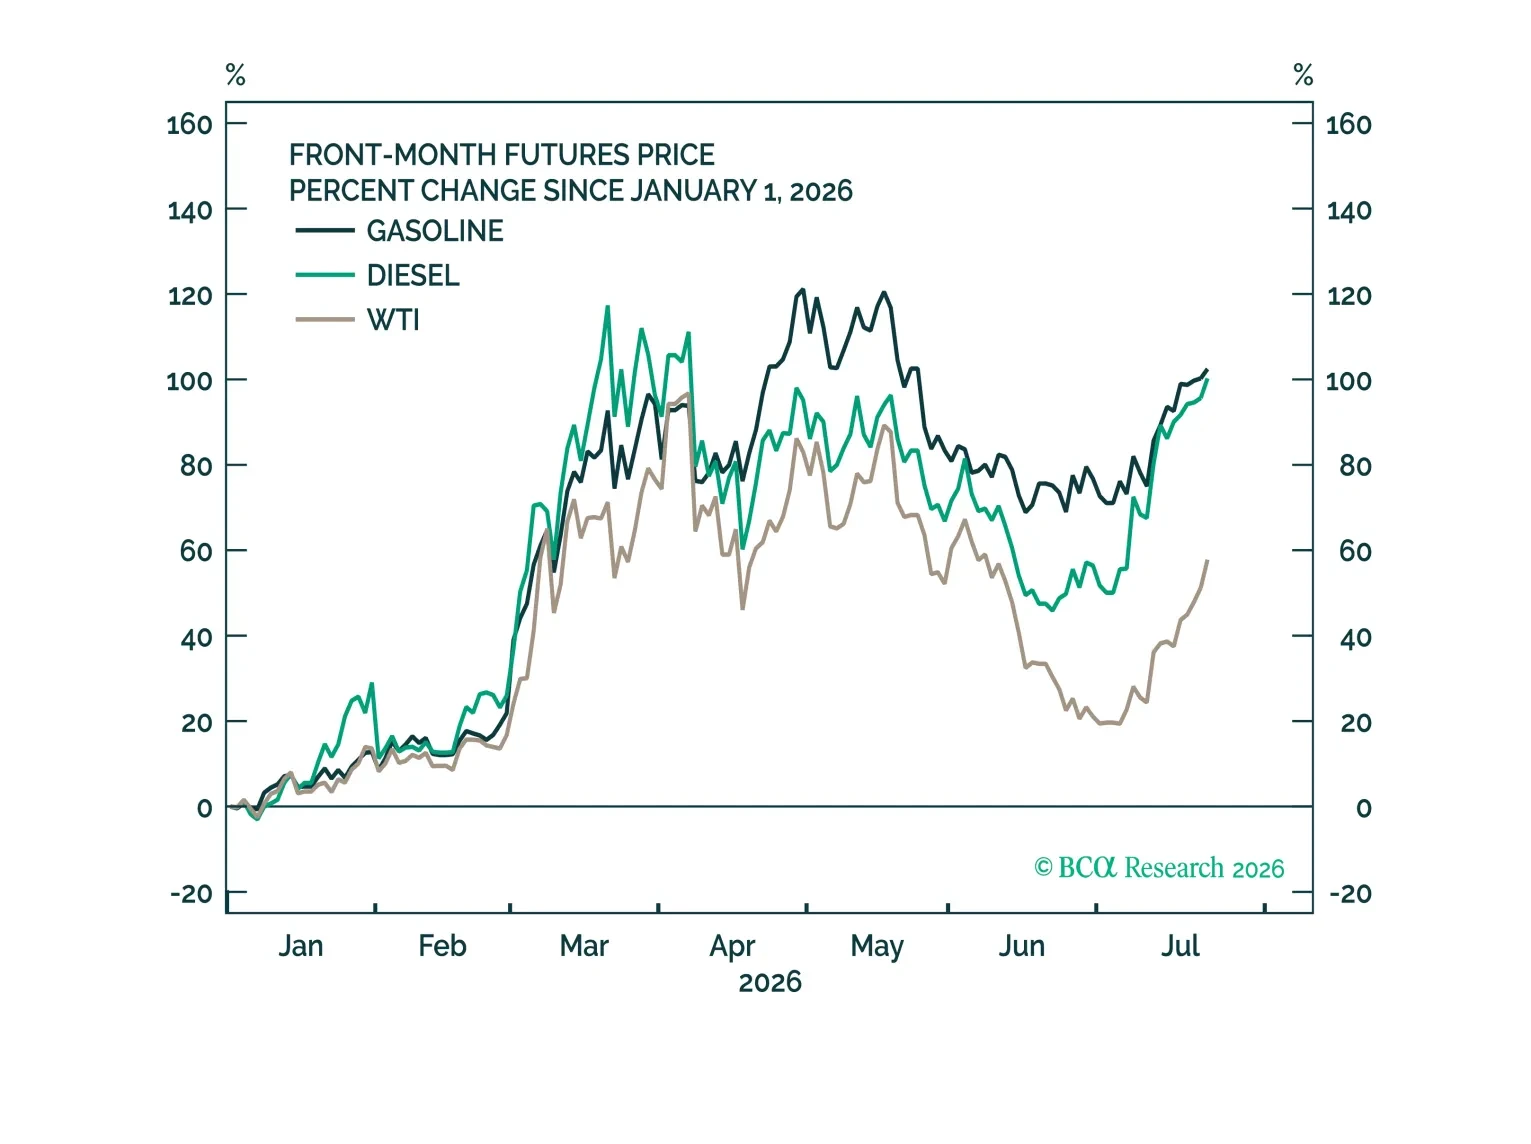
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
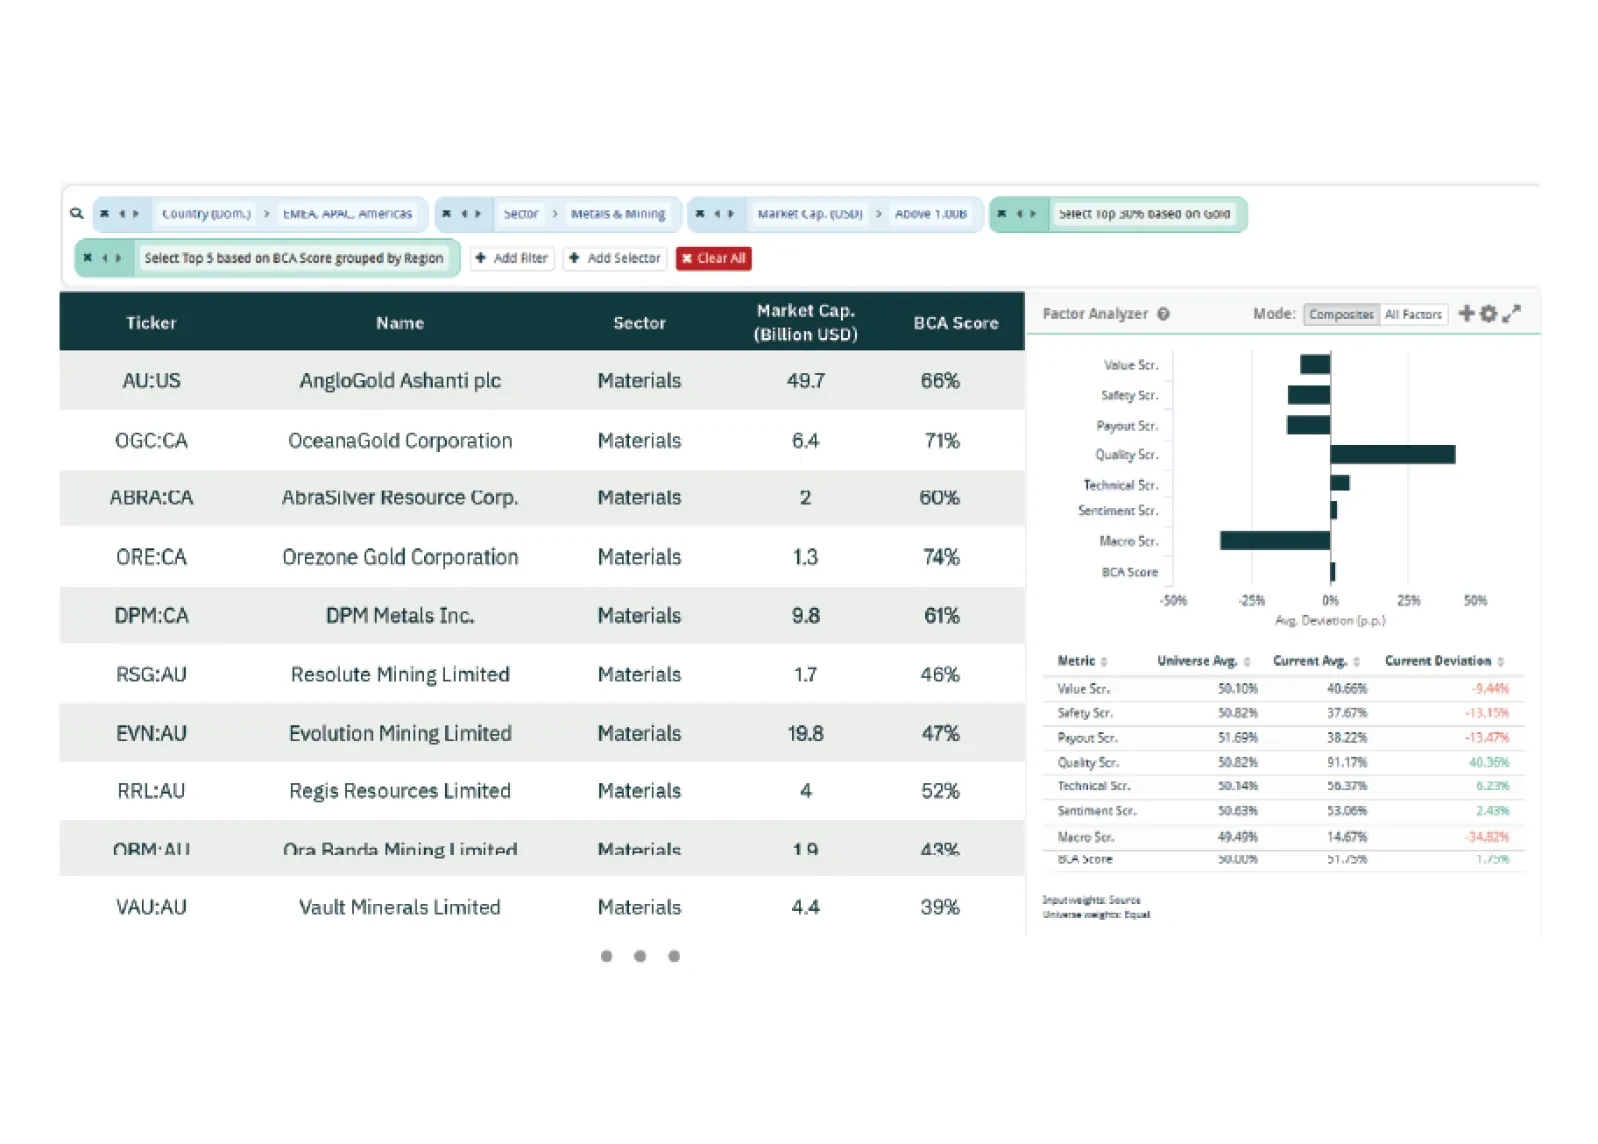
In this report, we explore opportunities in goldminer equities, AI infrastructure monetization, and Japan's tactical outperformance window.
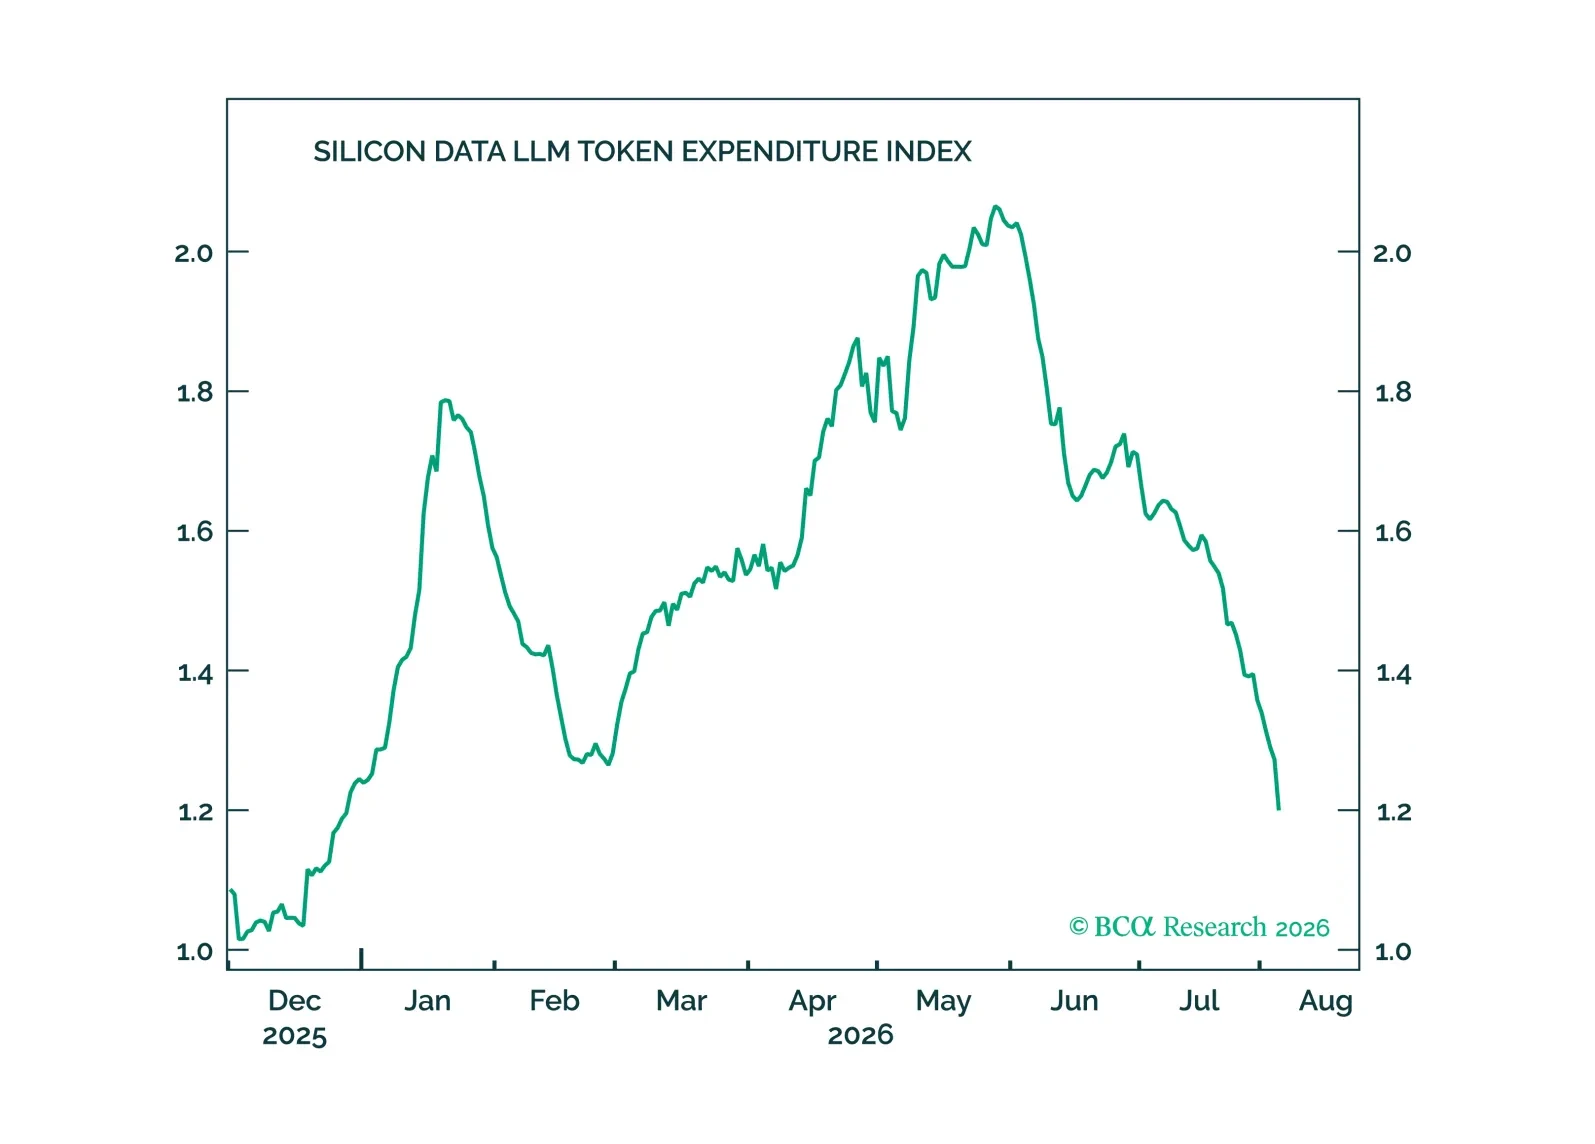
We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.
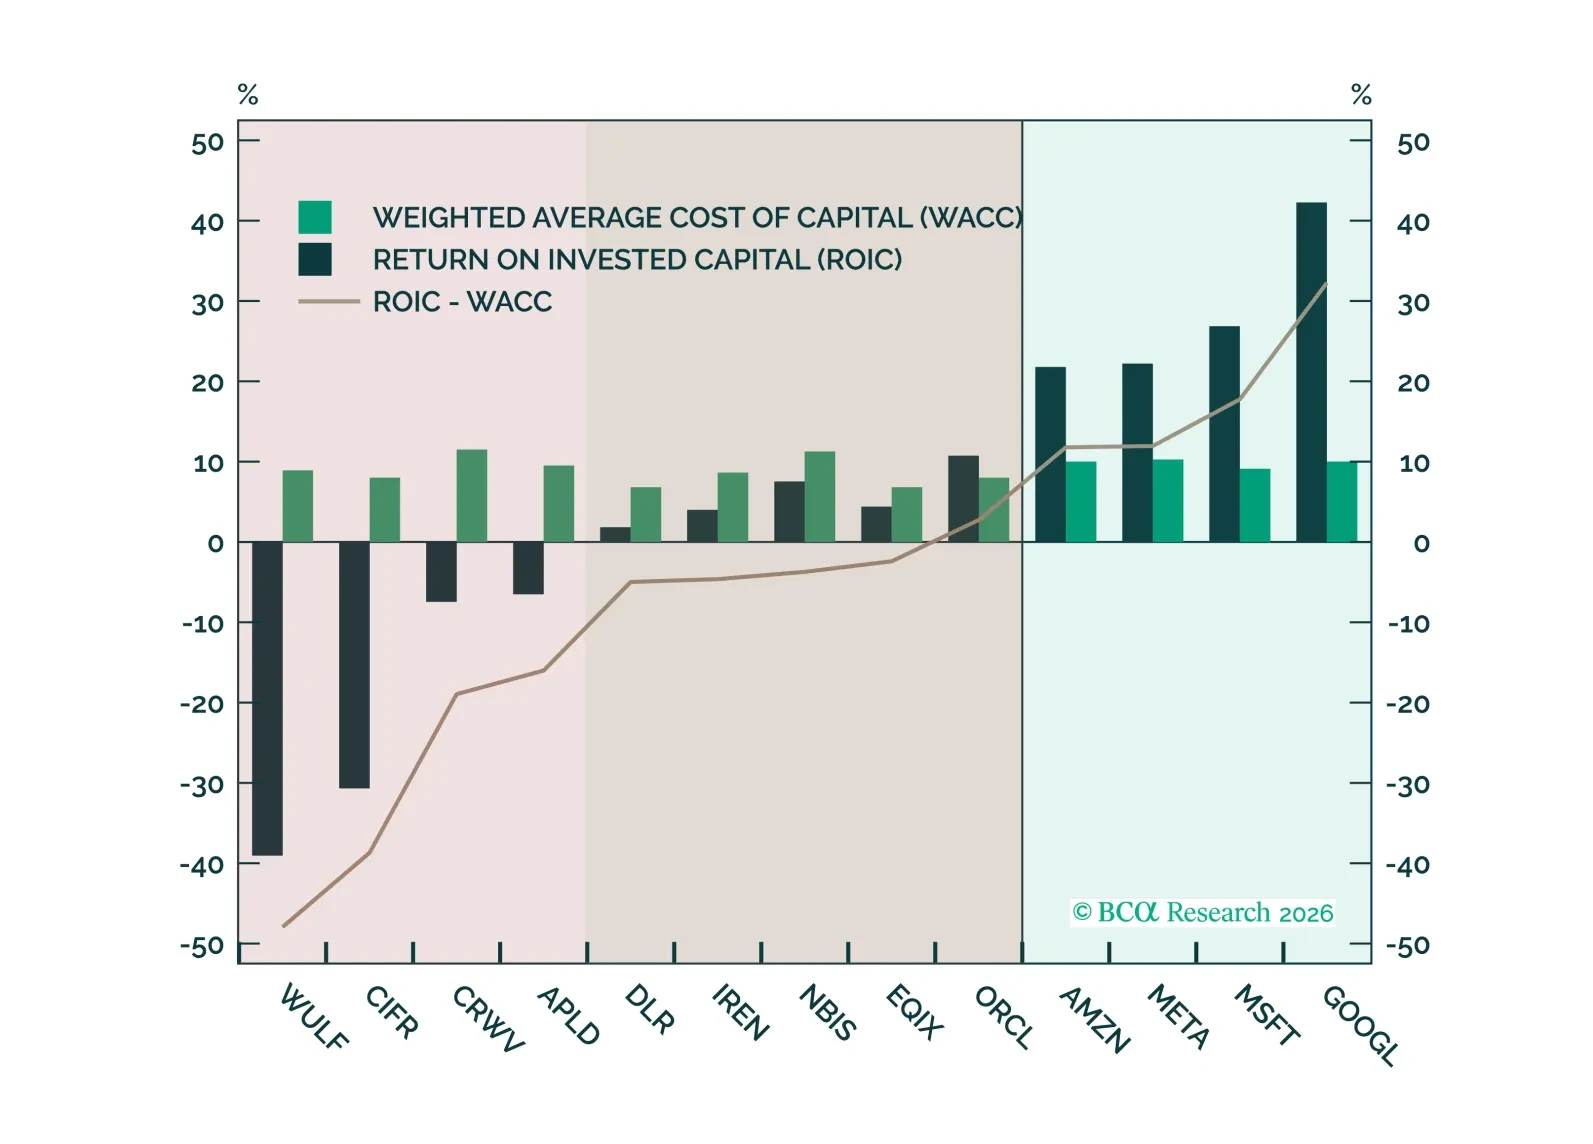
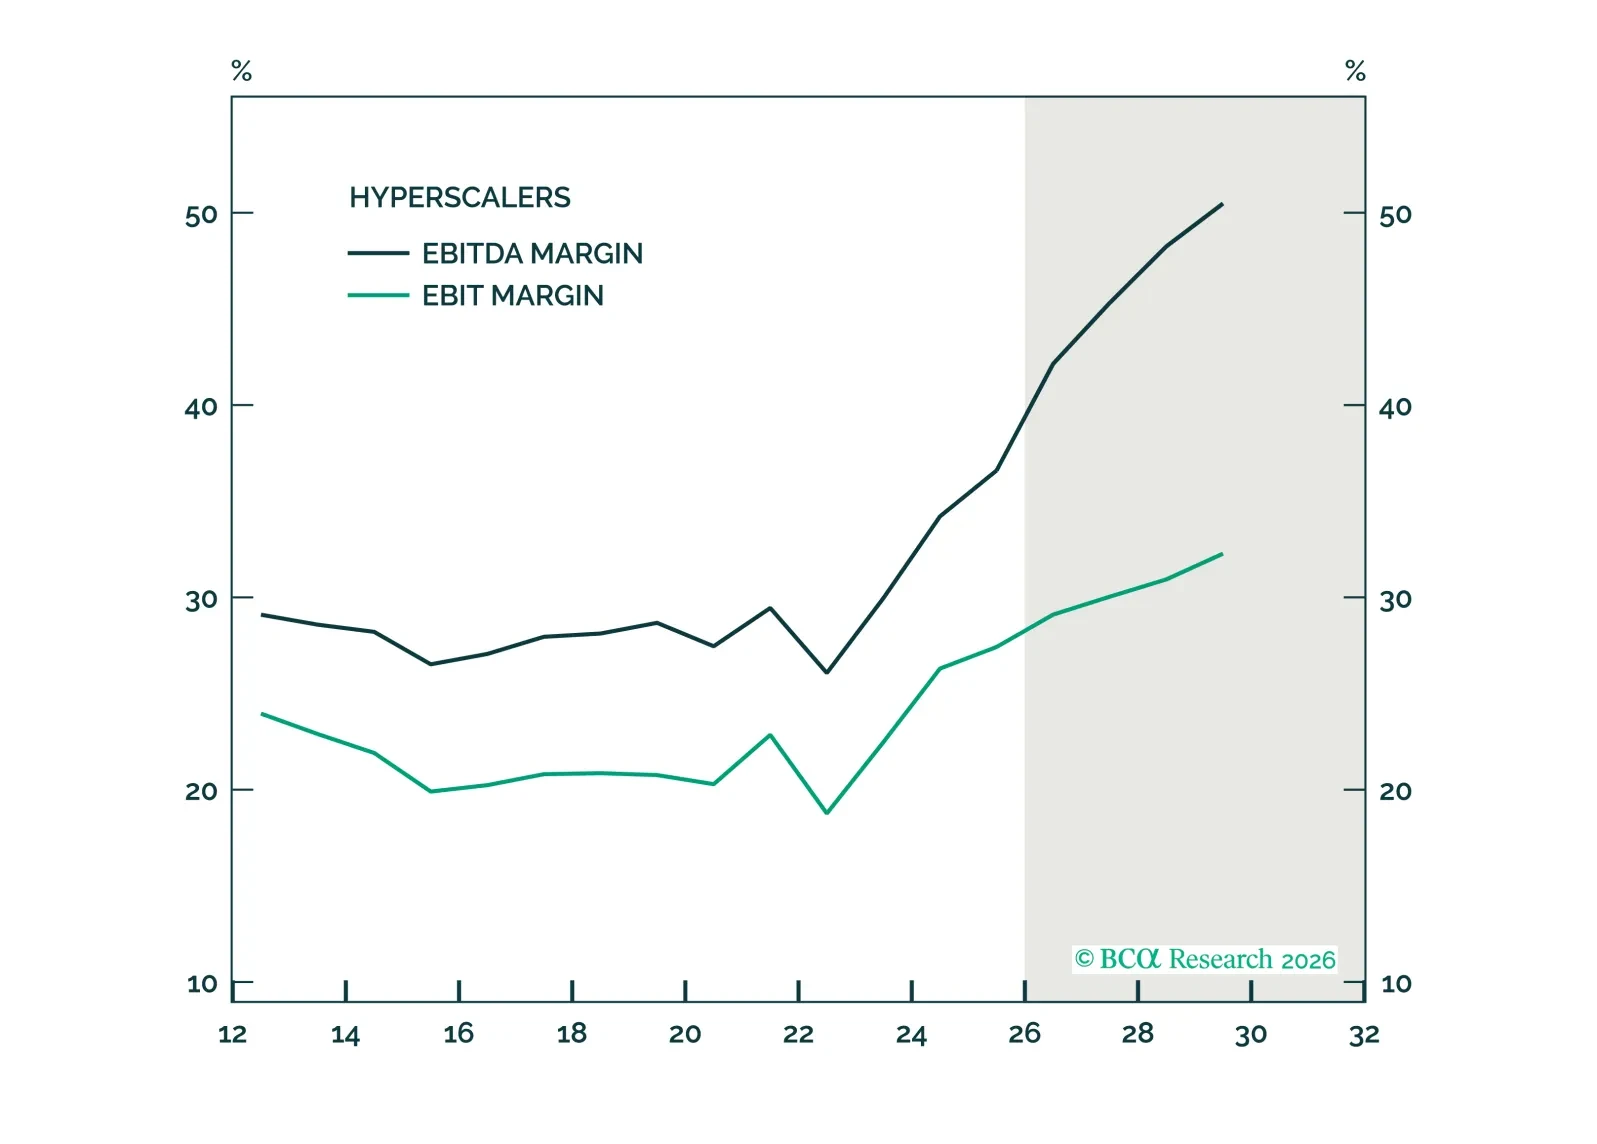
AI demand remains strong, but the capex boom is creating a growing divide within Tech. Hyperscalers combine superior margins, capital efficiency and financing capacity with multiple paths to monetize AI investment. Neoclouds rely more heavily on leverage and scarcity economics, potentially making them more vulnerable should capacity expand and compute pricing normalize.
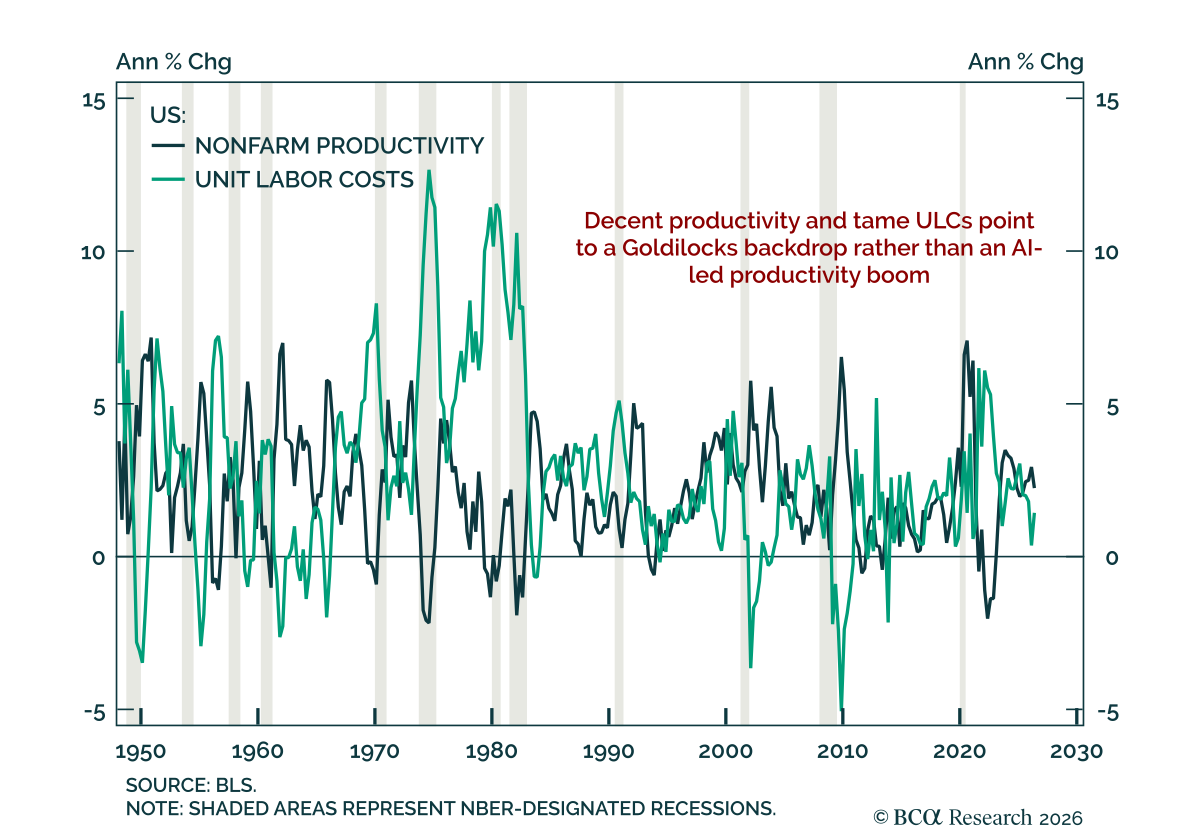
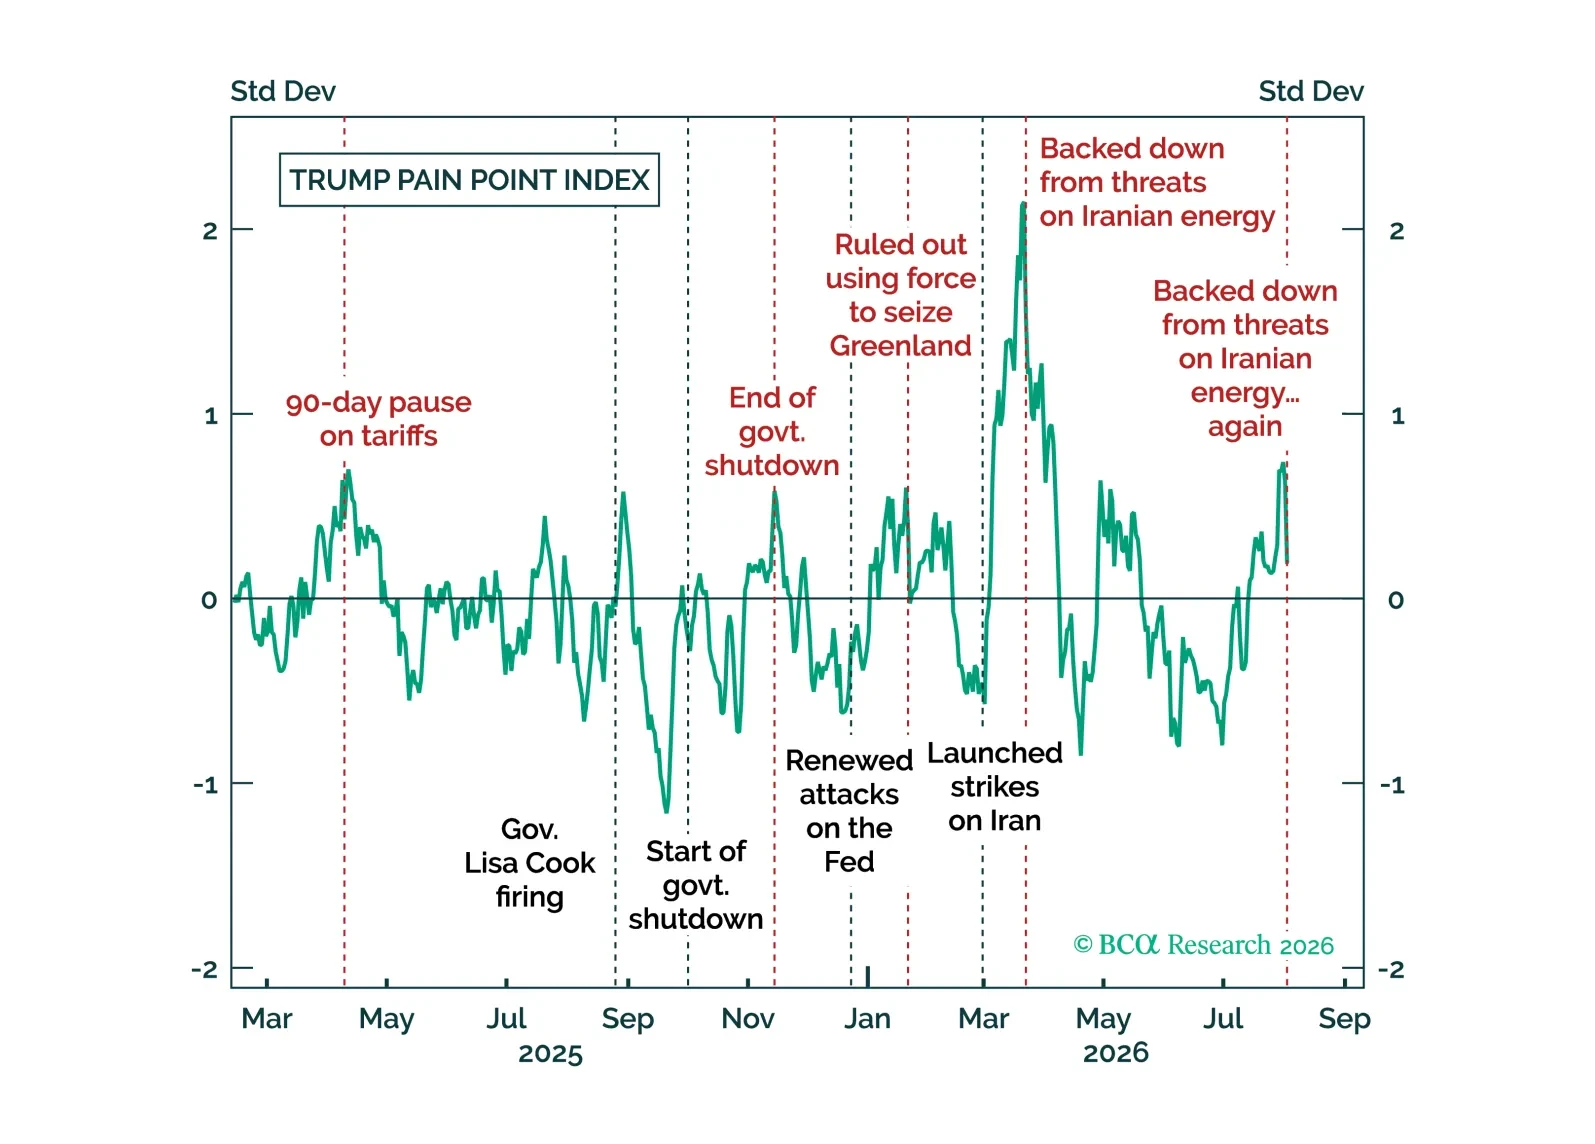
Last month we "stuck our neck out" and reaffirmed our bullishness towards risk asset. This month, we have confirmation that the risky bet is paying off. Iran and the US remain materially constrained from total war. The AI capex thesis is holding up and slowly mutating into a price war that will only boost adoption and necessitate more investment. We open a new AI-related trade (long hard disk makers) and go long gold.
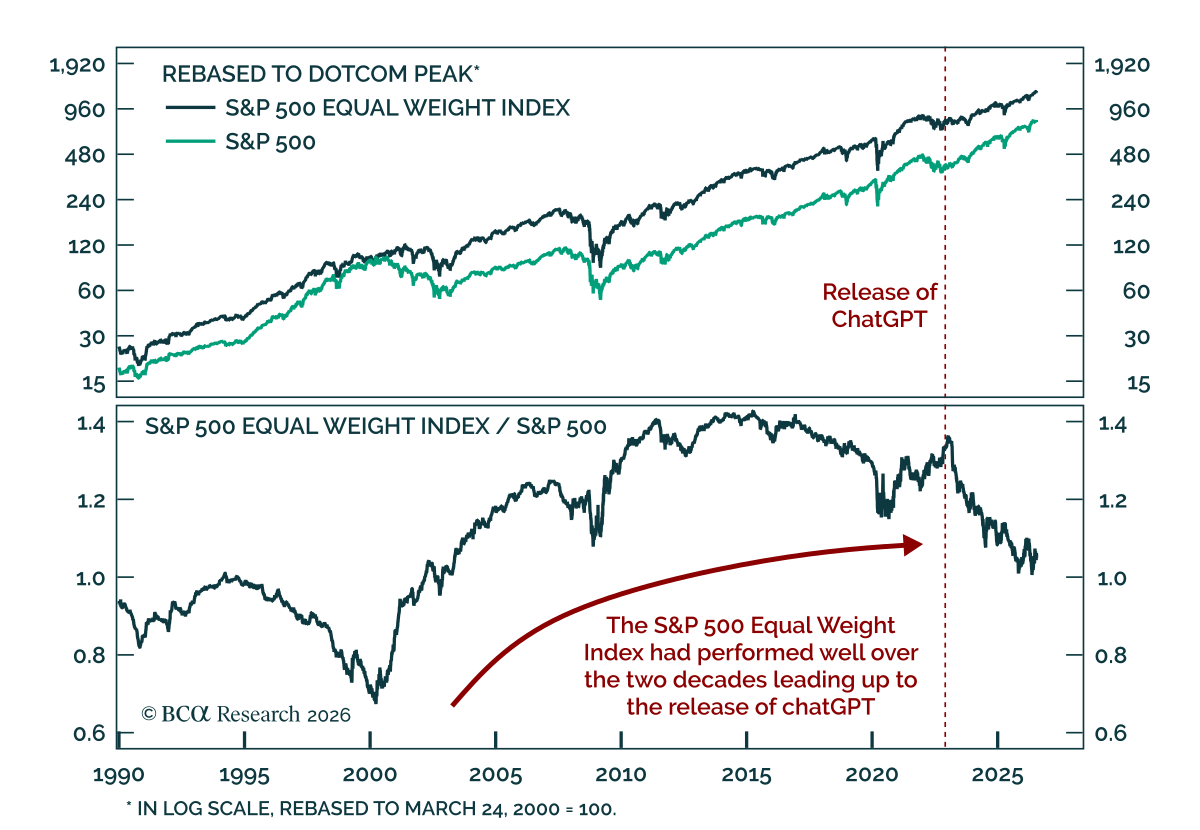
As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.