Global
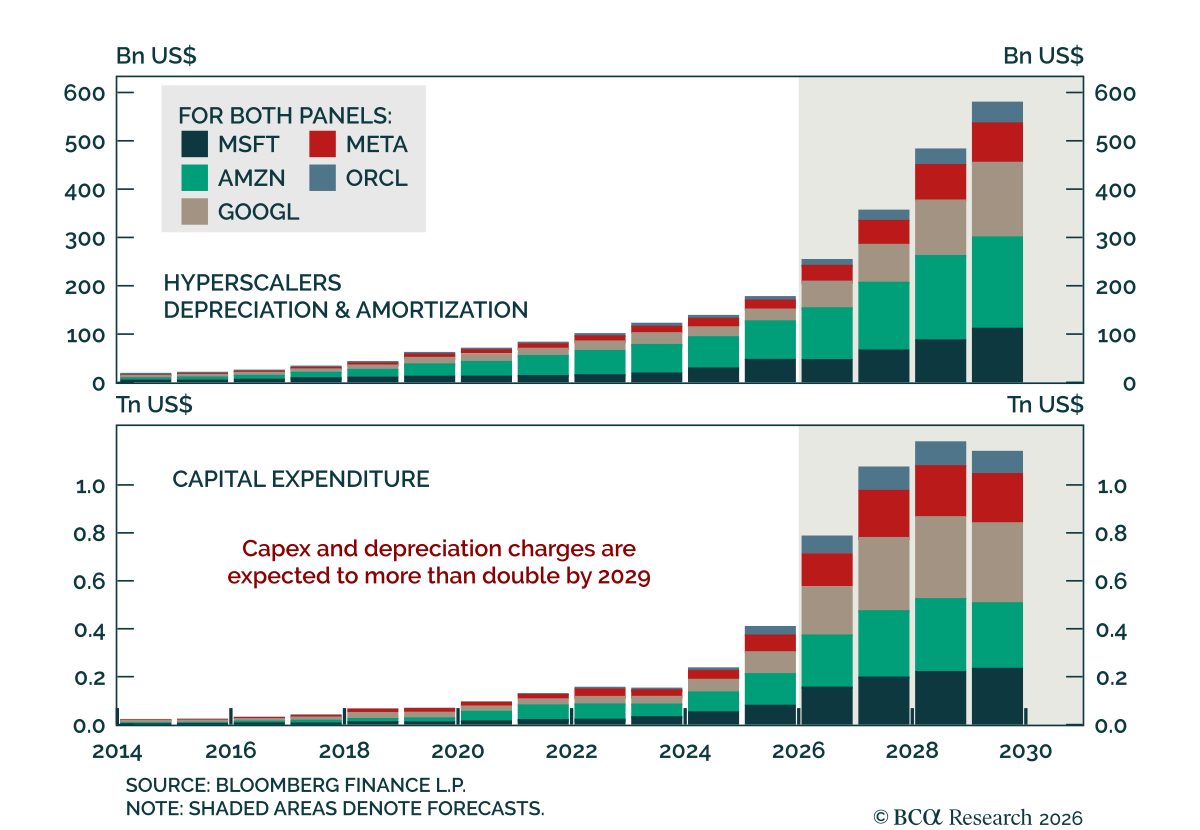
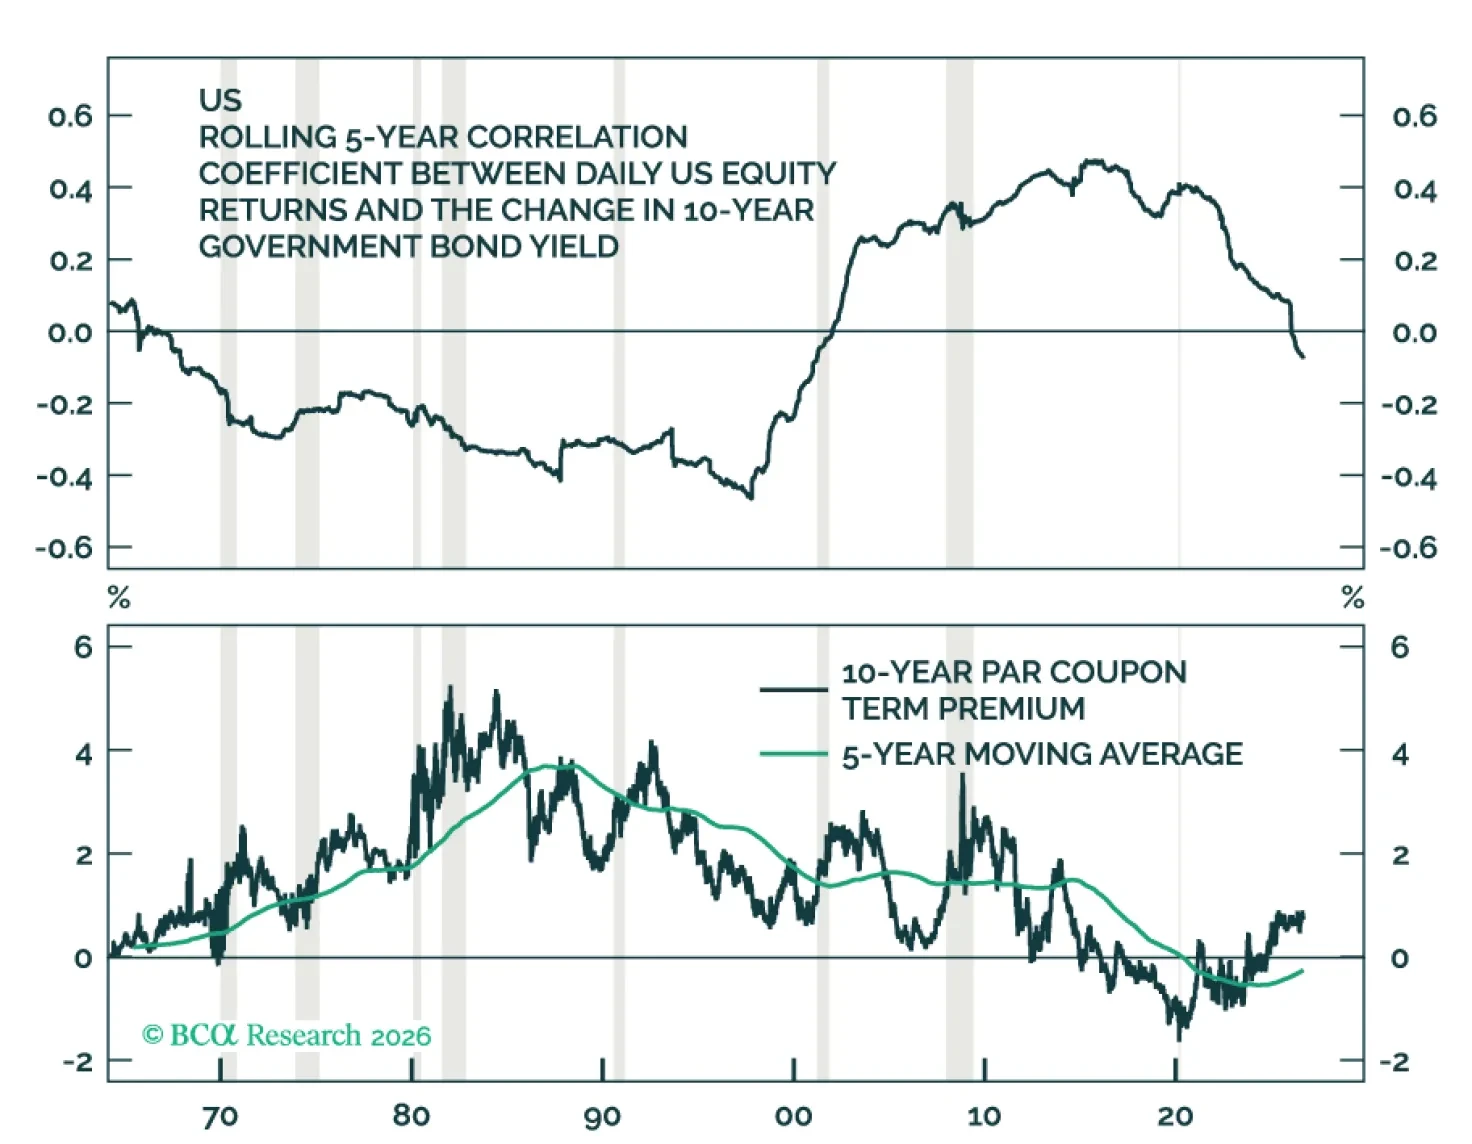
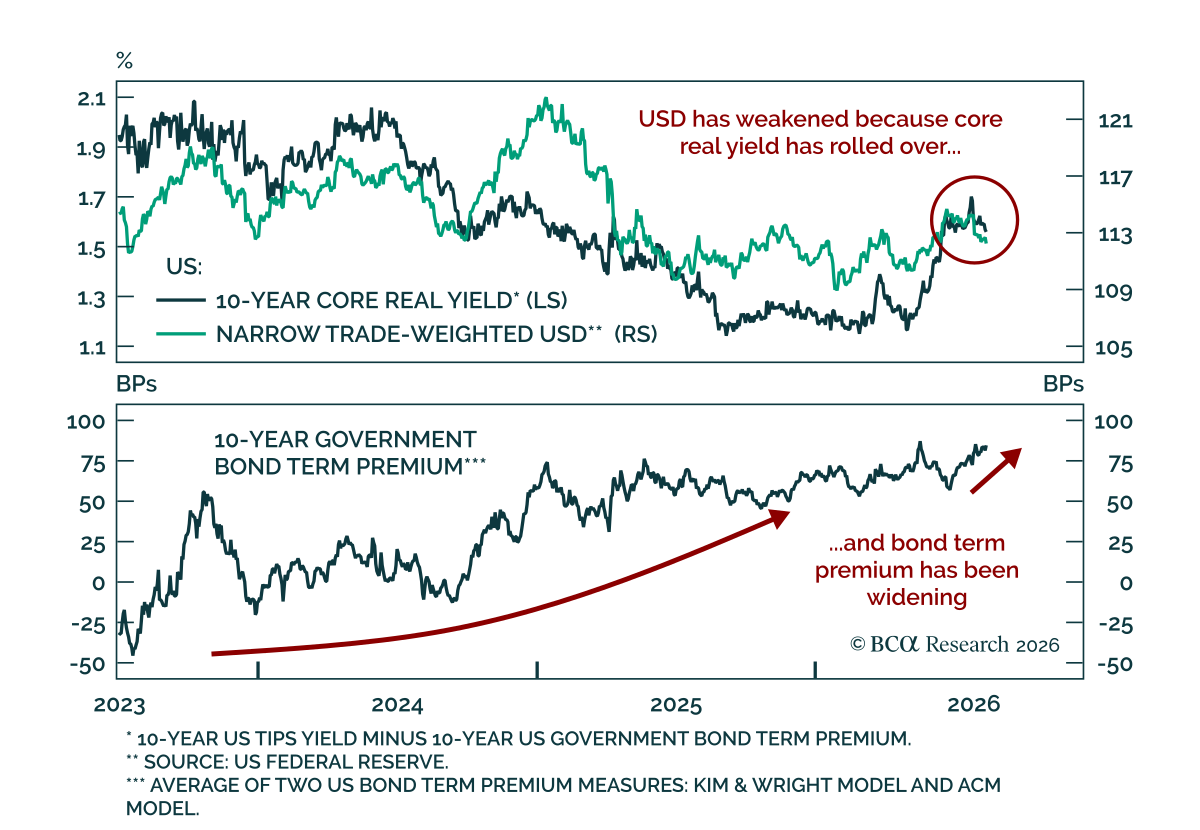
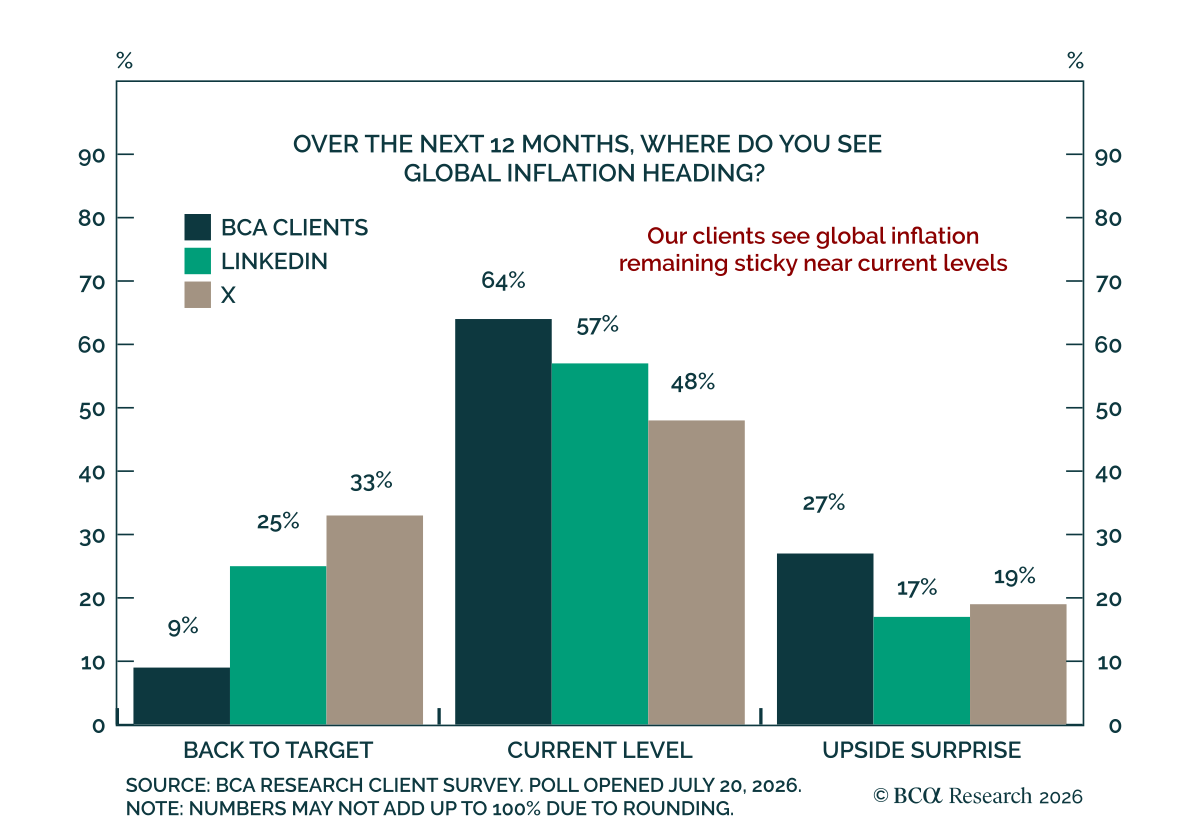
We propose a unified framework for predicting the direction of short-term interest rates and long-term bond yields that brings together three approaches: 1) the saving-investment approach; 2) the Taylor rule approach; and 3) the portfolio balance approach. Our analysis suggests that bond yields in the US and many other countries have increased mainly because of a higher neutral interest rate and a larger term premium. Given the risk of a further rise in inflation expectations, investors should overweight inflation-linked bonds.
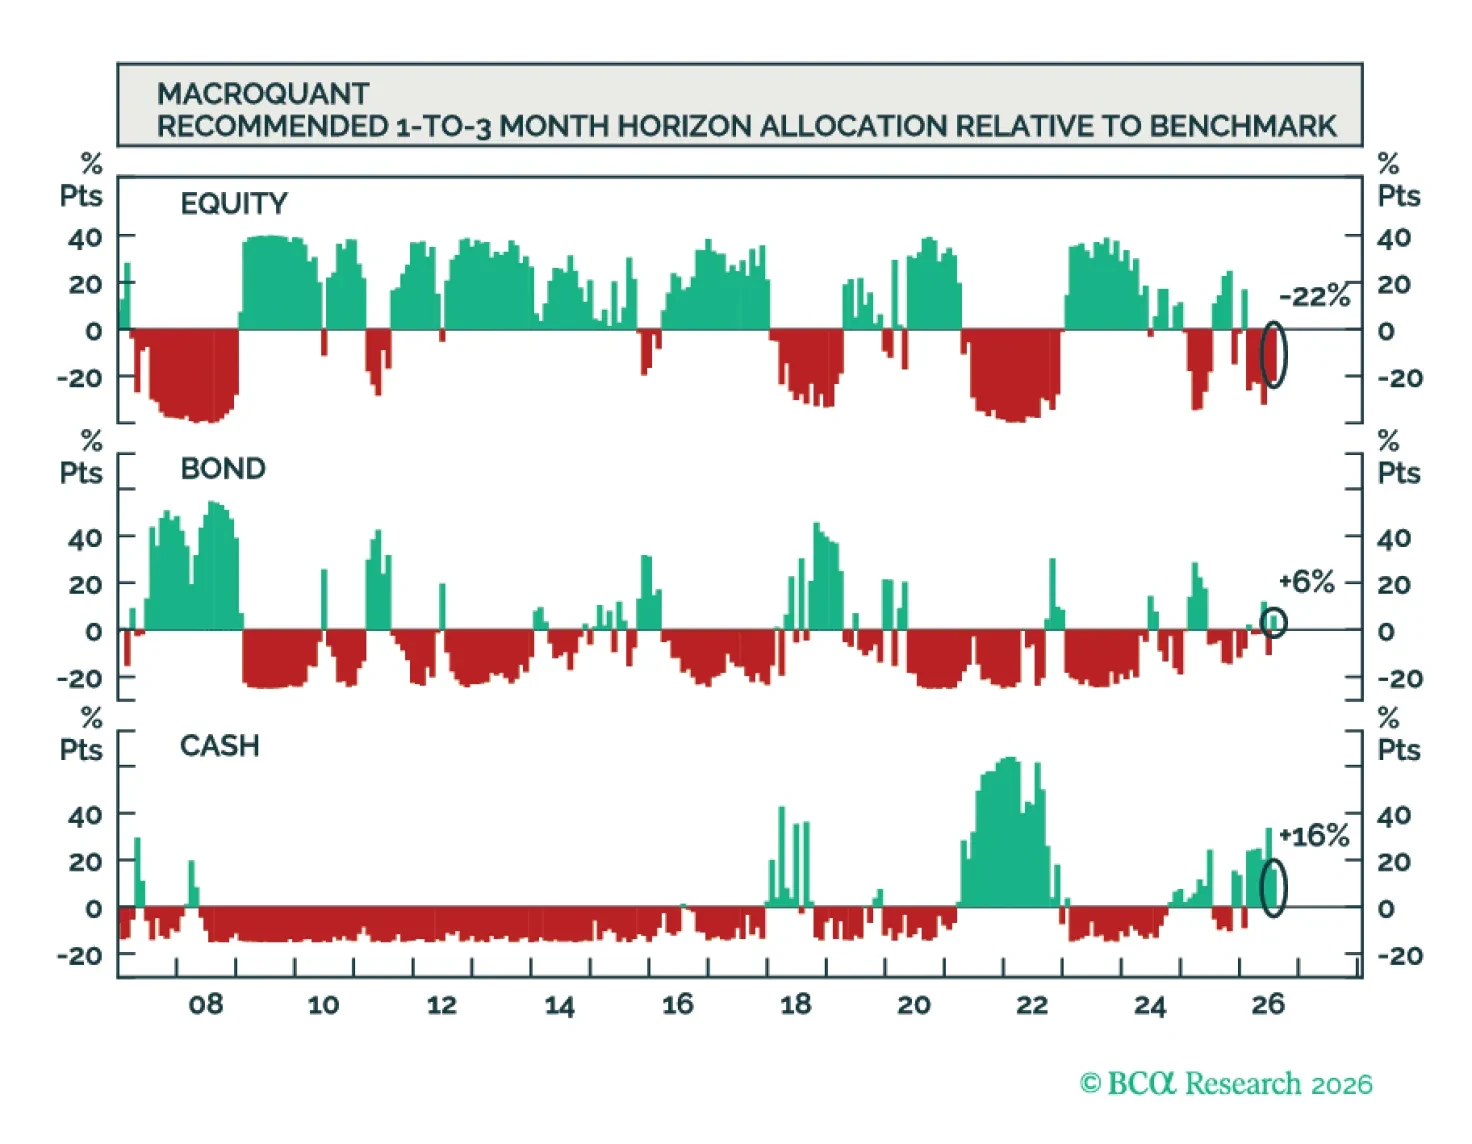
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.