Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Currencies

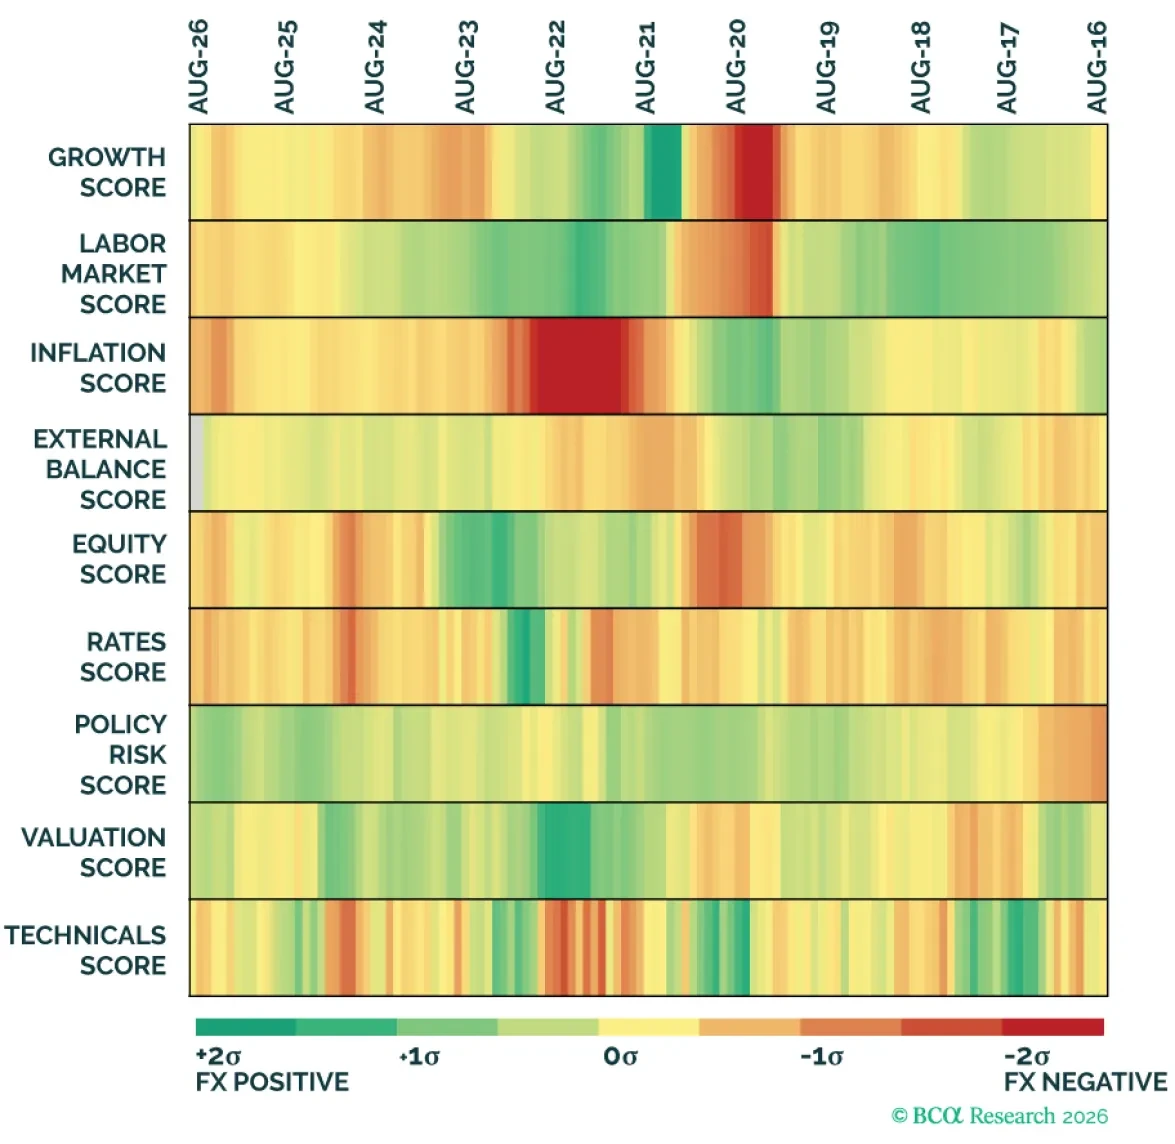
Foreign exchange markets are shaped by a wide range of macro influences. The sheer breadth of relevant information makes systematically assessing where a currency stands at any point in time a challenging analytical task. We introduce an FX scorecard that condenses the full range of data into nine thematic scores, providing a clear visual snapshot of a currency's position and how it's evolving.
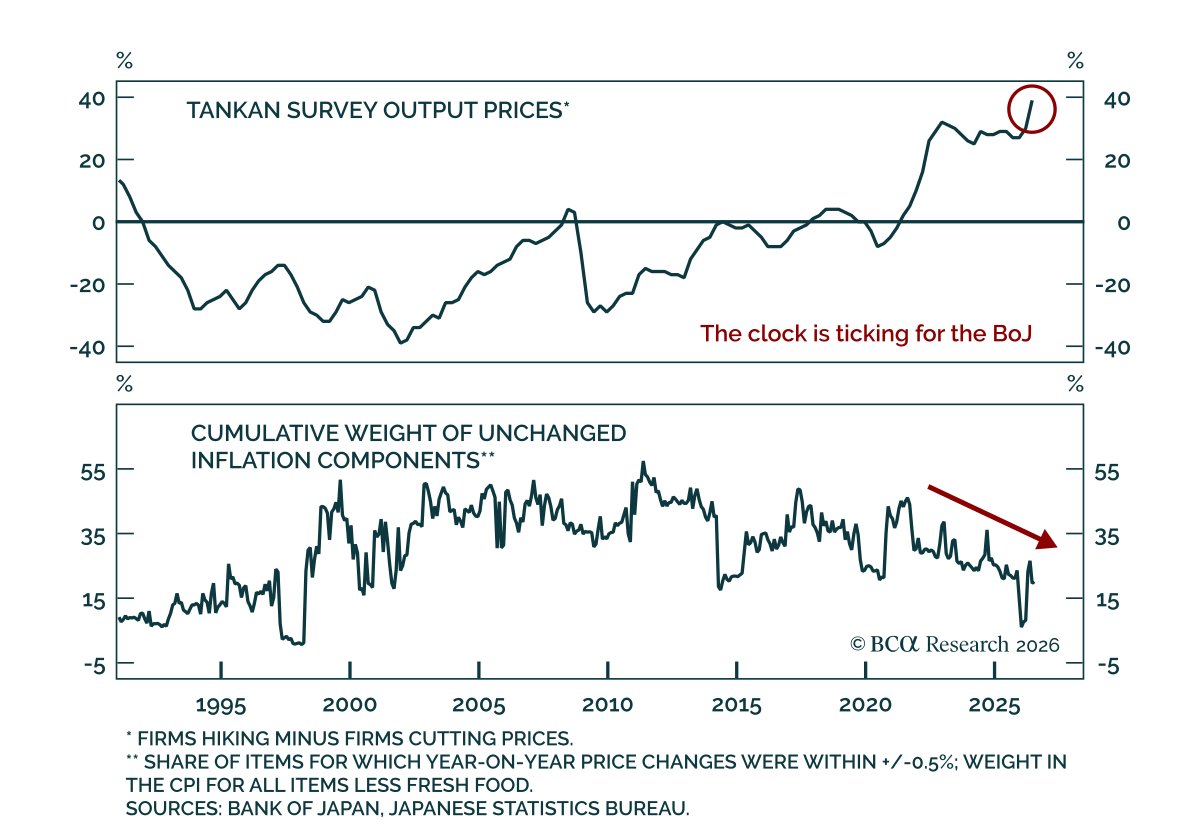
Our FICC strategists expect a hawkish BoJ pivot to drive USD/JPY toward 99. The Japanese central bank is set to signal a decisive tightening turn at its September 18 meeting, and our colleagues read the yen's weakness as an inflation problem rather than a…

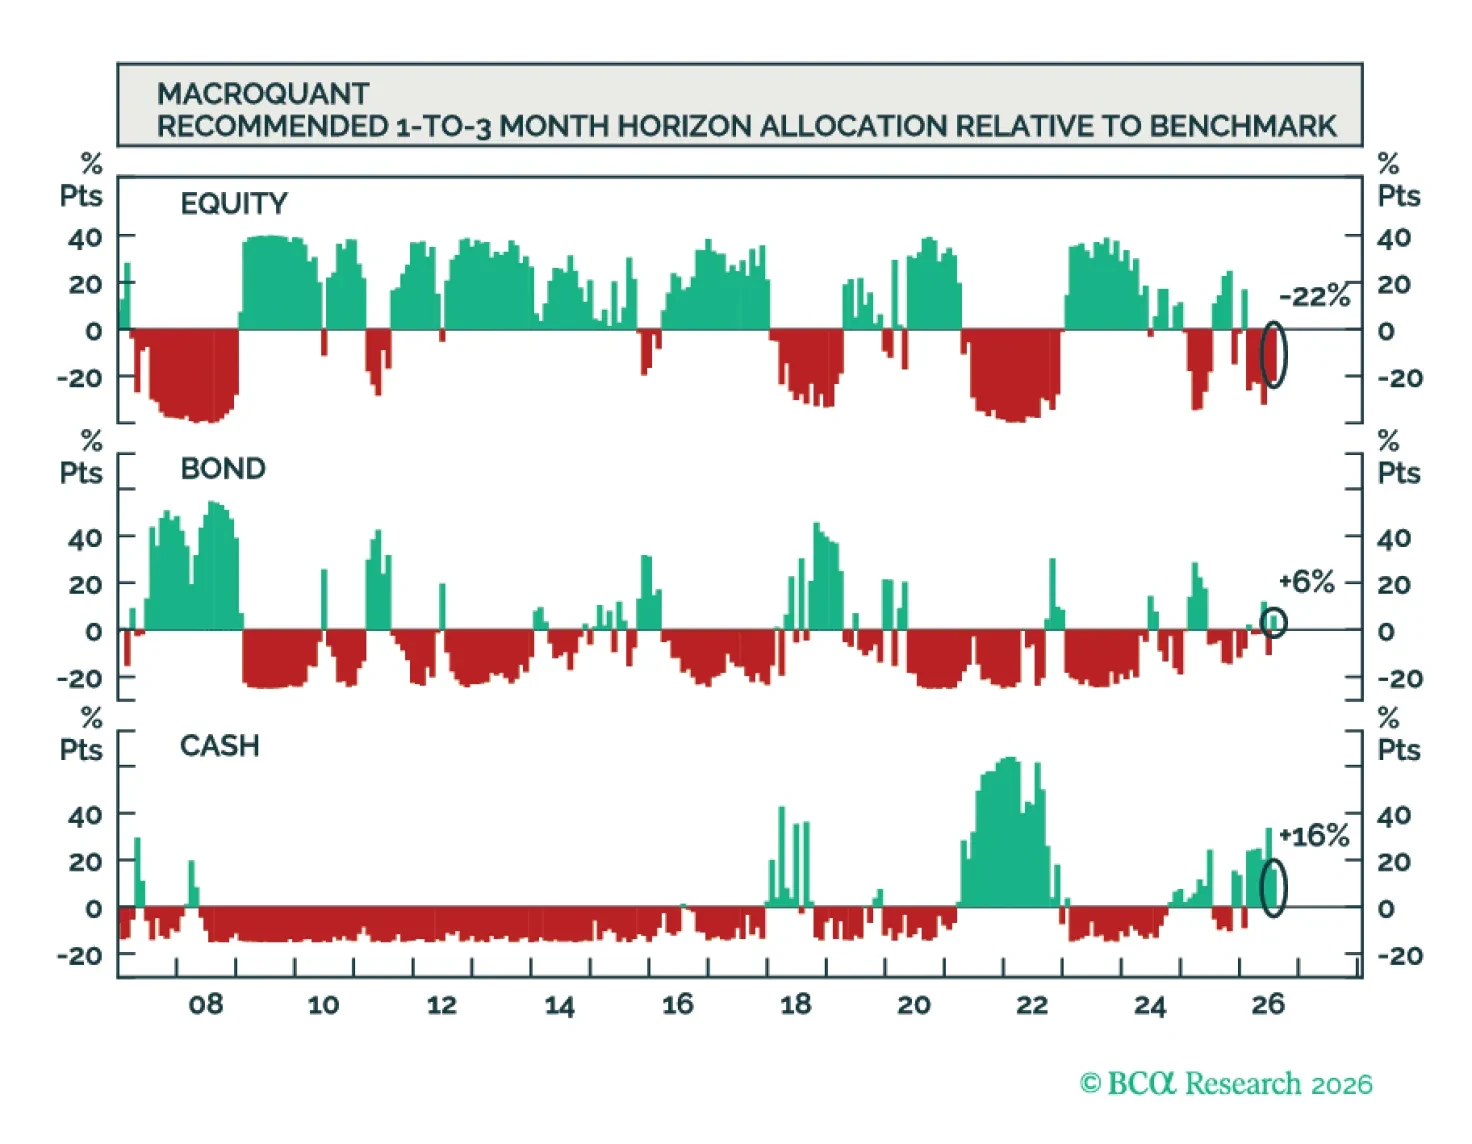
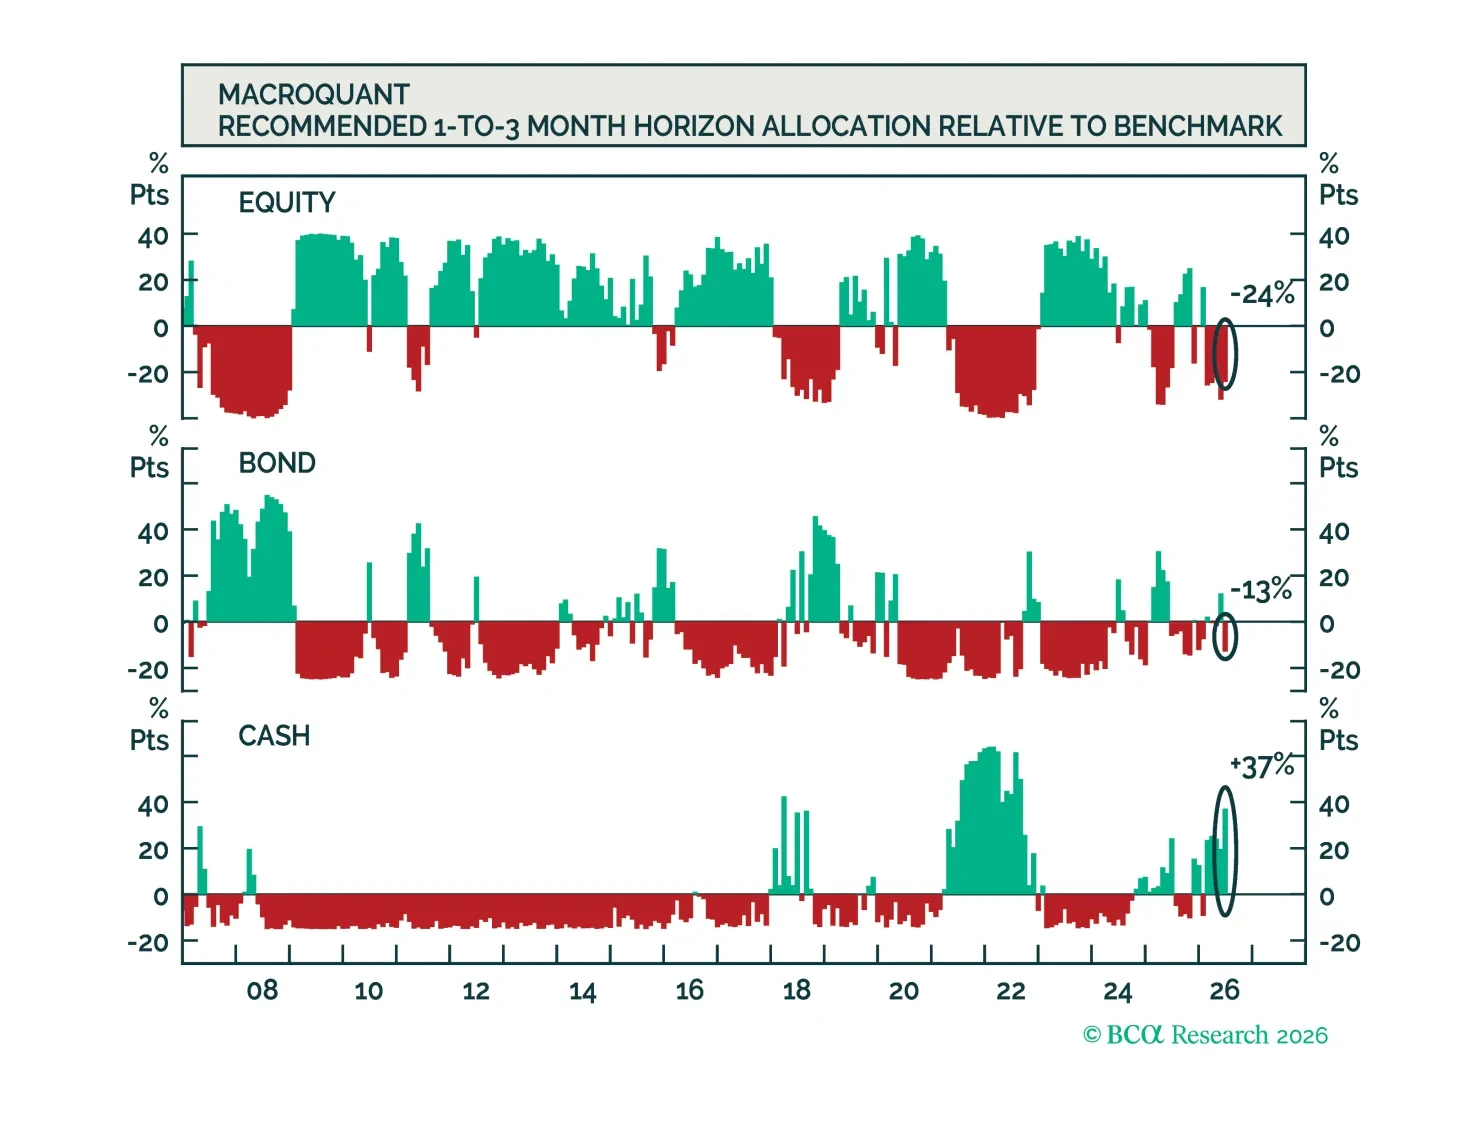
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.

Joint US and Japanese intervention can curb JPY weakness temporarily, but a durable turn still requires narrower rate differentials. Our Chart Of The Week comes from FX Strategist Artem Sakhbiev. The joint MoF and US Treasury intervention signals that…

MacroQuant recommends a slight underweight position in equities, and favors a below-benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, neutral on gold, constructive on copper, and very bullish on oil.
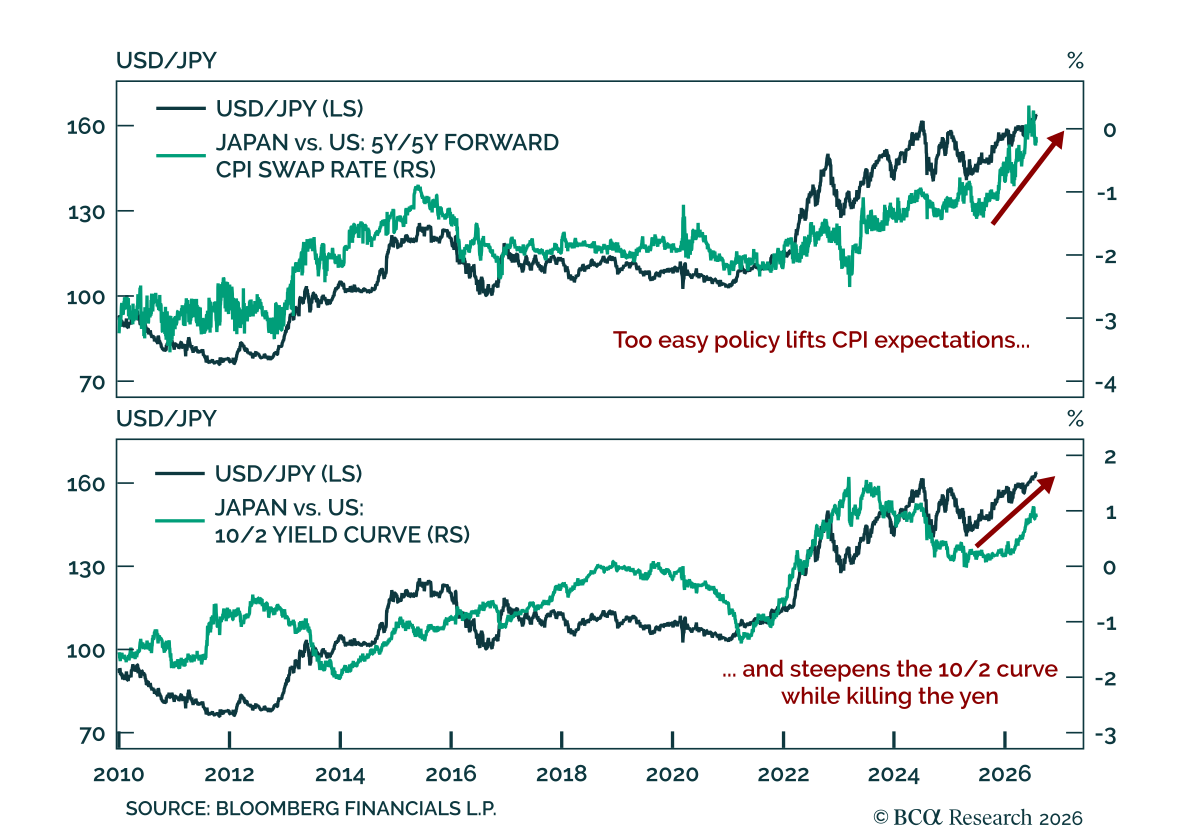
Our FICC strategists see the yen's collapse and JGB weakness driven by the Bank of Japan's easy policy, not fiscal stress. Japan's exploding debt is not to blame: cross-country evidence shows Japanese yields track savings-investment fundamentals rather than…
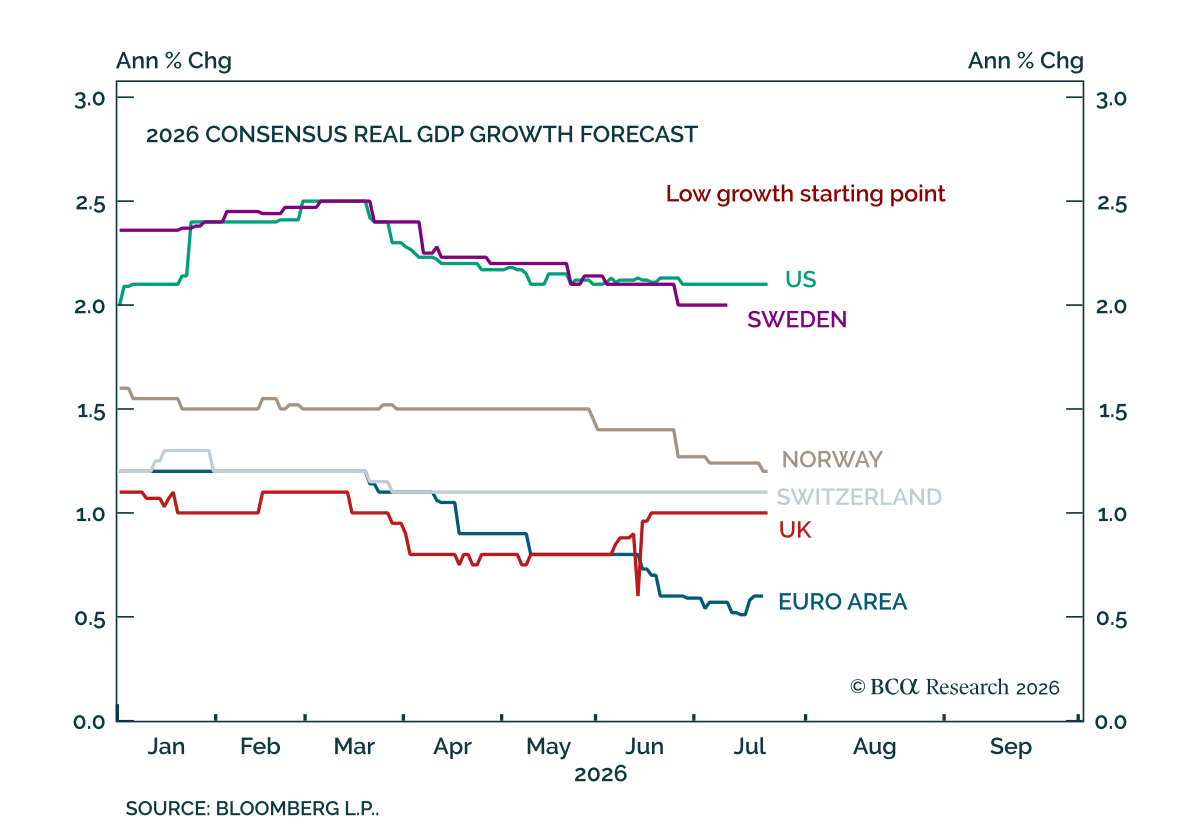
Our European and FICC strategists remain tactically constructive on Europe while urging investors to prepare portfolios for a more challenging medium-term environment. Rather than issue a single house forecast, our colleagues present two credible but…

Goldilocks, with fault lines underneath. Our first joint FICC outlook lays out where growth, inflation, and policy are headed this quarter and where the calm could crack.
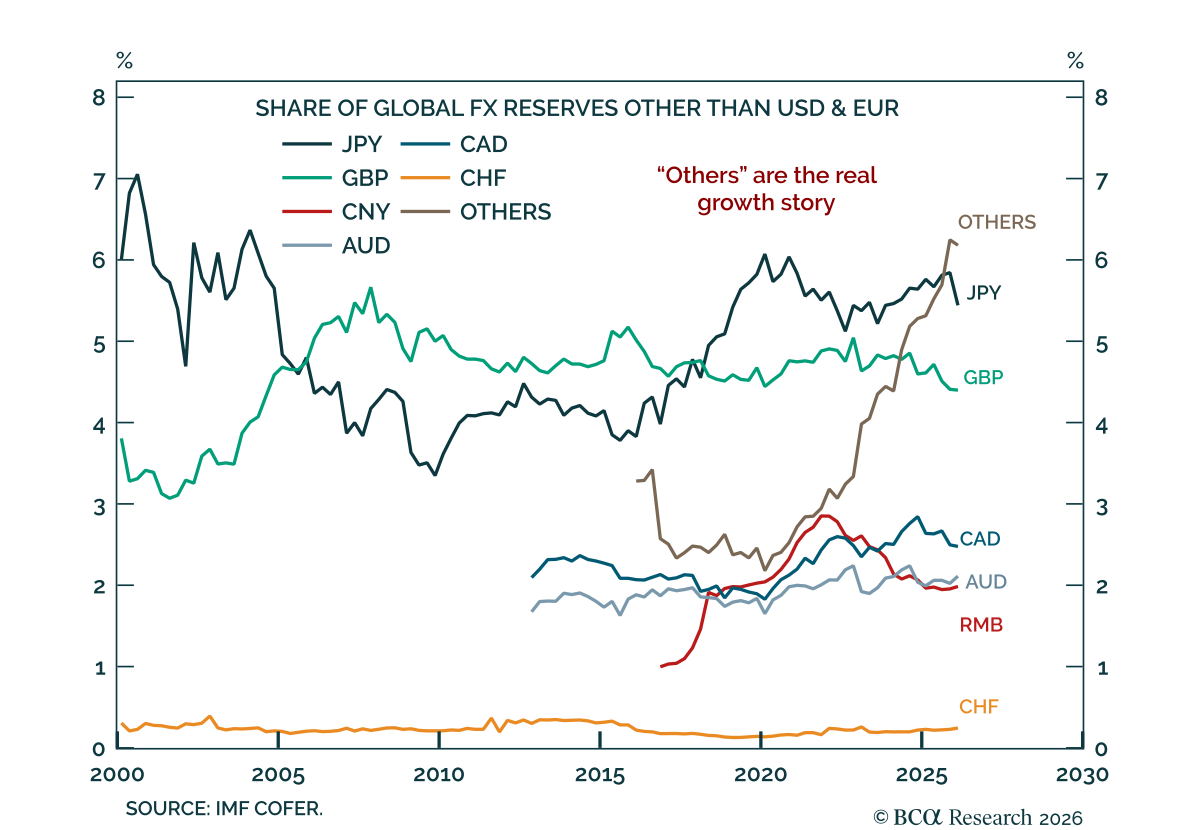
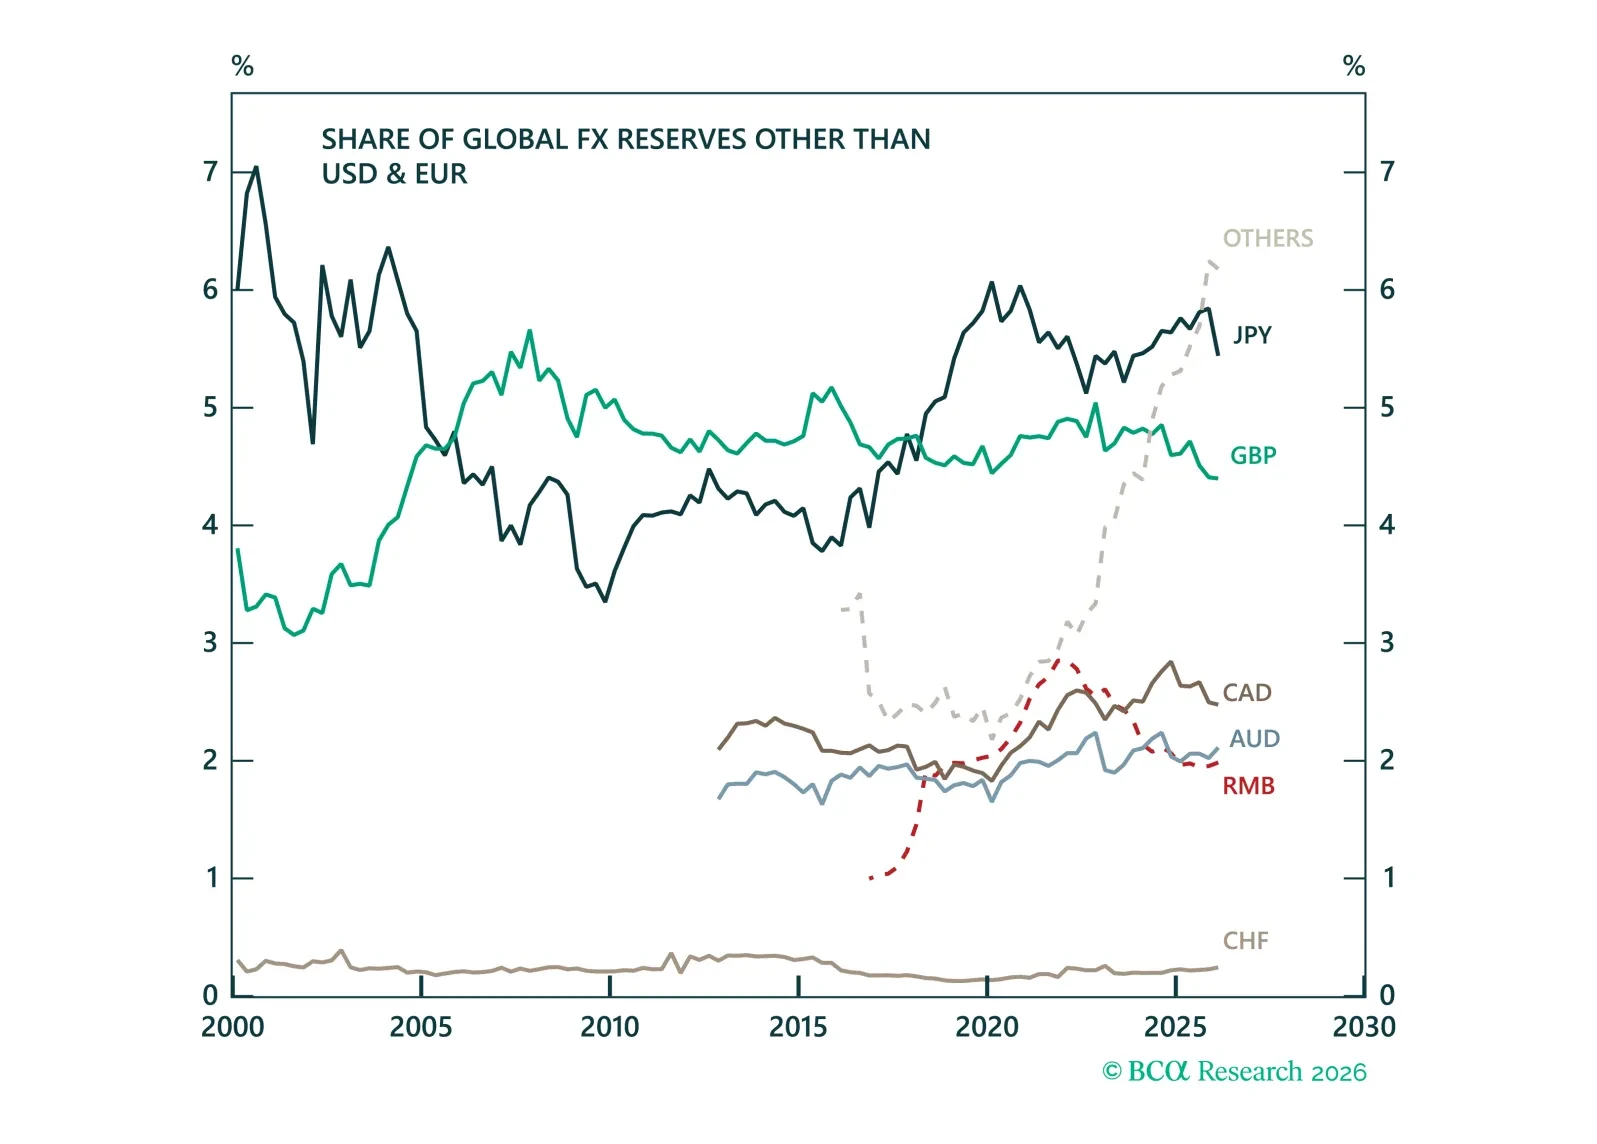
Our FX strategists expect the global reserve system to grow less dollar-centric. This will benefit a widening set of smaller fiat currencies rather than any single successor to the USD. The dollar's share of global reserves has fallen more than five…
Special Report

The dollar is not being replaced by a single rival, it is being diluted by a rising cast of “other” reserve currencies. This report identifies the hidden winners of reserve diversification and why they may matter more than investors think.