Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Australia

After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
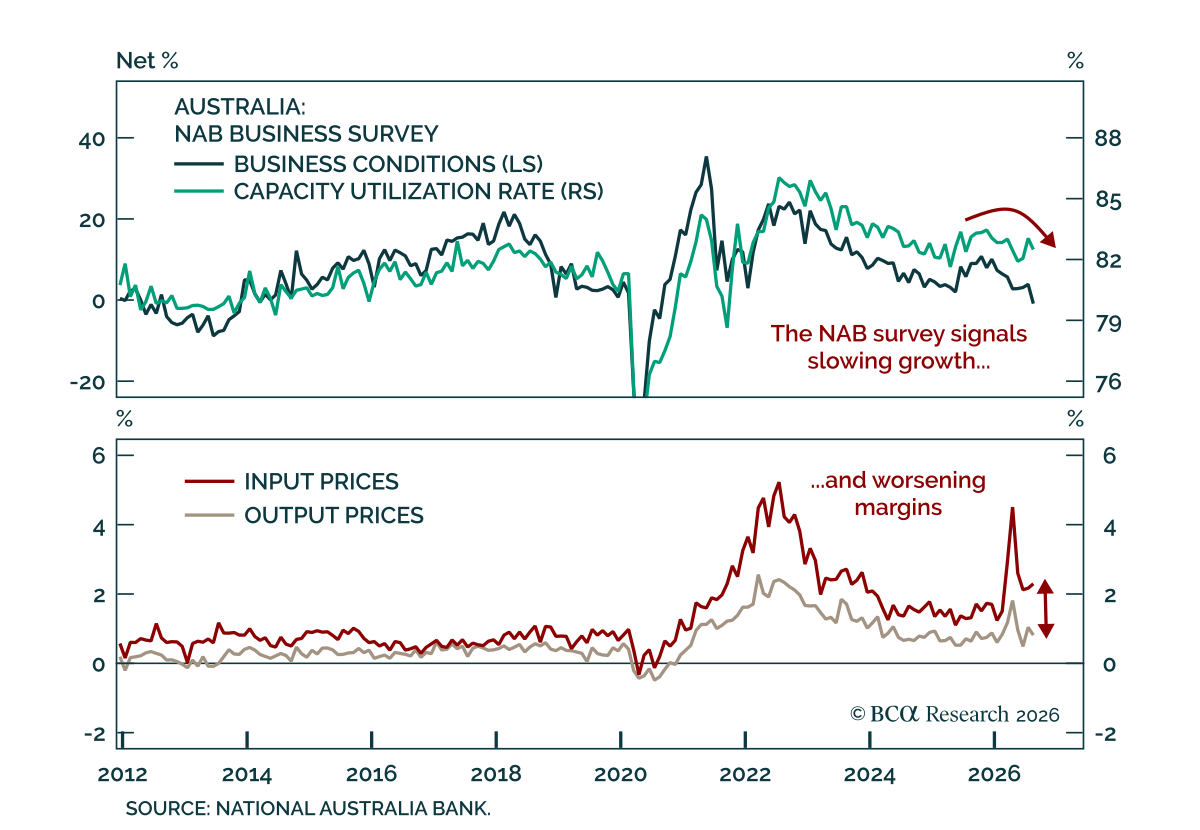
Australia's August NAB Business Survey points to a cooling economy and supports an on-hold RBA. Business conditions turned negative for the first time since 2020, falling to -1 from 4 and well below the long-term average. Profits and sales dropped to their…
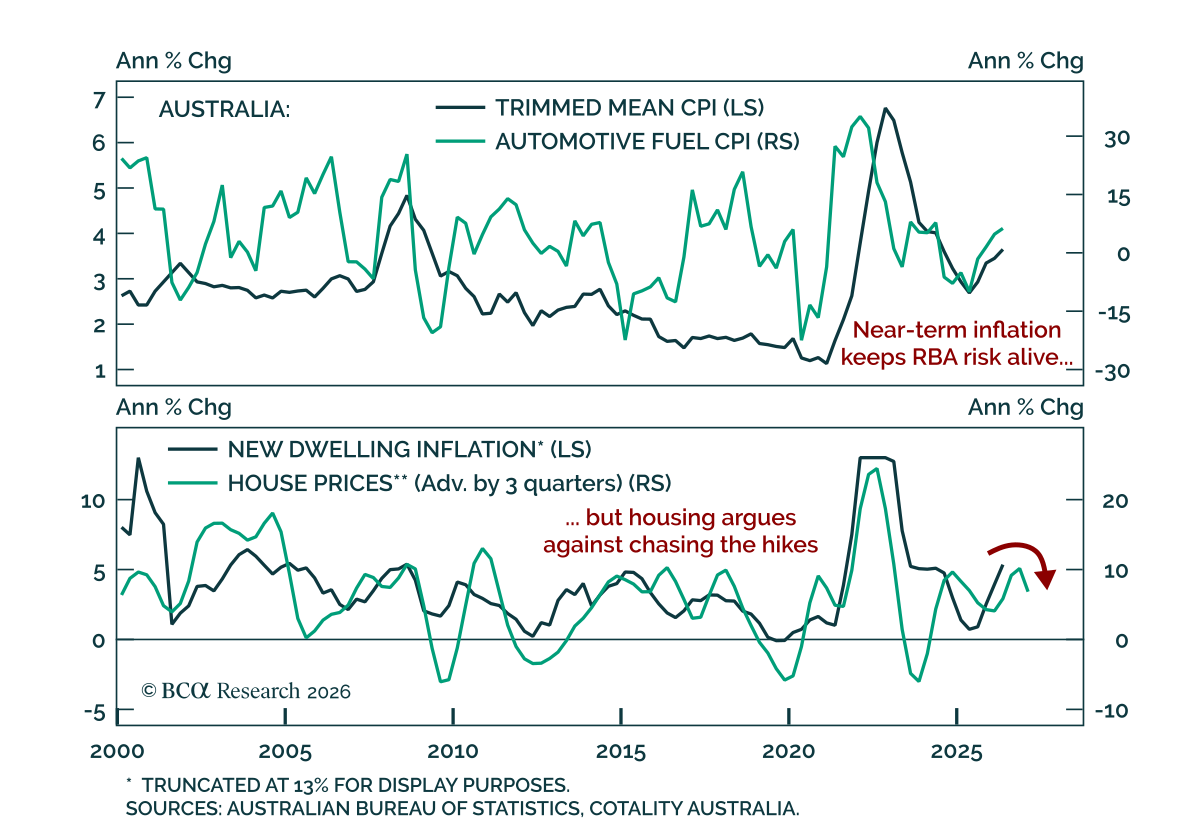
Australia’s latest inflation beat will keep RBA tightening risk alive, but the forces shaping inflation over the next year are becoming more disinflationary. Headline CPI eased to 3.5% y/y in July from 3.8%, but exceeded the 3.3% consensus. While trimmed-mean…
Our FICC strategists remain neutral on Australian government bonds, upgrade New Zealand government bonds to overweight, and recommend long AUD/NZD. Housing is becoming a disinflationary force in both economies, though for different reasons. Australian house…

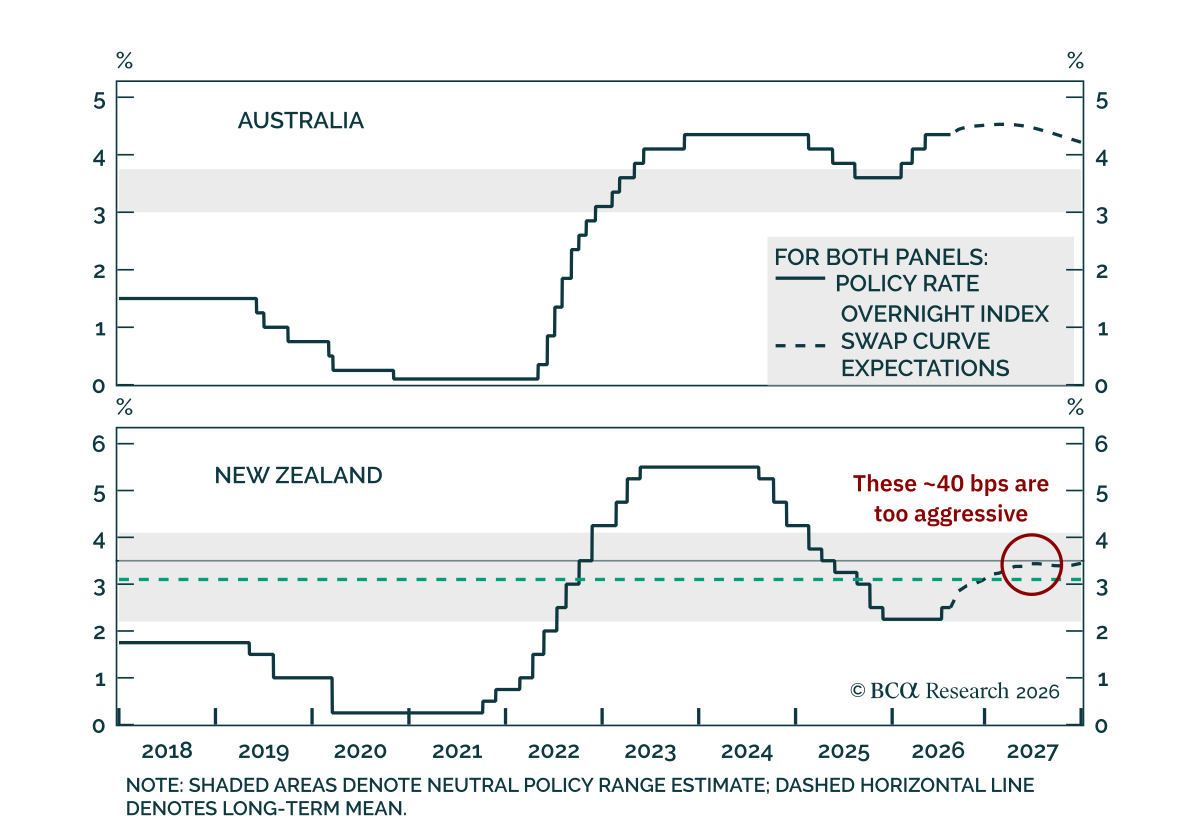
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.

The RBA's tightening cycle is likely over, despite Governor Bullock's hawkish tone. The cash rate was left unchanged at 4.35% for a second consecutive meeting, in line with consensus, after three hikes earlier this year. The decision was unanimous. Updated…

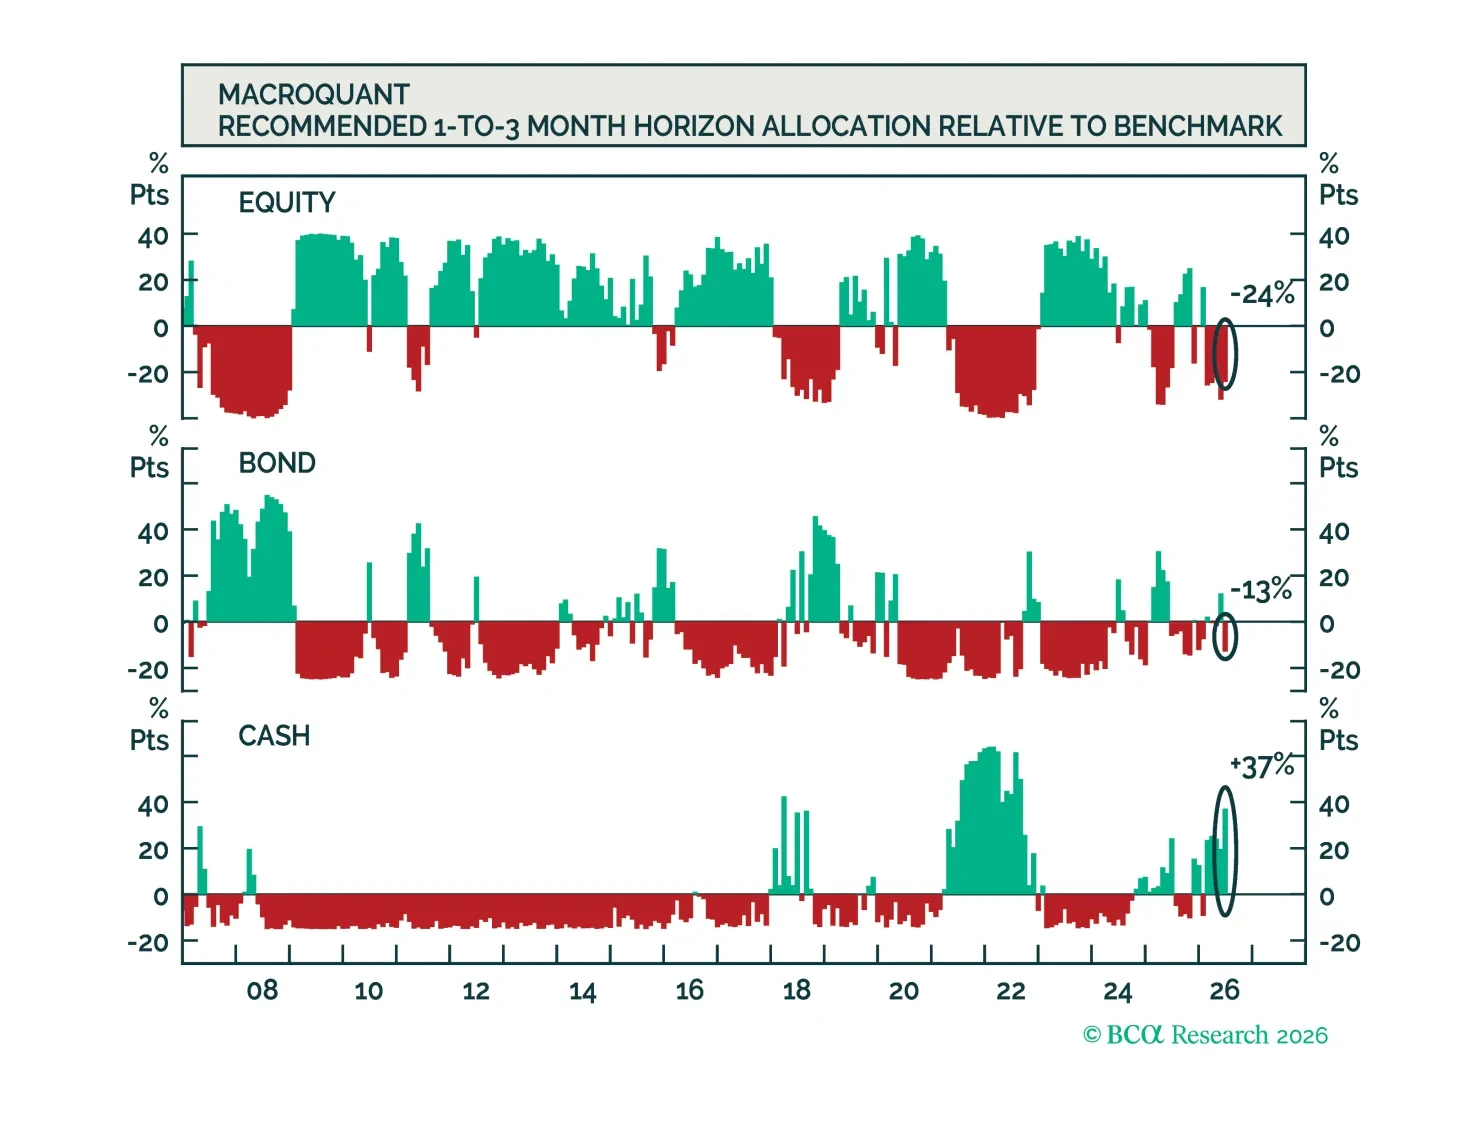
MacroQuant recommends a slight underweight position in equities, and favors a below-benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, neutral on gold, constructive on copper, and very bullish on oil.
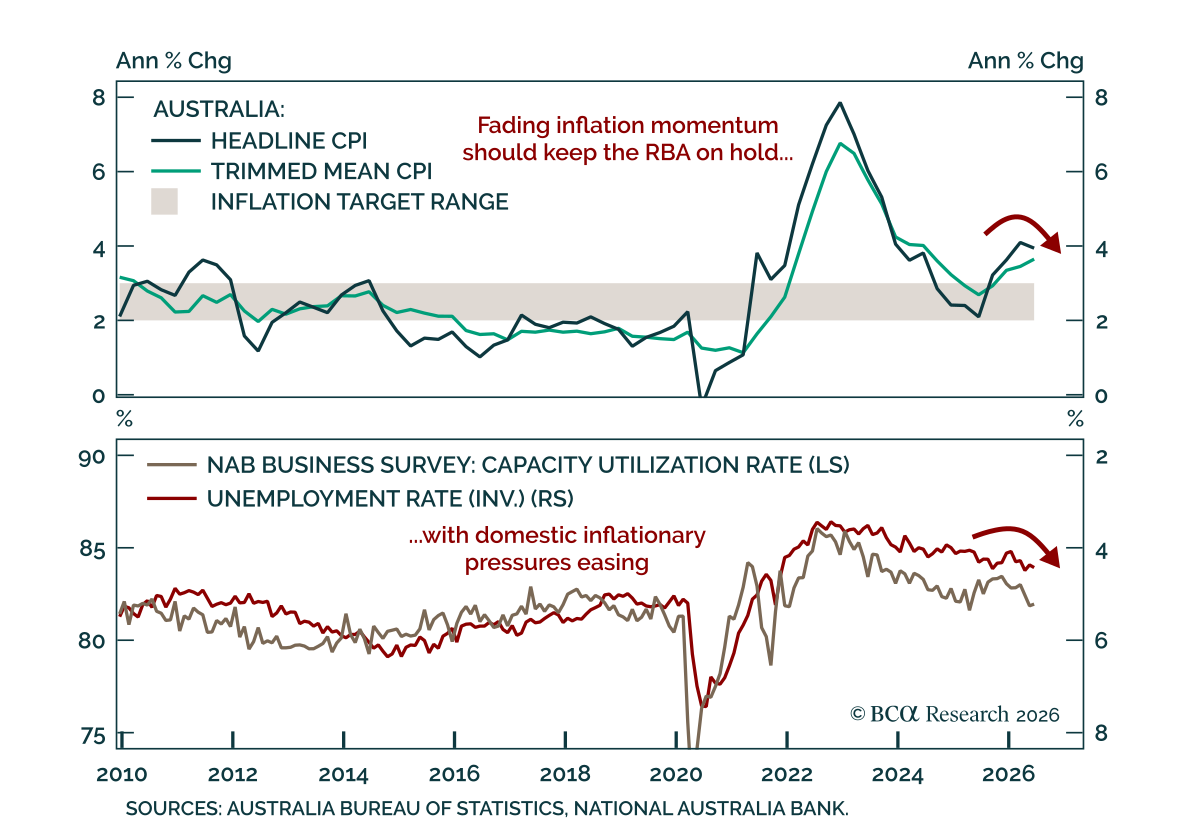
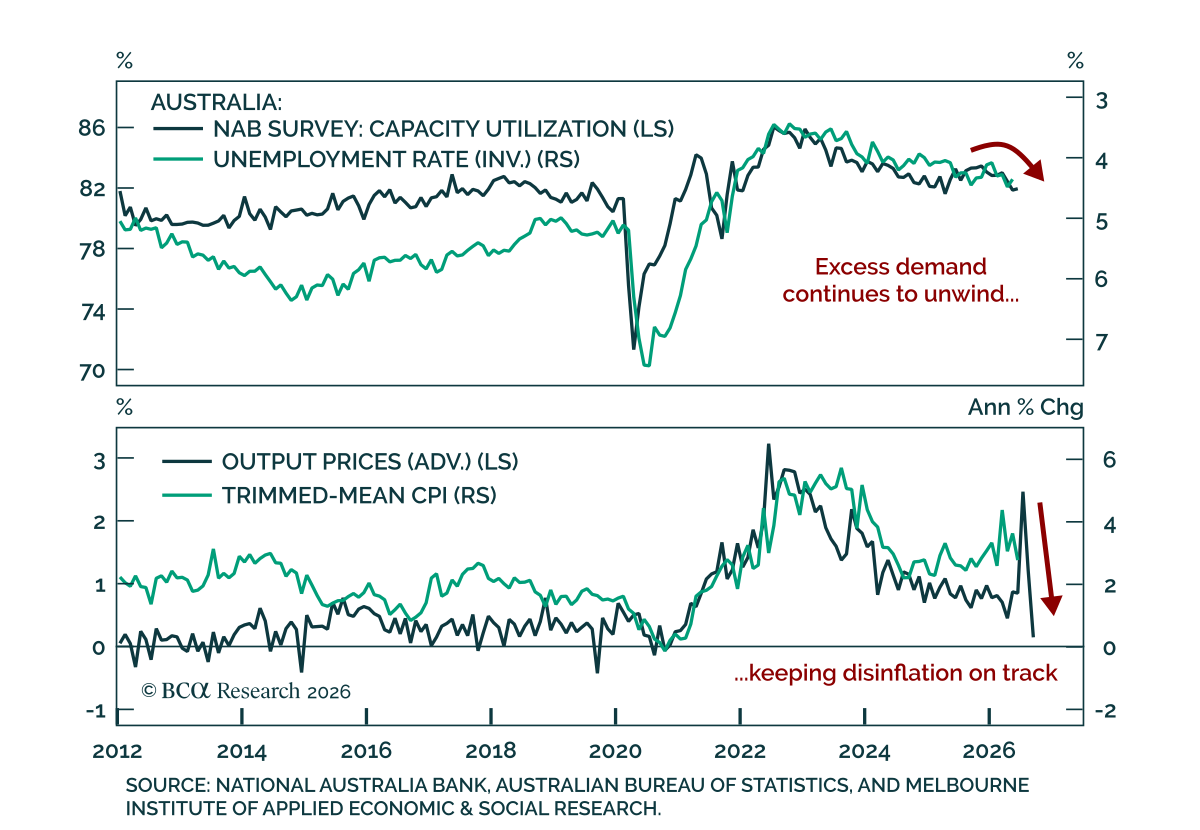
Australia's softer-than-expected Q2 inflation report reinforces the case for a RBA hold. While trimmed mean CPI, the RBA's preferred underlying measure, edged up to 3.6% y/y from 3.5%, it undershot consensus and the RBA's own forecast. The quarterly rate held…
Australia's June NAB Business Survey points to a cooling economy, reinforcing the case for an extended RBA pause. Business conditions held at +3 for a third consecutive month, while business confidence, the more forward-looking measure, rebounded from -14 to…
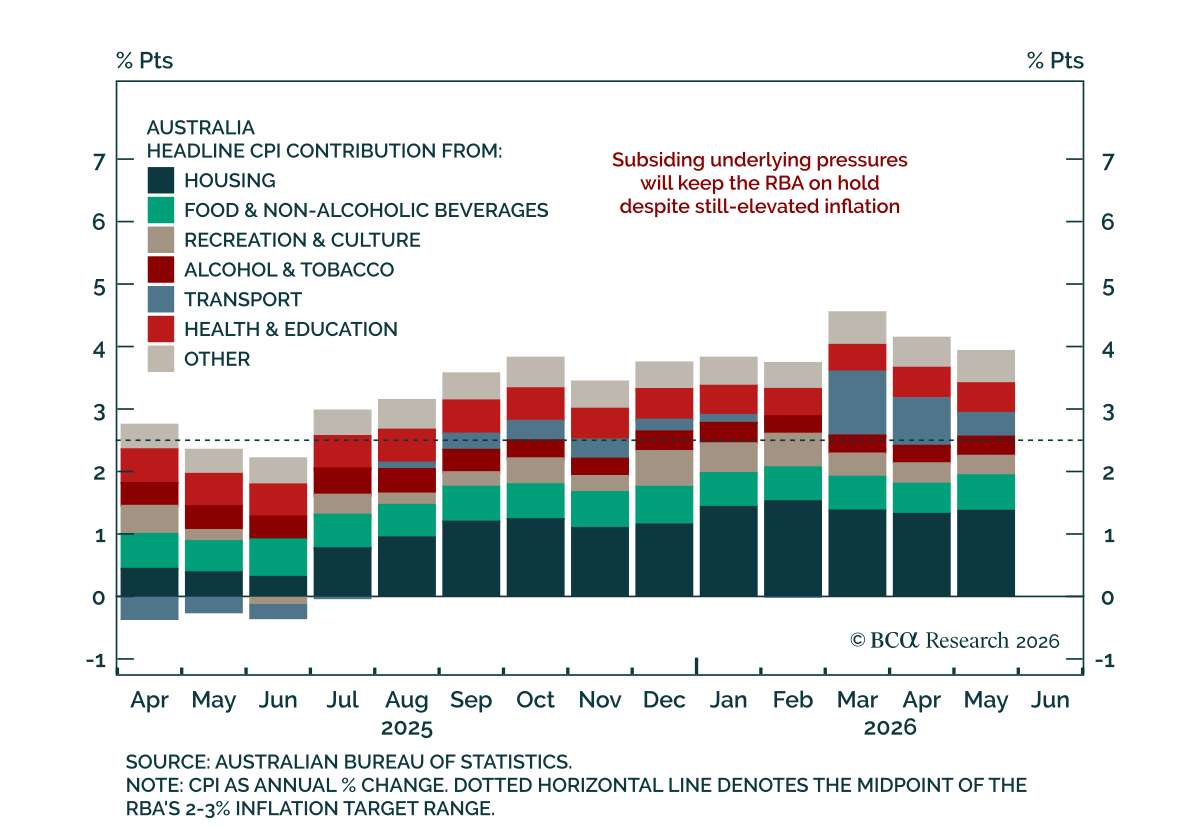
Australia's May data came in firmer than expected, but the RBA will stay on hold. Headline inflation eased to 4% y/y (-0.7% m/m) from 4.2% (0.4%), undershooting estimates. Lower energy prices cooled the print. The trimmed mean, however, climbed to 3.6% y/y…