Earnings
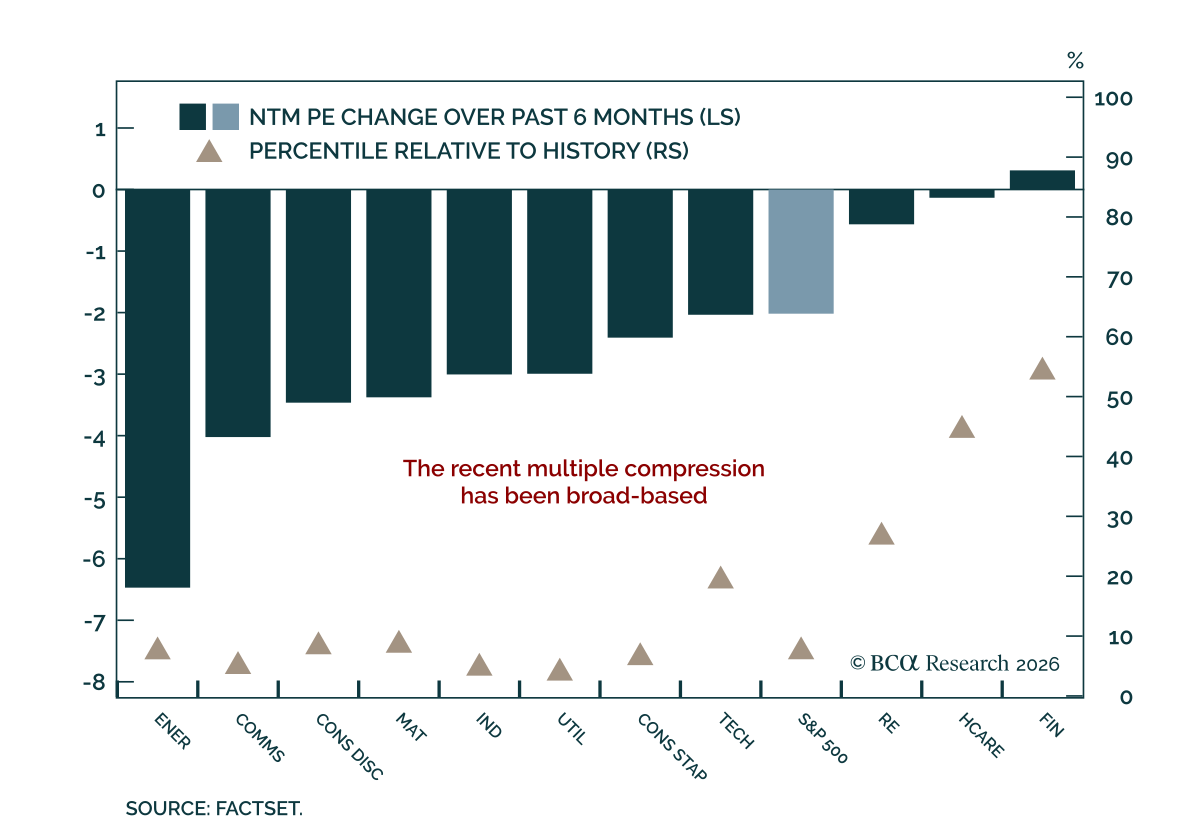
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
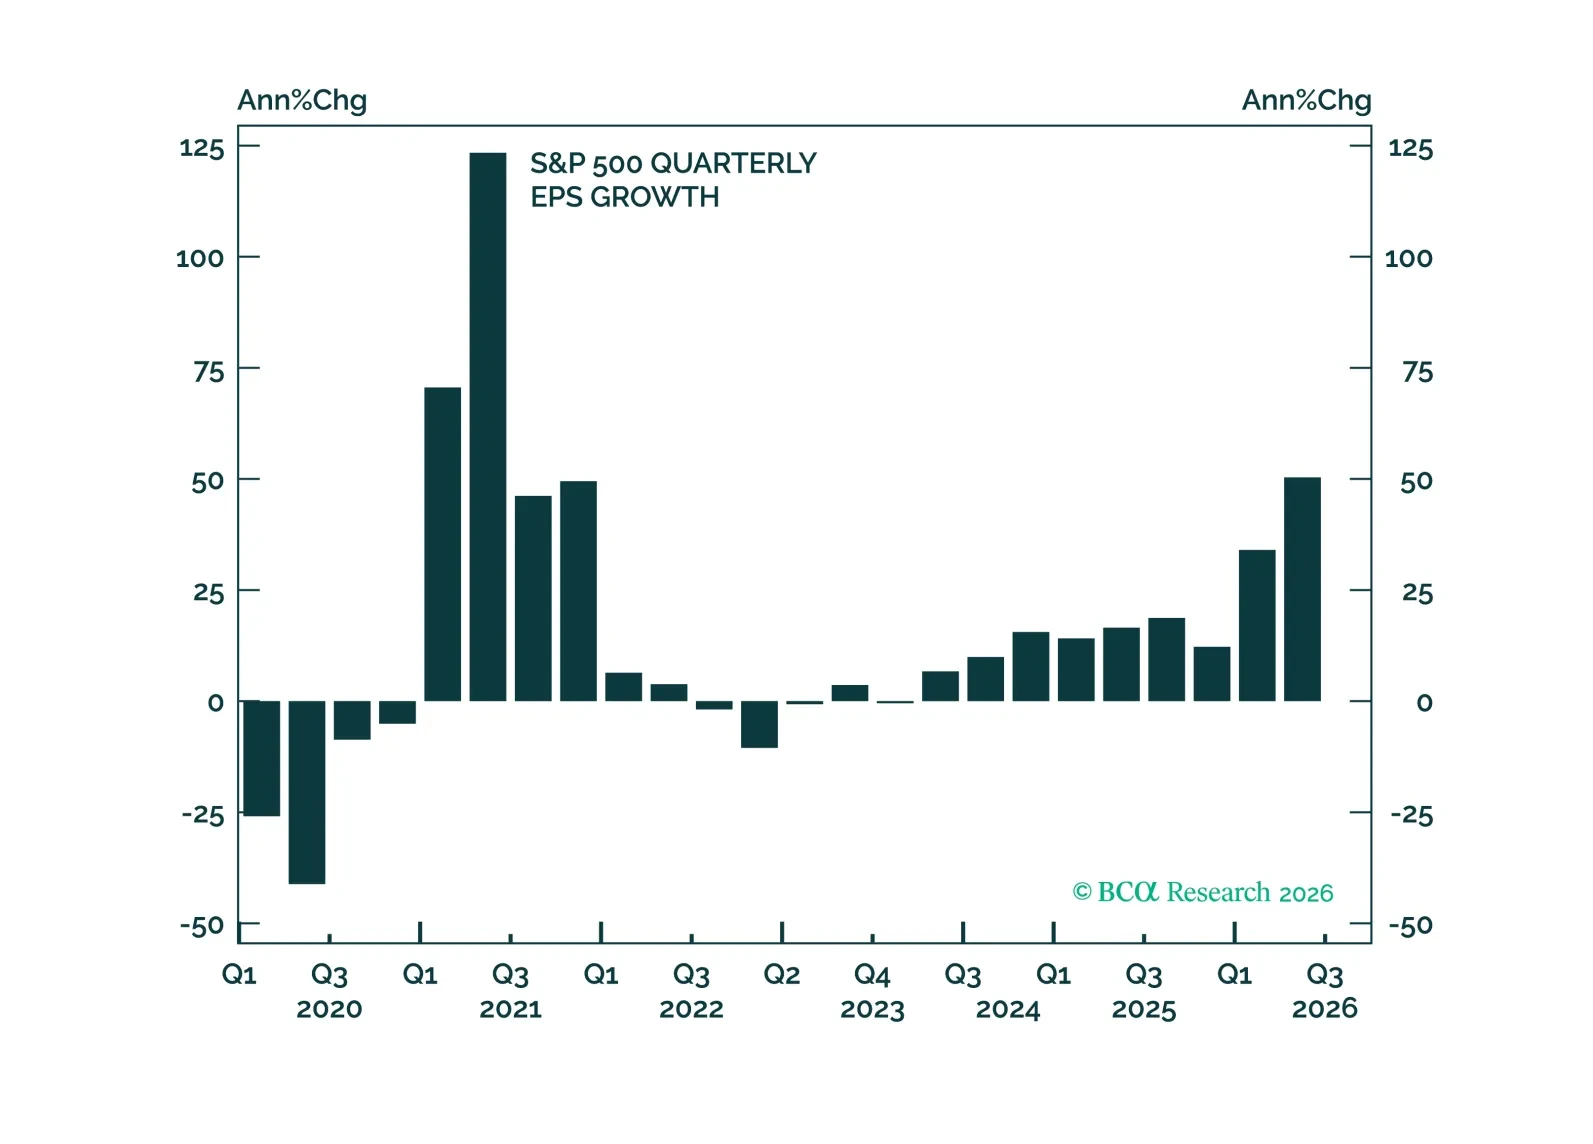
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.
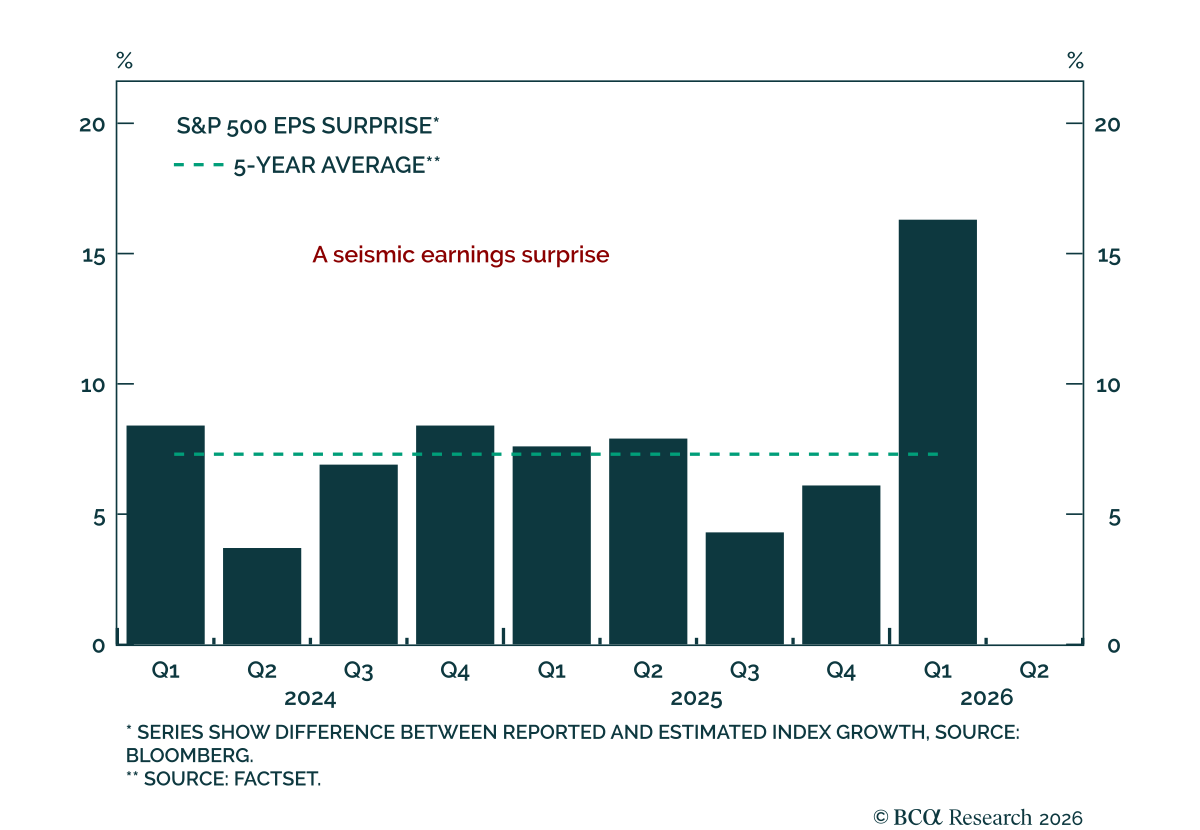
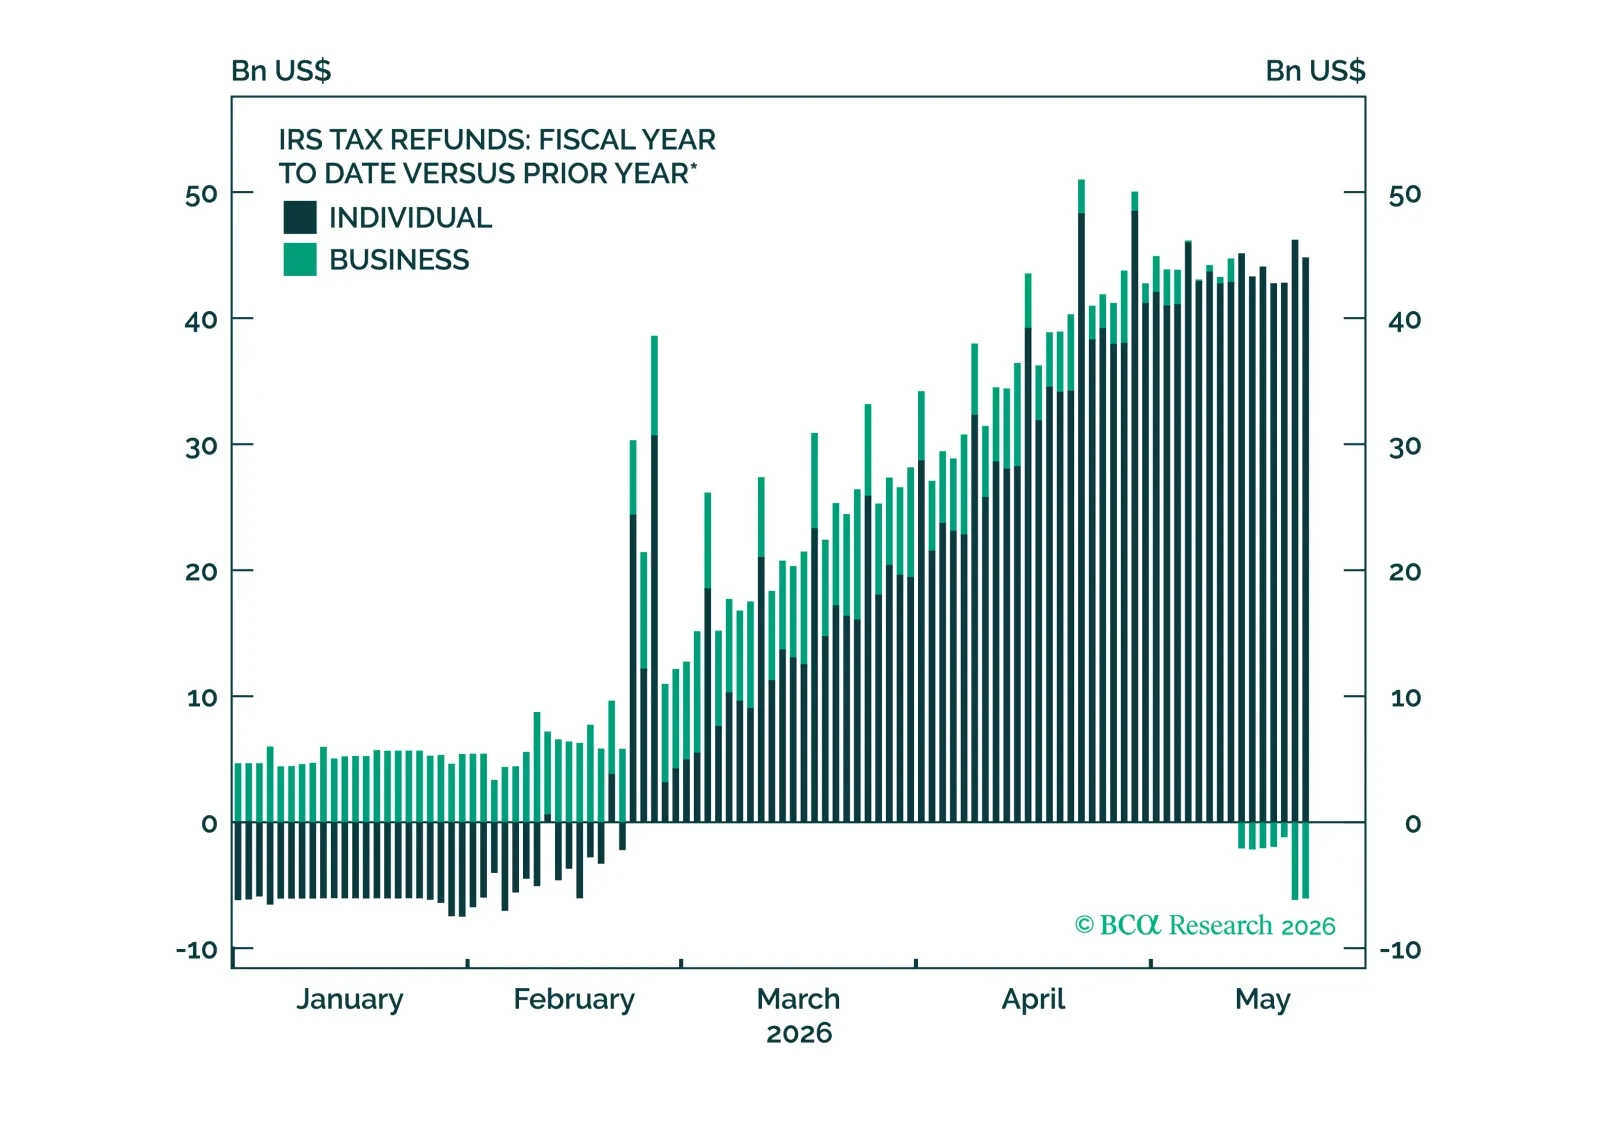
Against the earnings-versus-everything-else market backdrop, stellar earnings are easily outweighing elevated oil prices, rising yields and the increased probability that the Fed may hike rates before the year is out. US allocators should remain invested in equities.
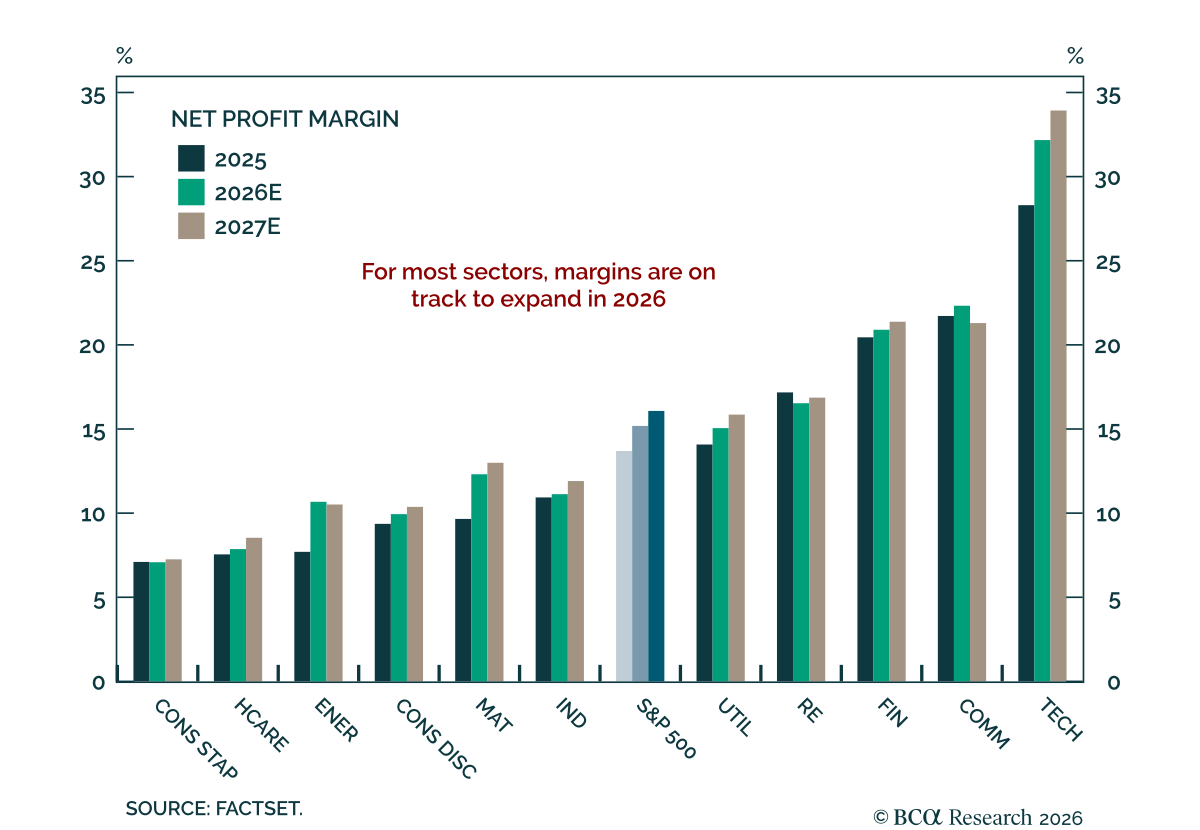
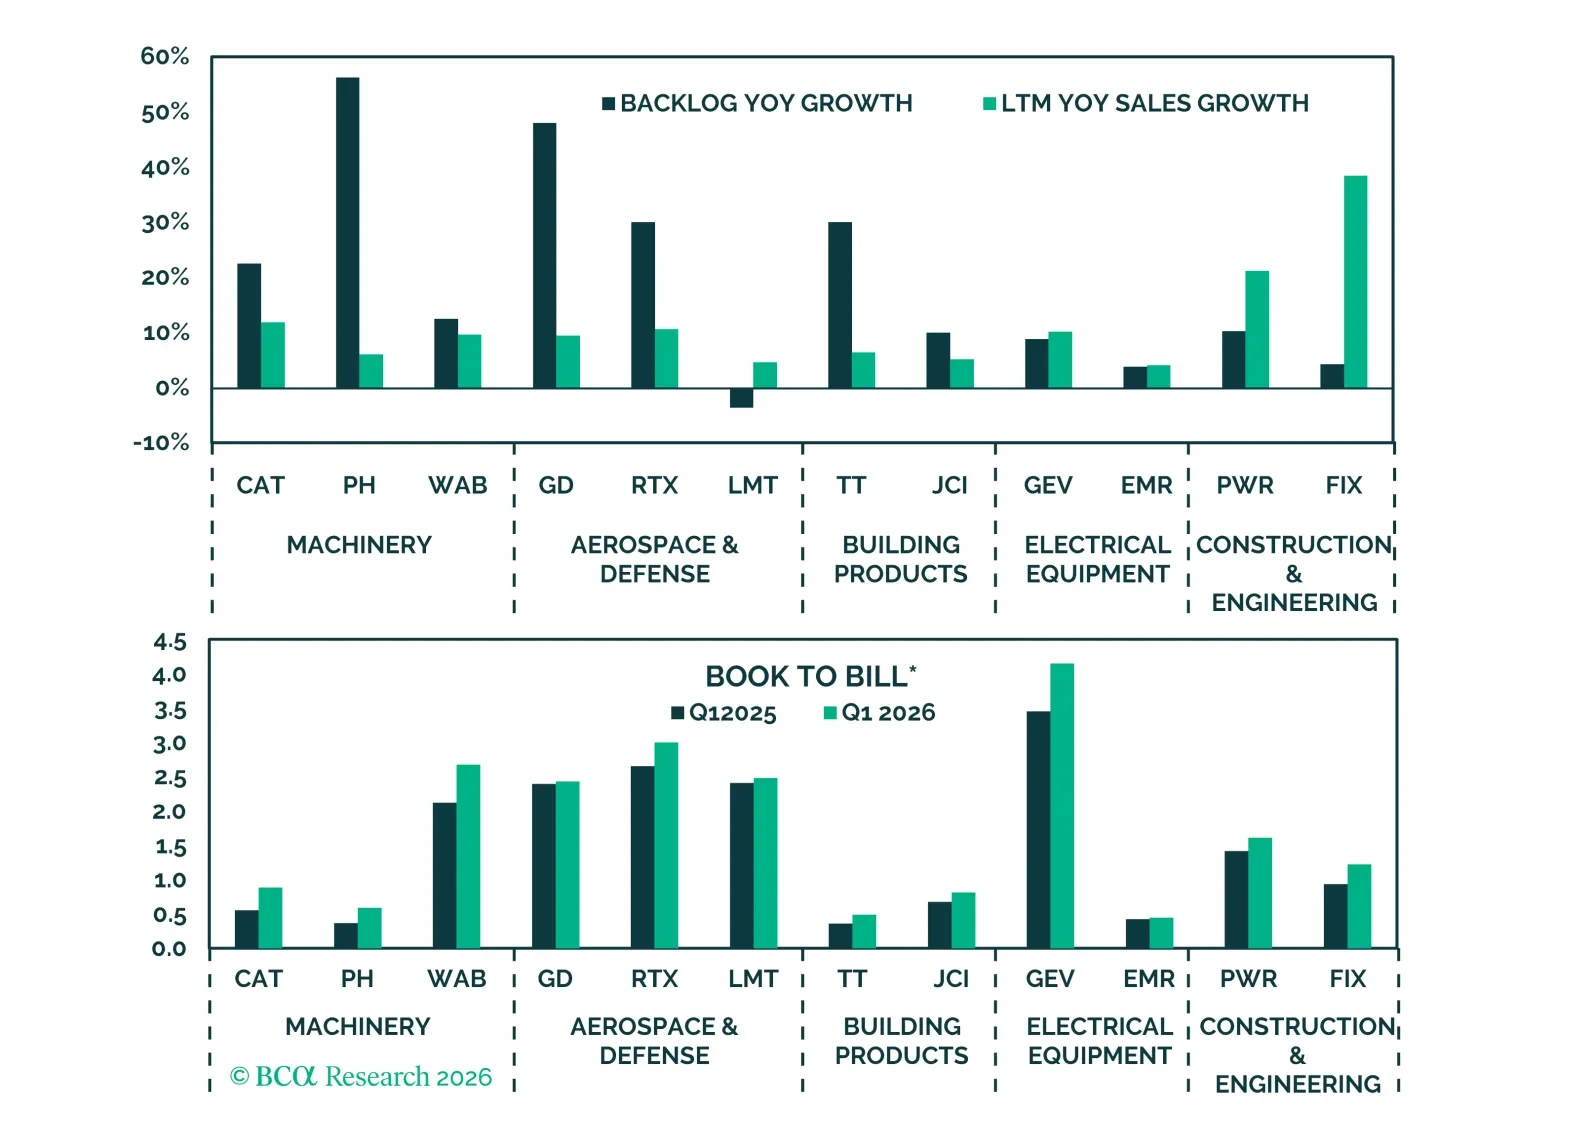
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, while geopolitical and credit risks remain contained and not yet systemic.

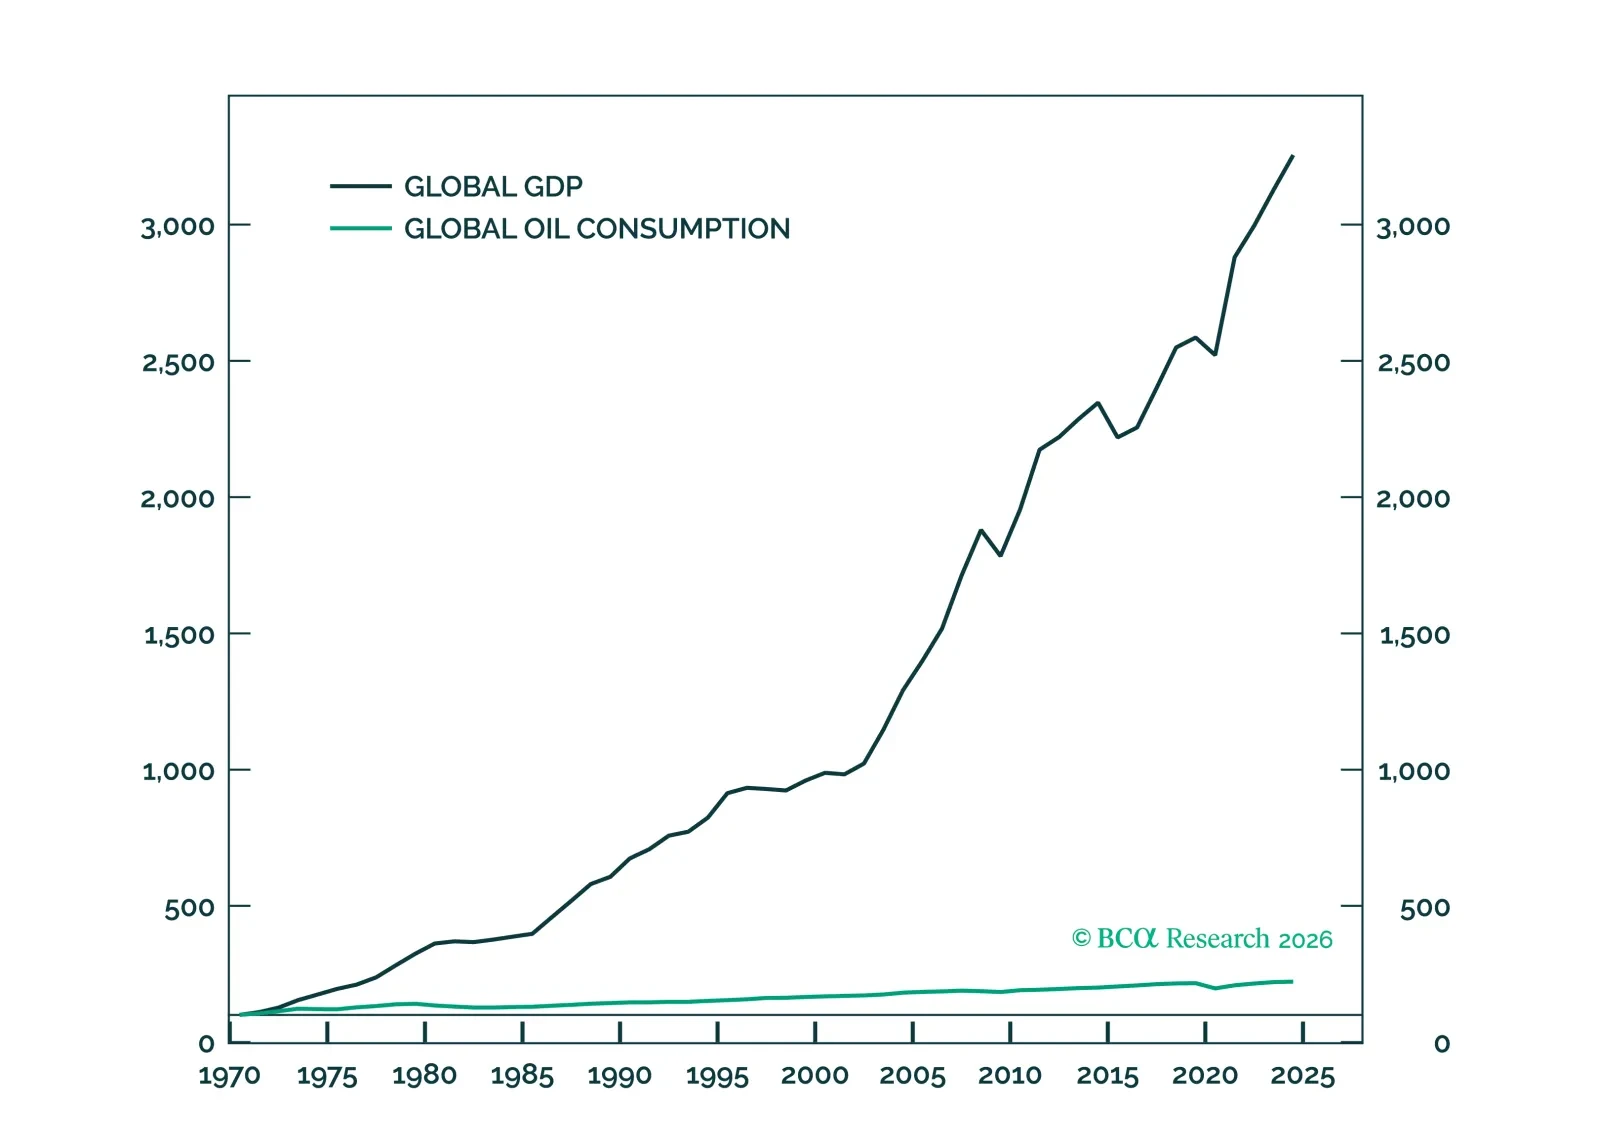
The S&P 500 finished last week at an all-time high as optimism over earnings has pushed the Iran conflict out of the spotlight. Despite uncertainty in the Strait of Hormuz, we do not think investors have enough evidence to justify underweighting equities and other risk assets.
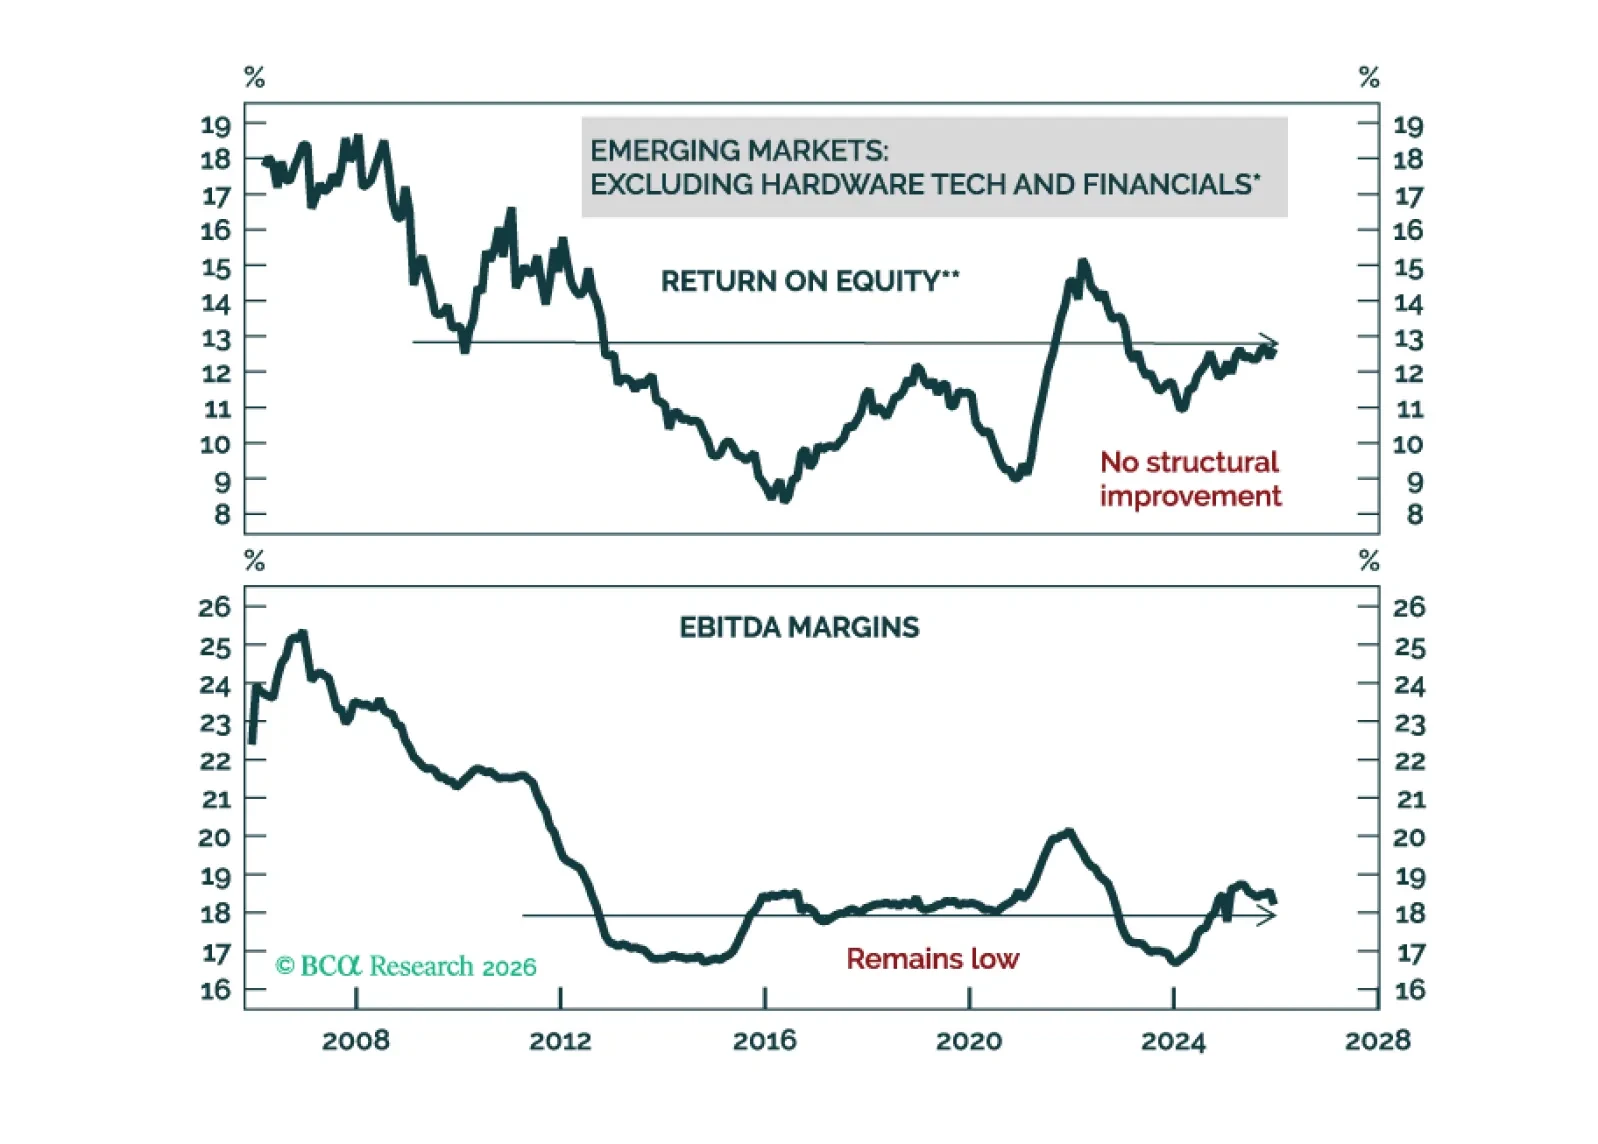
Outside Asian semiconductor producers, EM corporate earnings and profitability have seen little improvement. Despite the ceasefire in the Middle East, the medium-term outlook for EM stocks is still unattractive.