Tariffs
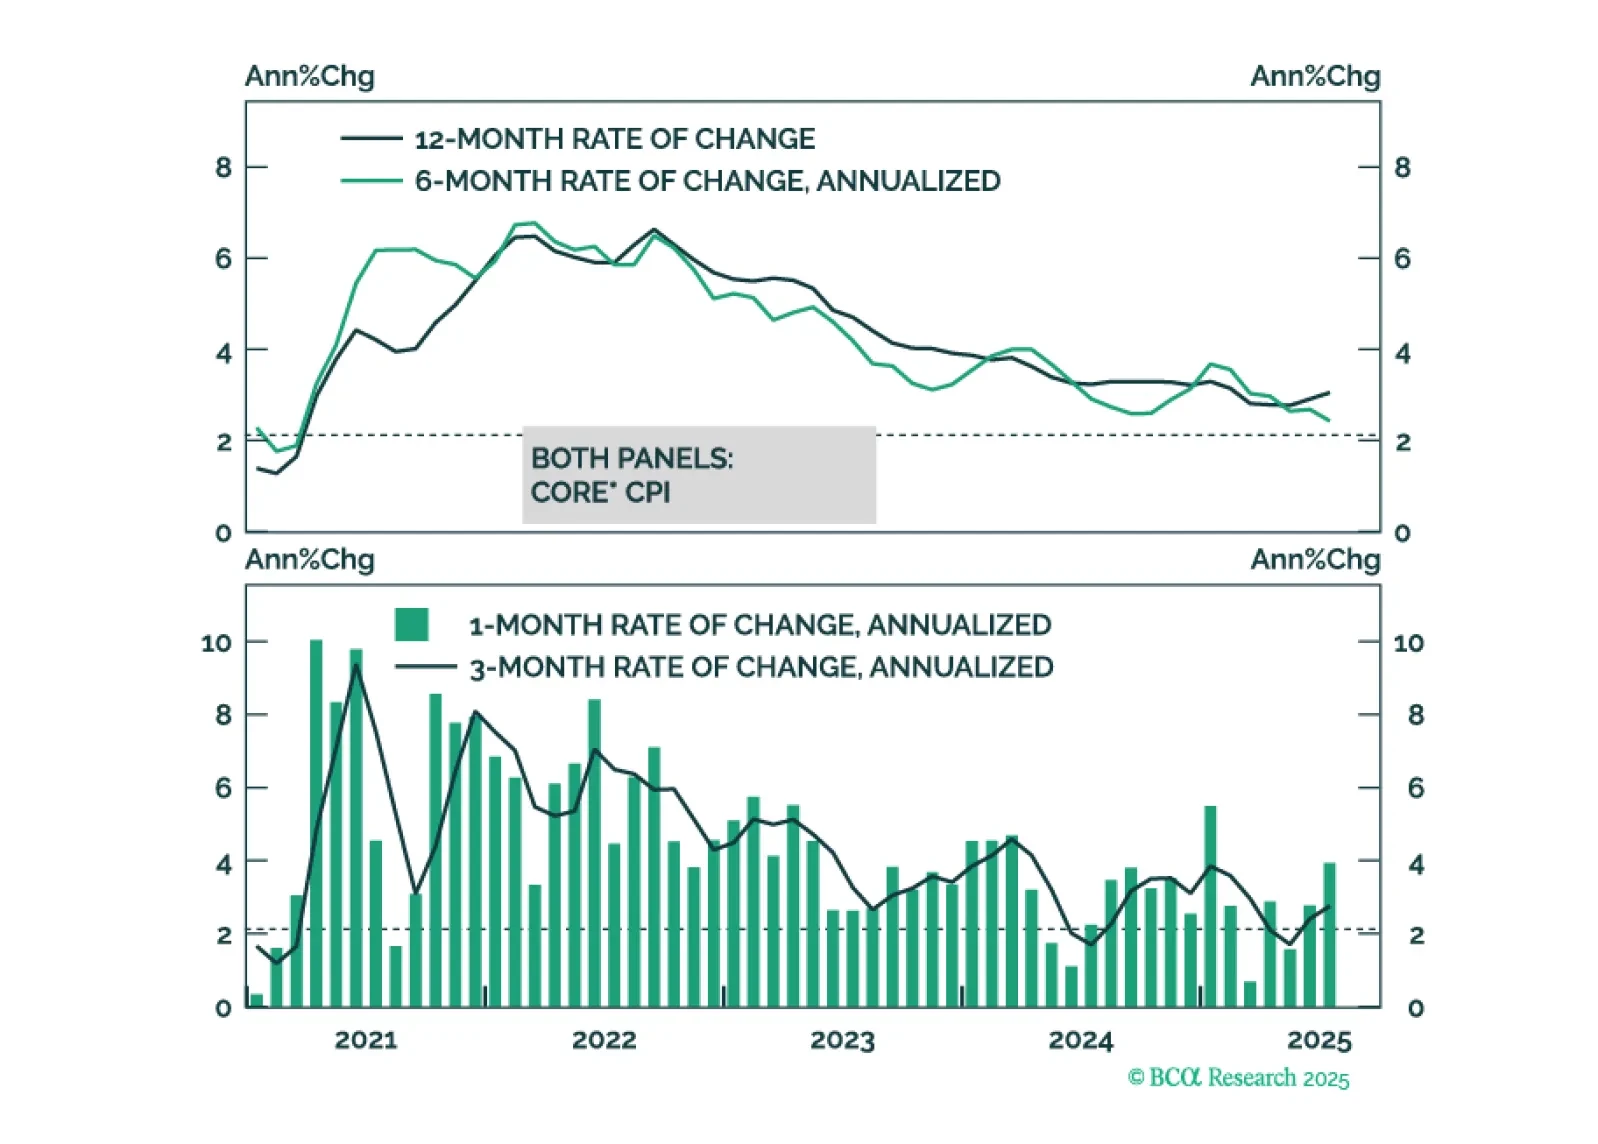
This morning’s CPI report marginally tips the scales in favor of a September rate cut.
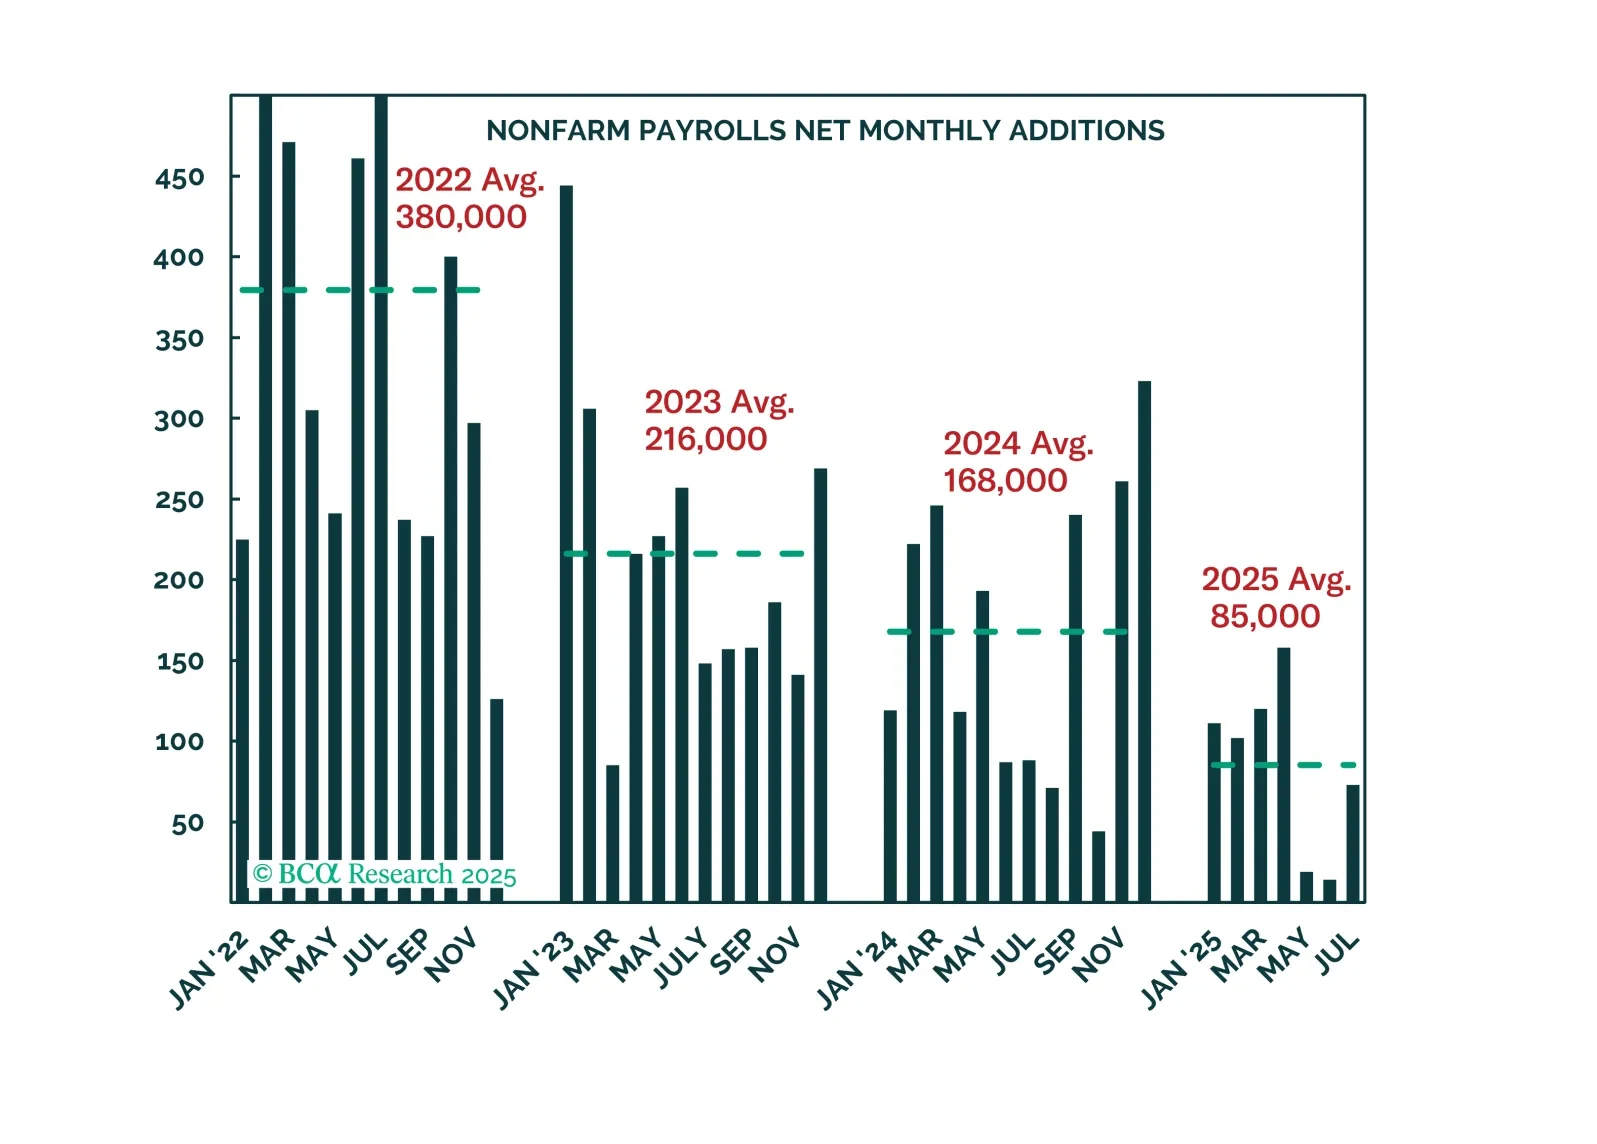
Data received since we began reassessing our bearish stance supported our notion that the economy is not as strong as the investor consensus perceives. But the softness will likely have to intensify in July and August to preserve our defensive recommendations.
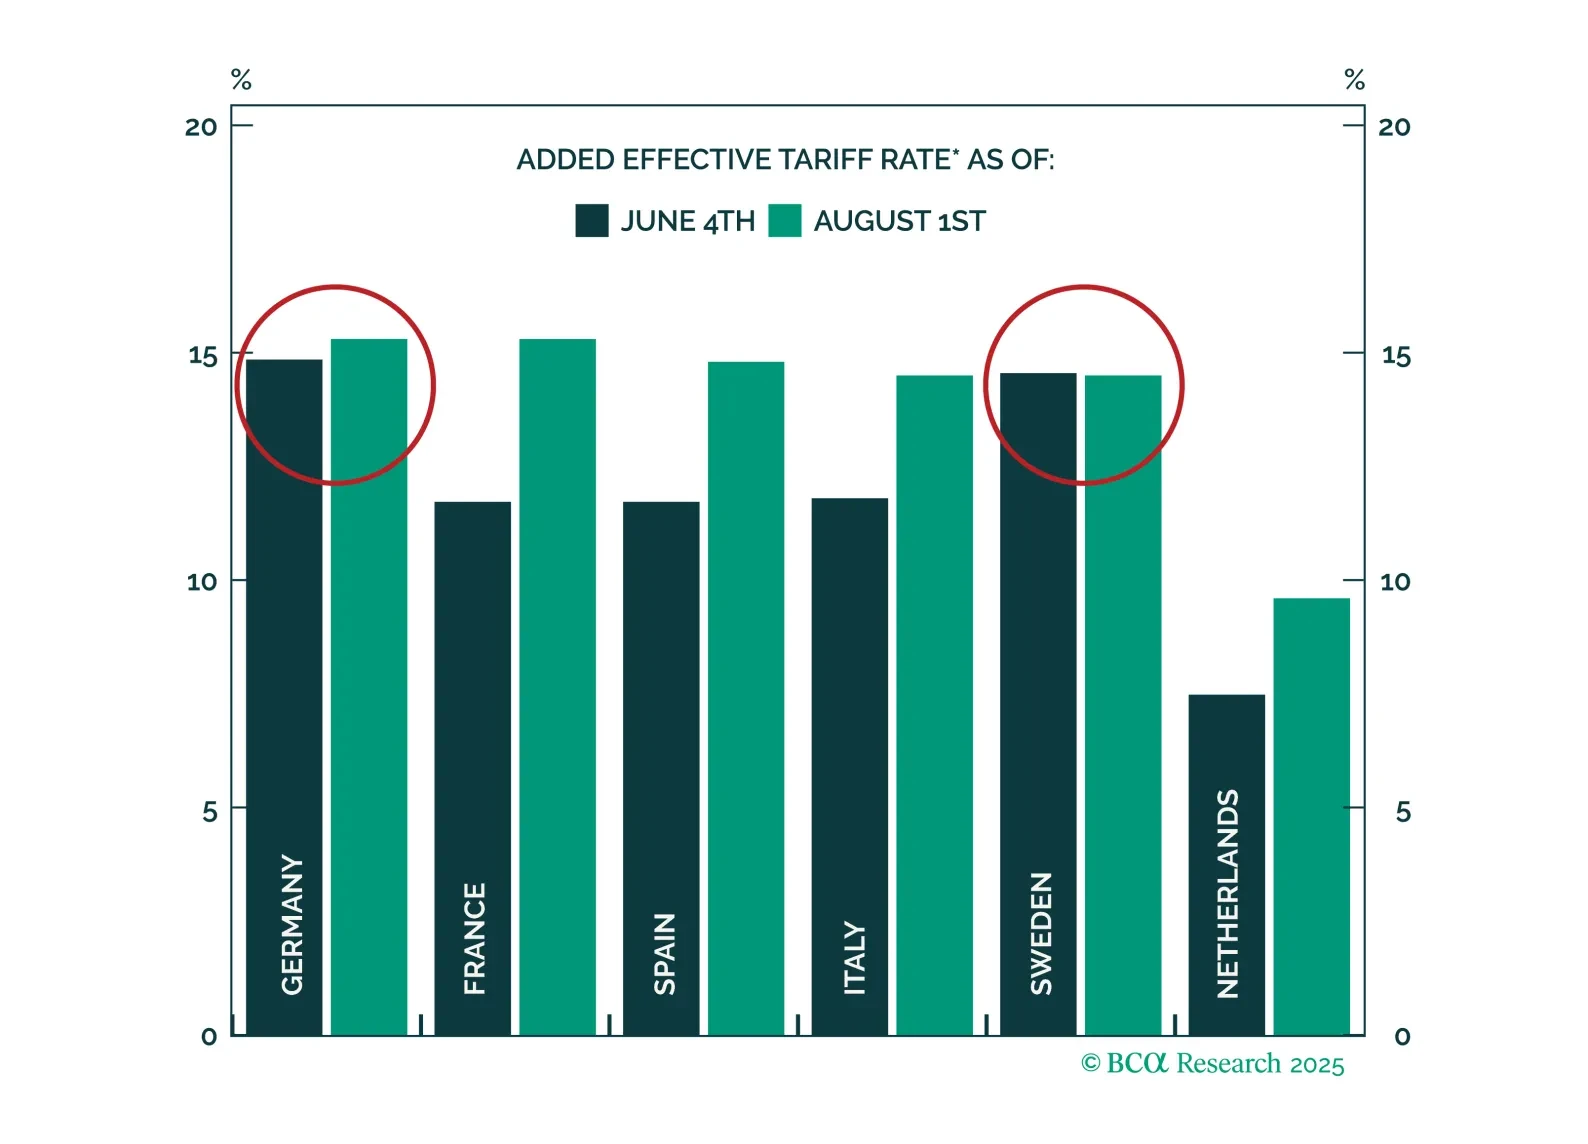
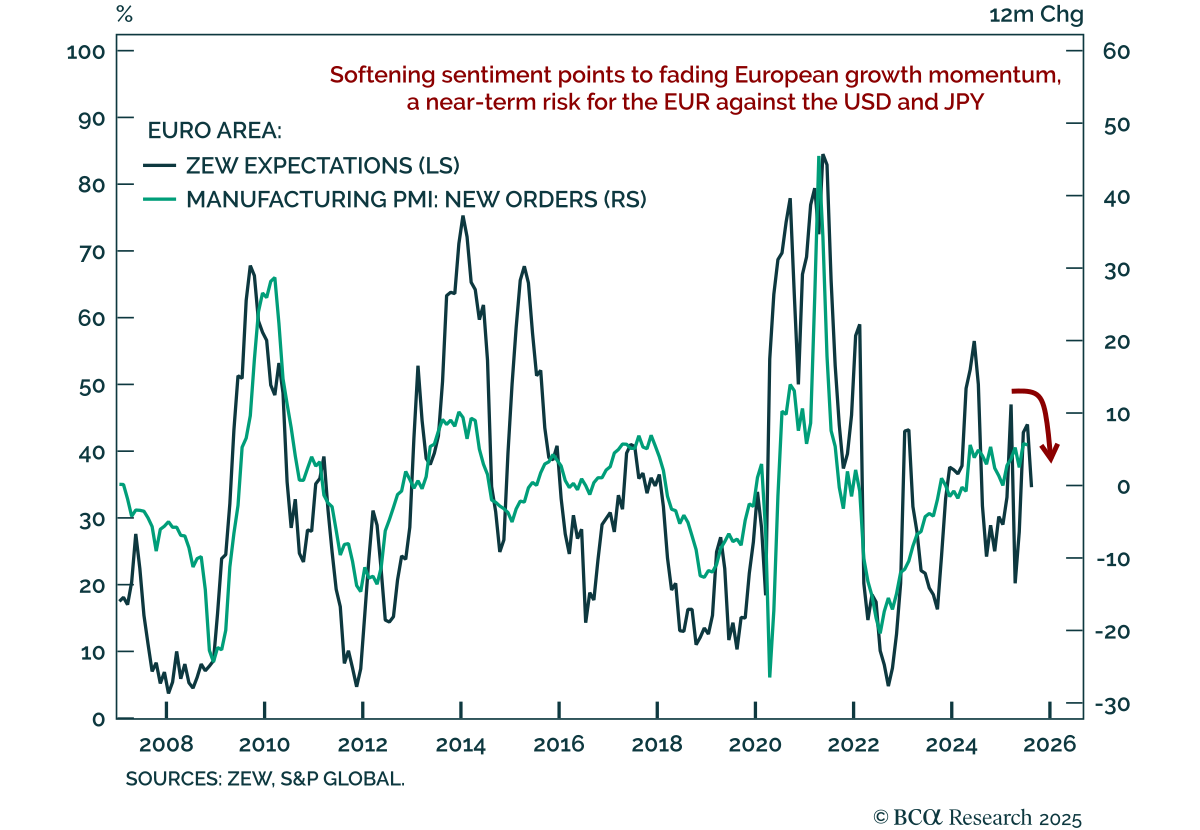
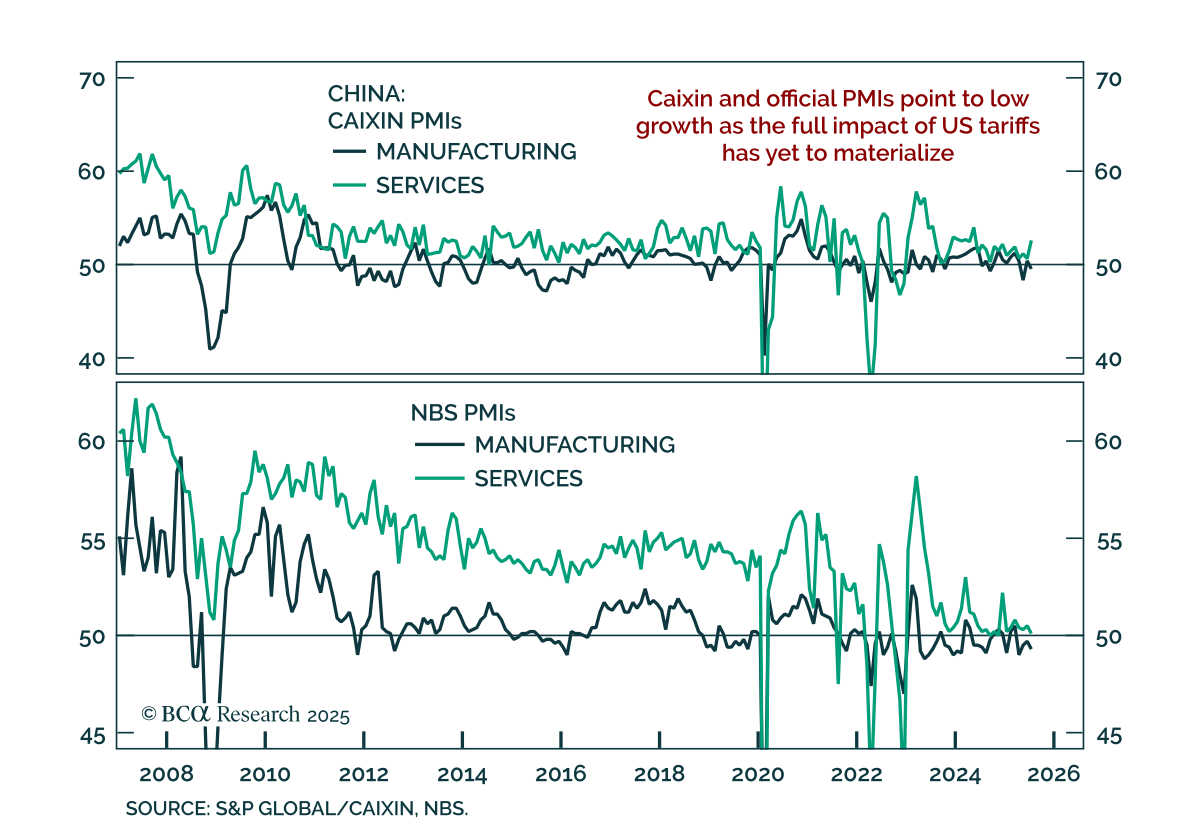
US tariffs will not derail the low-inflation economic recovery underway in the Euro Area. Investors should overweight European equities, focusing on parts of the market more insulated from tariffs.
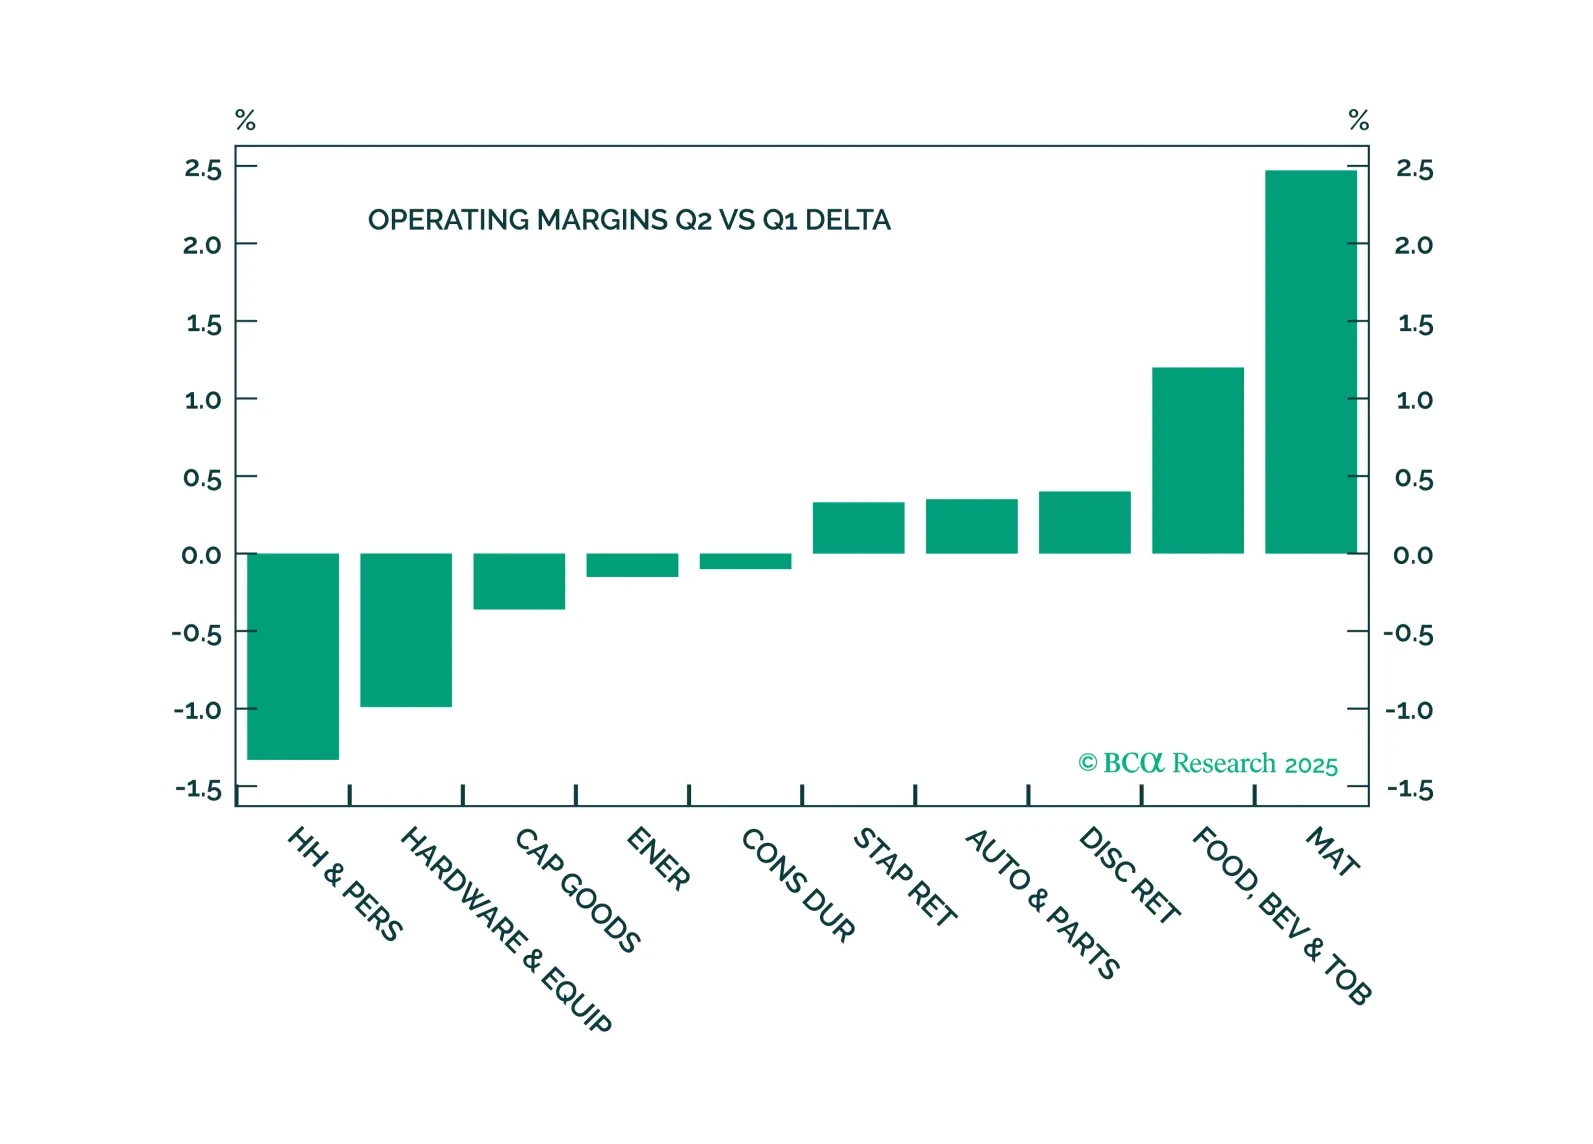
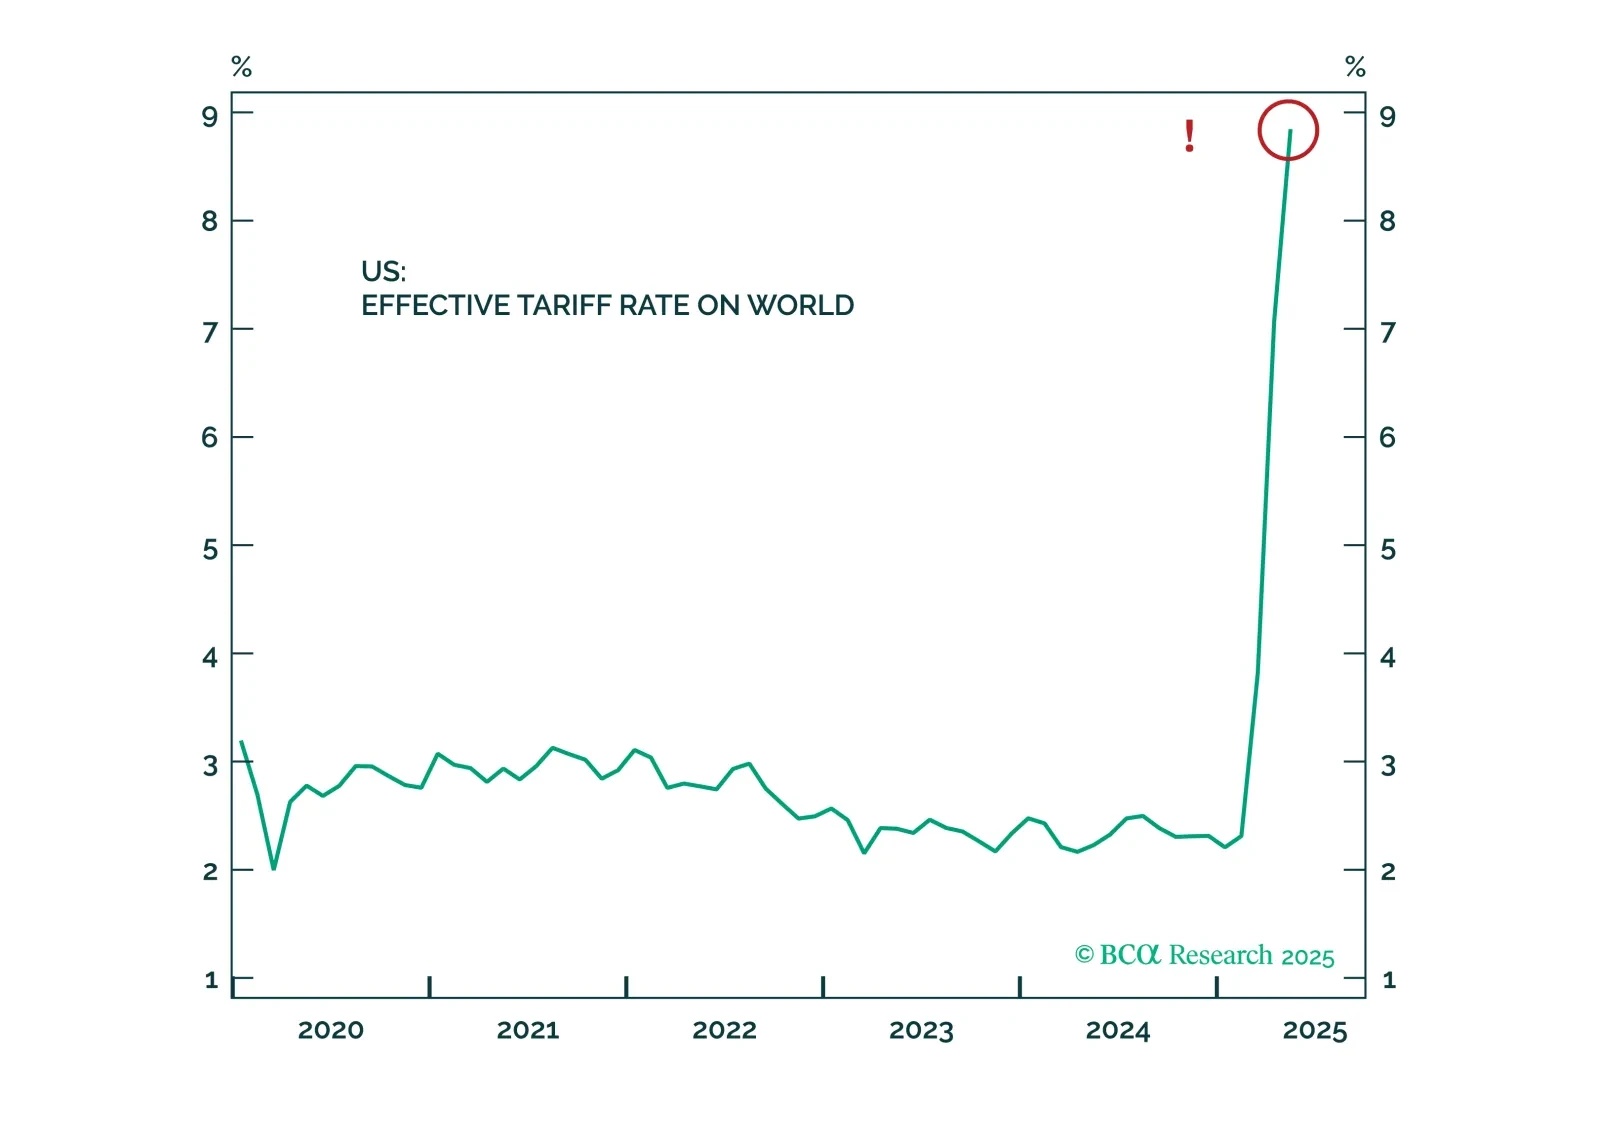
The Q2 earnings season delivered solid earnings and sales growth and resilient margins, reassuring investors that corporate America remains in good health and is capable of navigating economic uncertainty while mitigating the impact of new trade levies. The outlook is generally positive, but with one important caveat: The full effect of tariffs has yet to materialize.
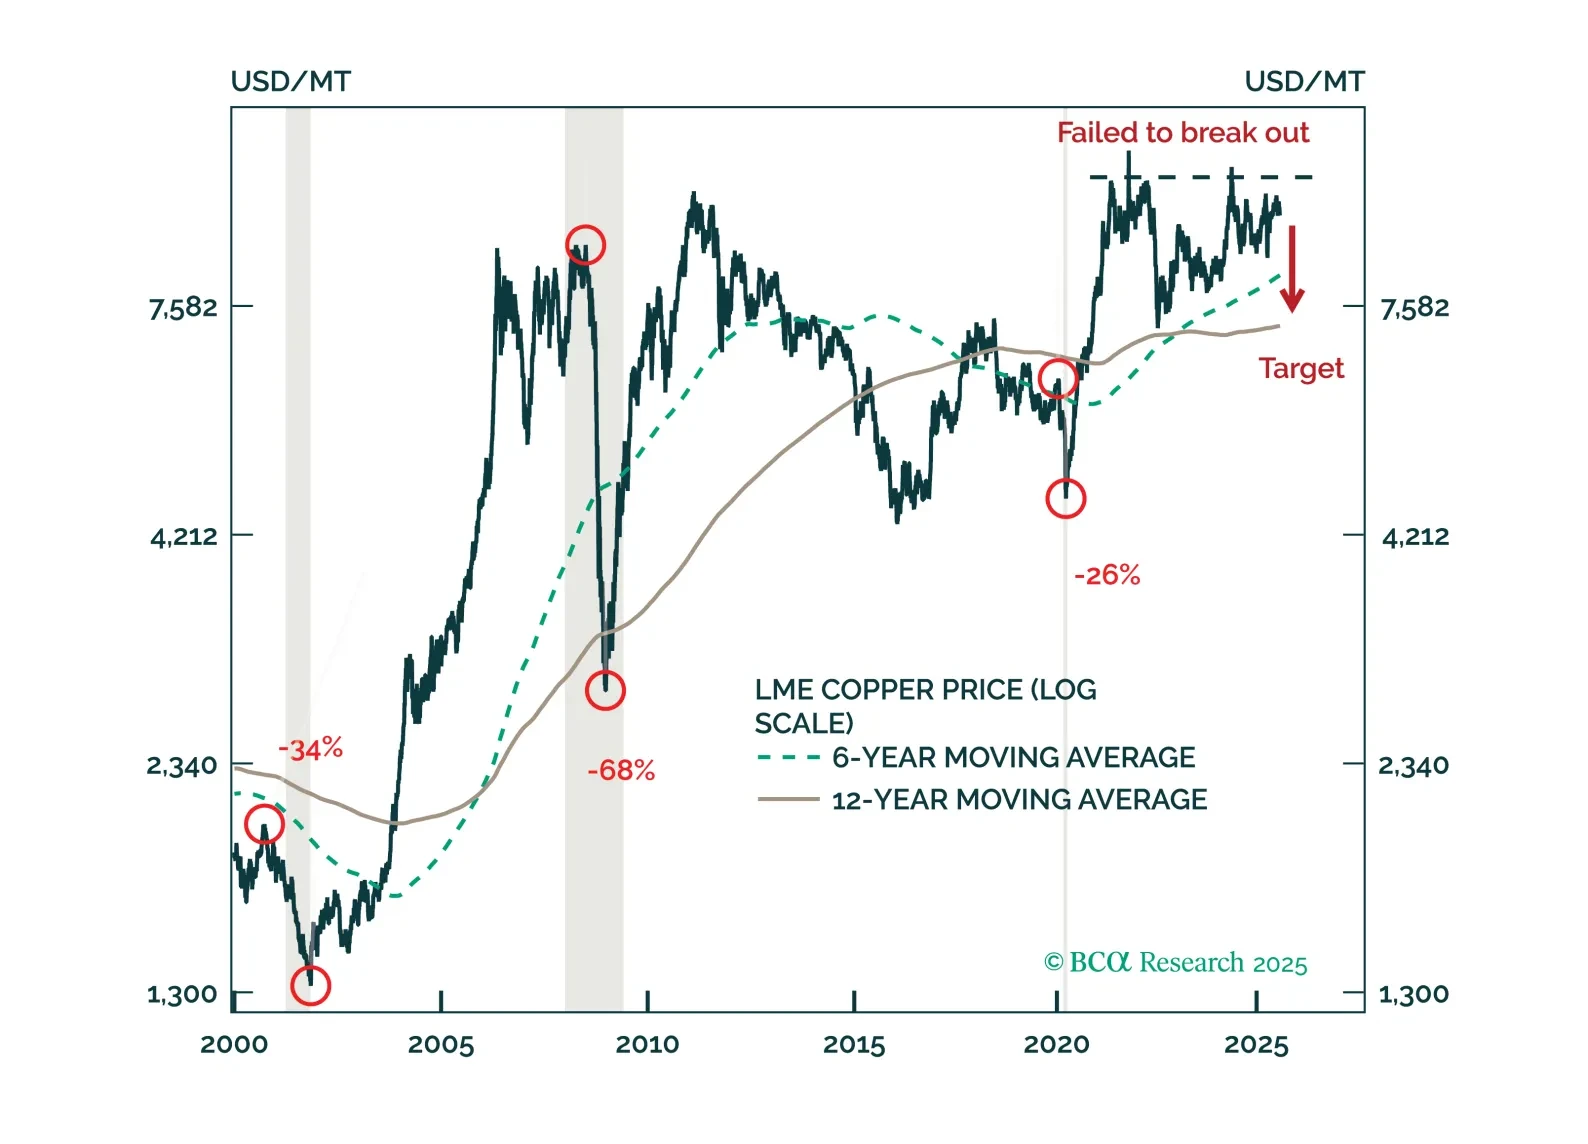
Copper’s unwind – triggered by the refined metal’s US tariff exemption – isn’t over yet. We remain short the red metal on an absolute basis and relative to gold.
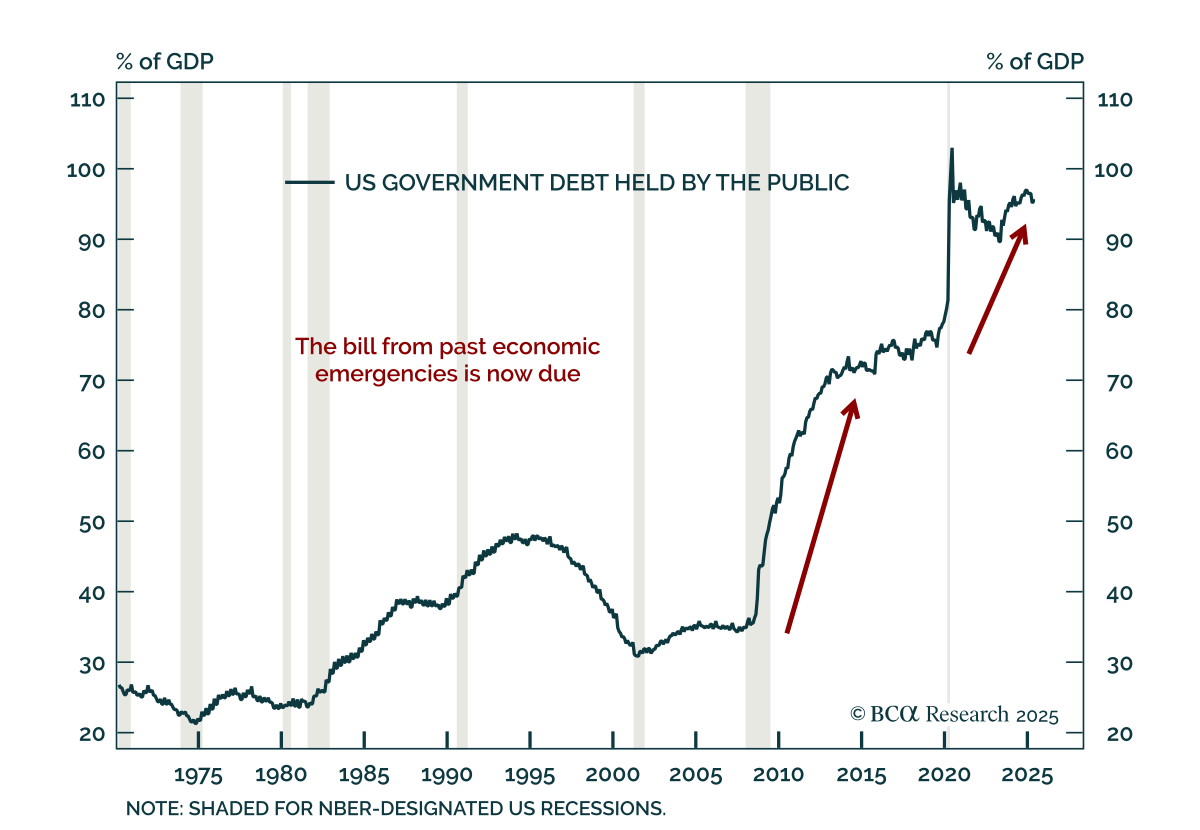
We maintain our 12-month US recession probability at 60%. However, until the “whites of the recession’s eyes” are more clearly visible, we would refrain from moving to a fully defensive stance.
Investors should stick to a defensive stance in the very near term as the Russia-Ukraine conflict and persistent trade tensions cause market volatility.